Saudi Arabia TIN number guide
Tax Identification Number (TIN)
The Tax Identification Number (TIN) is issued by the Zakat, Tax and Customs Authority (ZATCA) to all taxpayers and withholding entities, including government ministries, agencies, and departments, in Saudi Arabia. Once issued, the TIN remains valid for as long as the taxpayer is operational. It serves as the unique identifier for the taxpayer and is utilized for all applicable taxes.
The structure of the Saudi Tax Identification Number (TIN) is as follows:
- The first digit represents the GCC Member State.
- The next eight digits comprise a serial number.
- The final digit is a check digit.
This structure is from the TIN information sheet the Saudi tax authority (then GAZT) submitted to the OECD in 2018. [12]
Format: 10 digits, following the structure above.
 |
| VAT registration certificate with TIN in Saudi Arabia |
The Tax Identification Number (TIN) can be found on various official documents such as TAX, Zakat, excise tax, or VAT Certificates and invoices. The TIN also appears in communications between ZATCA and taxpayers, and on documents ZATCA issues to taxpayers.
For individuals without a TIN, official identification documents like the Saudi national ID or residency ID for non-Saudis serve as alternatives. If the physical Saudi national ID is unavailable for verification, a copy of the national ID along with Saudi passport verification becomes necessary.
VAT number
Businesses in Saudi Arabia registered for VAT are assigned a VAT registration number by ZATCA (Zakat, Tax and Customs Authority). It is 15 digits long, and its first and last digits are both 3. ZATCA's e-invoicing rule BR-KSA-40 states that the seller VAT registration number or seller group VAT registration number "must contain 15 digits. The first and the last digits are "3"." [11]
Format: pattern 3XXXXXXXXXXXXX3 (illustrative; X is any digit).
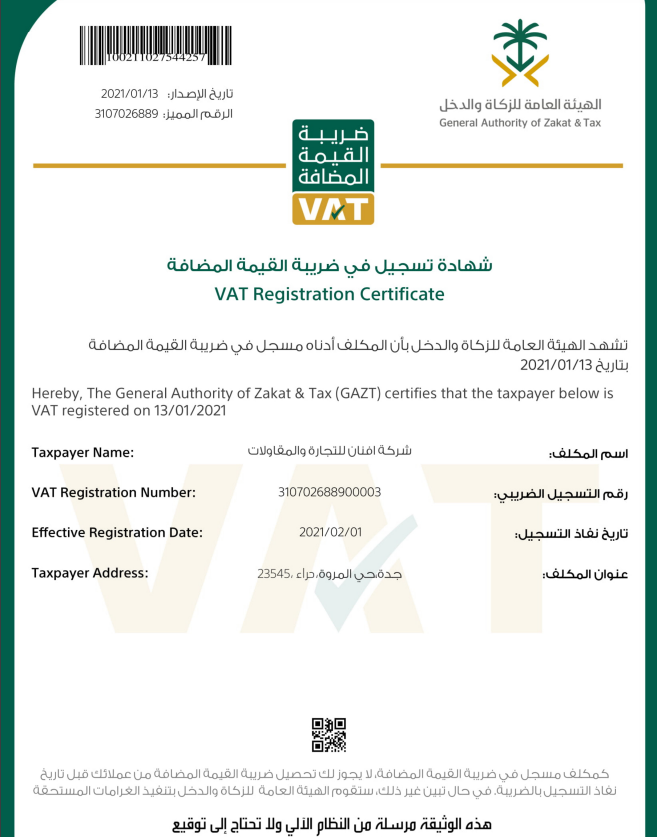 |
| VAT registration certificate in Saudi Arabia |
For VAT registration, invoicing, e-invoicing and filing rules, see the Saudi Arabia VAT guide.
How Lookuptax can help you in VAT validation?
Lookuptax VAT validation revolutionizes VAT number validation with its robust platform, empowering businesses to seamlessly verify VAT numbers across over 100 countries. Our cutting-edge technology ensures accurate and efficient validation, reducing errors and enhancing compliance.
Frequently Asked Questions
Does a foreign company selling digital services to Saudi consumers need to register for VAT even with zero Saudi revenue at launch?
Yes — there is no minimum turnover threshold for non-resident suppliers of electronically supplied services (ESS). VAT registration with ZATCA becomes mandatory within 30 days of the very first B2C supply to a Saudi consumer, regardless of amount. [1] B2B cross-border sales are handled by the reverse-charge mechanism, so the Saudi business customer accounts for VAT and the foreign supplier bears no Saudi VAT liability on those transactions. For B2C, the standard 15% VAT rate applies from day one, and the non-resident registers either directly or through a tax representative (GCC Agreement Art. 50(3); Implementing Regulations Art. 9(3)); ZATCA's guidance on tax representatives says a non-resident must have one, who is jointly liable for the tax. Failure to register before the first sale is a compliance violation subject to ZATCA penalties. [2]
How are Zakat and Corporate Income Tax split in a company with both Saudi and foreign shareholders?
ZATCA applies a proportional apportionment: the Saudi and GCC shareholders' share of the Zakat base is subject to Zakat at 2.5%, while the foreign shareholders' share of net taxable profit is subject to Corporate Income Tax (CIT) at 20%. [3] The two taxes are calculated on entirely different bases — Zakat is computed on equity, retained earnings, and certain liabilities (not just profits), so a loss-making year still generates a Zakat liability if the Zakat base is positive. Both obligations are filed separately with ZATCA. Mixed-ownership joint ventures frequently under-report Zakat by mistakenly applying CIT logic to the Saudi share; ZATCA audits specifically look for this. [4]
What withholding tax rate applies when a Saudi company pays a foreign service provider, and when is it due?
Withholding tax (WHT) rates depend on payment type: royalties and management fees carry 15–20%, rent and dividends 5%, and most other services sourced in the Kingdom 15%. [5] The Saudi-resident payer, not the foreign recipient, is responsible for deducting and remitting WHT to ZATCA within the first 10 days of the following month. Late payment attracts a penalty of 1% of unpaid tax per 30-day period, plus an additional 25% surcharge if ZATCA determines the delay constitutes tax evasion. Foreign suppliers should gross up invoices to account for expected WHT deductions, as the net received will be lower than the invoice face value. [6]
Which businesses are now inside Phase 2 of ZATCA's Fatoora e-invoicing mandate, and what does clearance require?
Phase 2 (the "Integration Phase") rolls out in waves, each defined by a floor on VAT-taxable revenue in specified past years rather than by a revenue band. The most recent is Wave 25, announced on 24 July 2026: taxpayers whose VAT-taxable revenues exceeded SAR 187,500 in any of 2022, 2023, 2024 or 2025 must integrate with the Fatoora platform by 1 February 2027. It halves the Wave 24 criterion of SAR 375,000 (deadline 30 June 2026). ZATCA notifies targeted taxpayers at least six months before their integration date, but the obligation follows the criteria, not the notification. [7] For standard B2B/B2G invoices, real-time clearance is required: the invoice XML must be submitted to the Fatoora portal and a Cryptographic Stamp ID (CSID) returned before the invoice is issued to the buyer. A cleared invoice cannot be reused — rejected invoices require a new UUID and invoice counter value. Simplified B2C invoices must be reported to ZATCA within 24 hours. [8]
Can Saudi-resident subsidiaries of the same group file a single VAT return as a VAT group?
Yes. Two or more legal persons resident in Saudi Arabia can register as a single VAT group under Article 10 of the VAT Implementing Regulations, as amended by ZATCA Board Resolution 01-06-24 of 19 November 2024. Every member must be resident in the Kingdom and eligible to register for VAT, meeting the voluntary registration threshold (SAR 187,500). 50% or more of the capital, voting rights or market value of each member must be owned, directly or indirectly, by the same legal person or persons, or by a legal person (inside or outside the group) that exercises control over the other members. No member may be licensed to operate in a special zone with customs-suspension status or be a member of another tax group, and persons eligible for a VAT refund under Article 70 are excluded, except licensed real-estate developers supplying real estate only to their employees and donors to public-benefit projects. The group is treated as a single taxable person with one tax number: supplies between members are outside the scope of VAT, the group representative files the group's returns, and each member remains jointly and severally liable for the group's VAT obligations. [9] [10]