Bangladesh compliance calendar

10 recurring Turnover Tax, Value Added Tax (VAT), VAT deduction at source (VDS) and আবগারি শুল্ক (excise duty) on air tickets obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Bangladesh rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
31
1
2
3
4
5
6
7
8
9
10
11
Payment Return filing Report / listing

Dates already include the weekend and public-holiday shift where Bangladesh applies one — 2 of 10 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Mushak-9.1 — VAT return (quarterly)

Value Added Tax (VAT) and Supplementary Duty · Quarterly · return filing

15th of the month after the quarter ends Verified 2026-09-07
Who files
Every VAT-registered person, and anyone registrable who has not yet registered - the registration threshold is BDT 5,000,000 of turnover in any 12 months, and a list of activities requires registration whatever the turnover
Notes
Bangladesh moved from monthly to quarterly VAT returns on 1 July 2026, so one return now covers three months and falls due 15 days after the quarter ends. Pay first: the net tax has to reach the government treasury before the return can be submitted, which makes the 15th a payment deadline as much as a filing one. Where the 15th is a government holiday the return is due on the next working day. The Board can also extend the date for everyone by public order, without interest or penalty, so treat the date shown as the earliest a return can be due and never the latest.
Source
মূল্য সংযোজন কর ও সম্পূরক শুল্ক আইন, ২০১২ — ধারা ৬৪ (দাখিলপত্র পেশ) Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs
See the source text
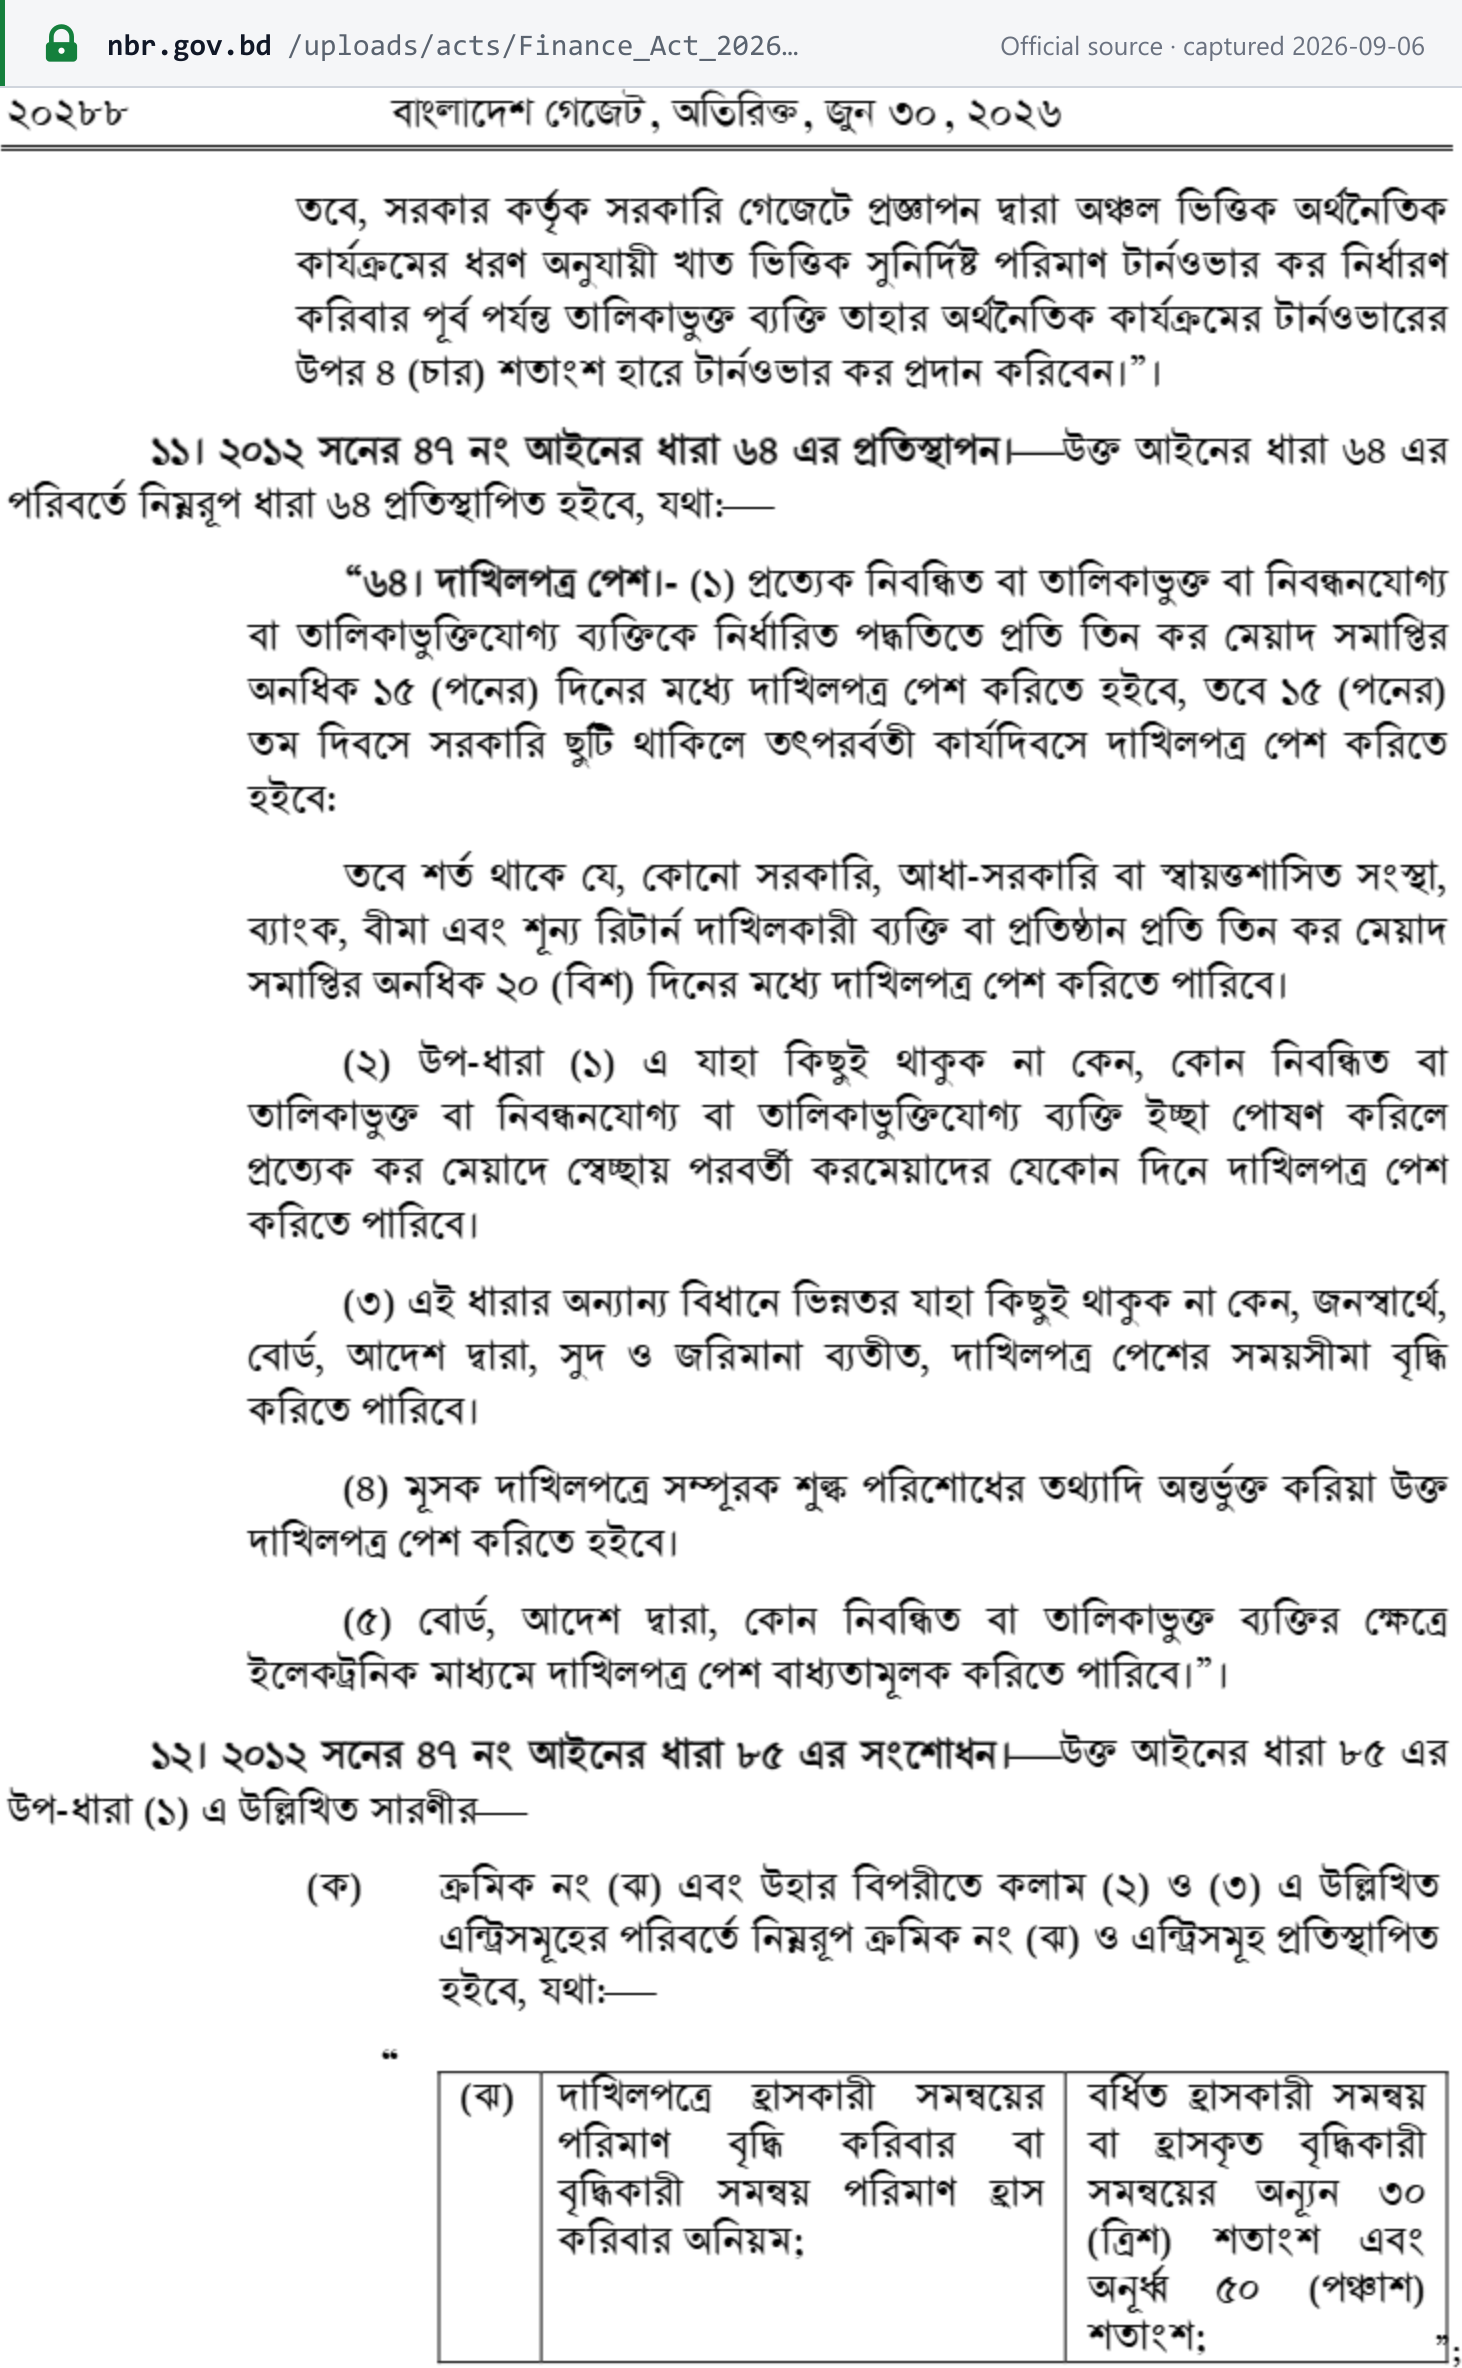
“প্রত্যেক নিবন্ধিত বা তালিকাভুক্ত বা নিবন্ধনযোগ্য বা তালিকাভুক্তিযোগ্য ব্যক্তিকে নির্ধারিত পদ্ধতিতে প্রতি তিন কর মেয়াদ সমাপ্তির অনধিক ১৫ (পনের) দিনের মধ্যে দাখিলপত্র পেশ করিতে হইবে, তবে ১৫ (পনের) তম দিবসে সরকারি ছুটি থাকিলে তৎপরবর্তী কার্যদিবসে দাখিলপত্র পেশ করিতে হইবে:”
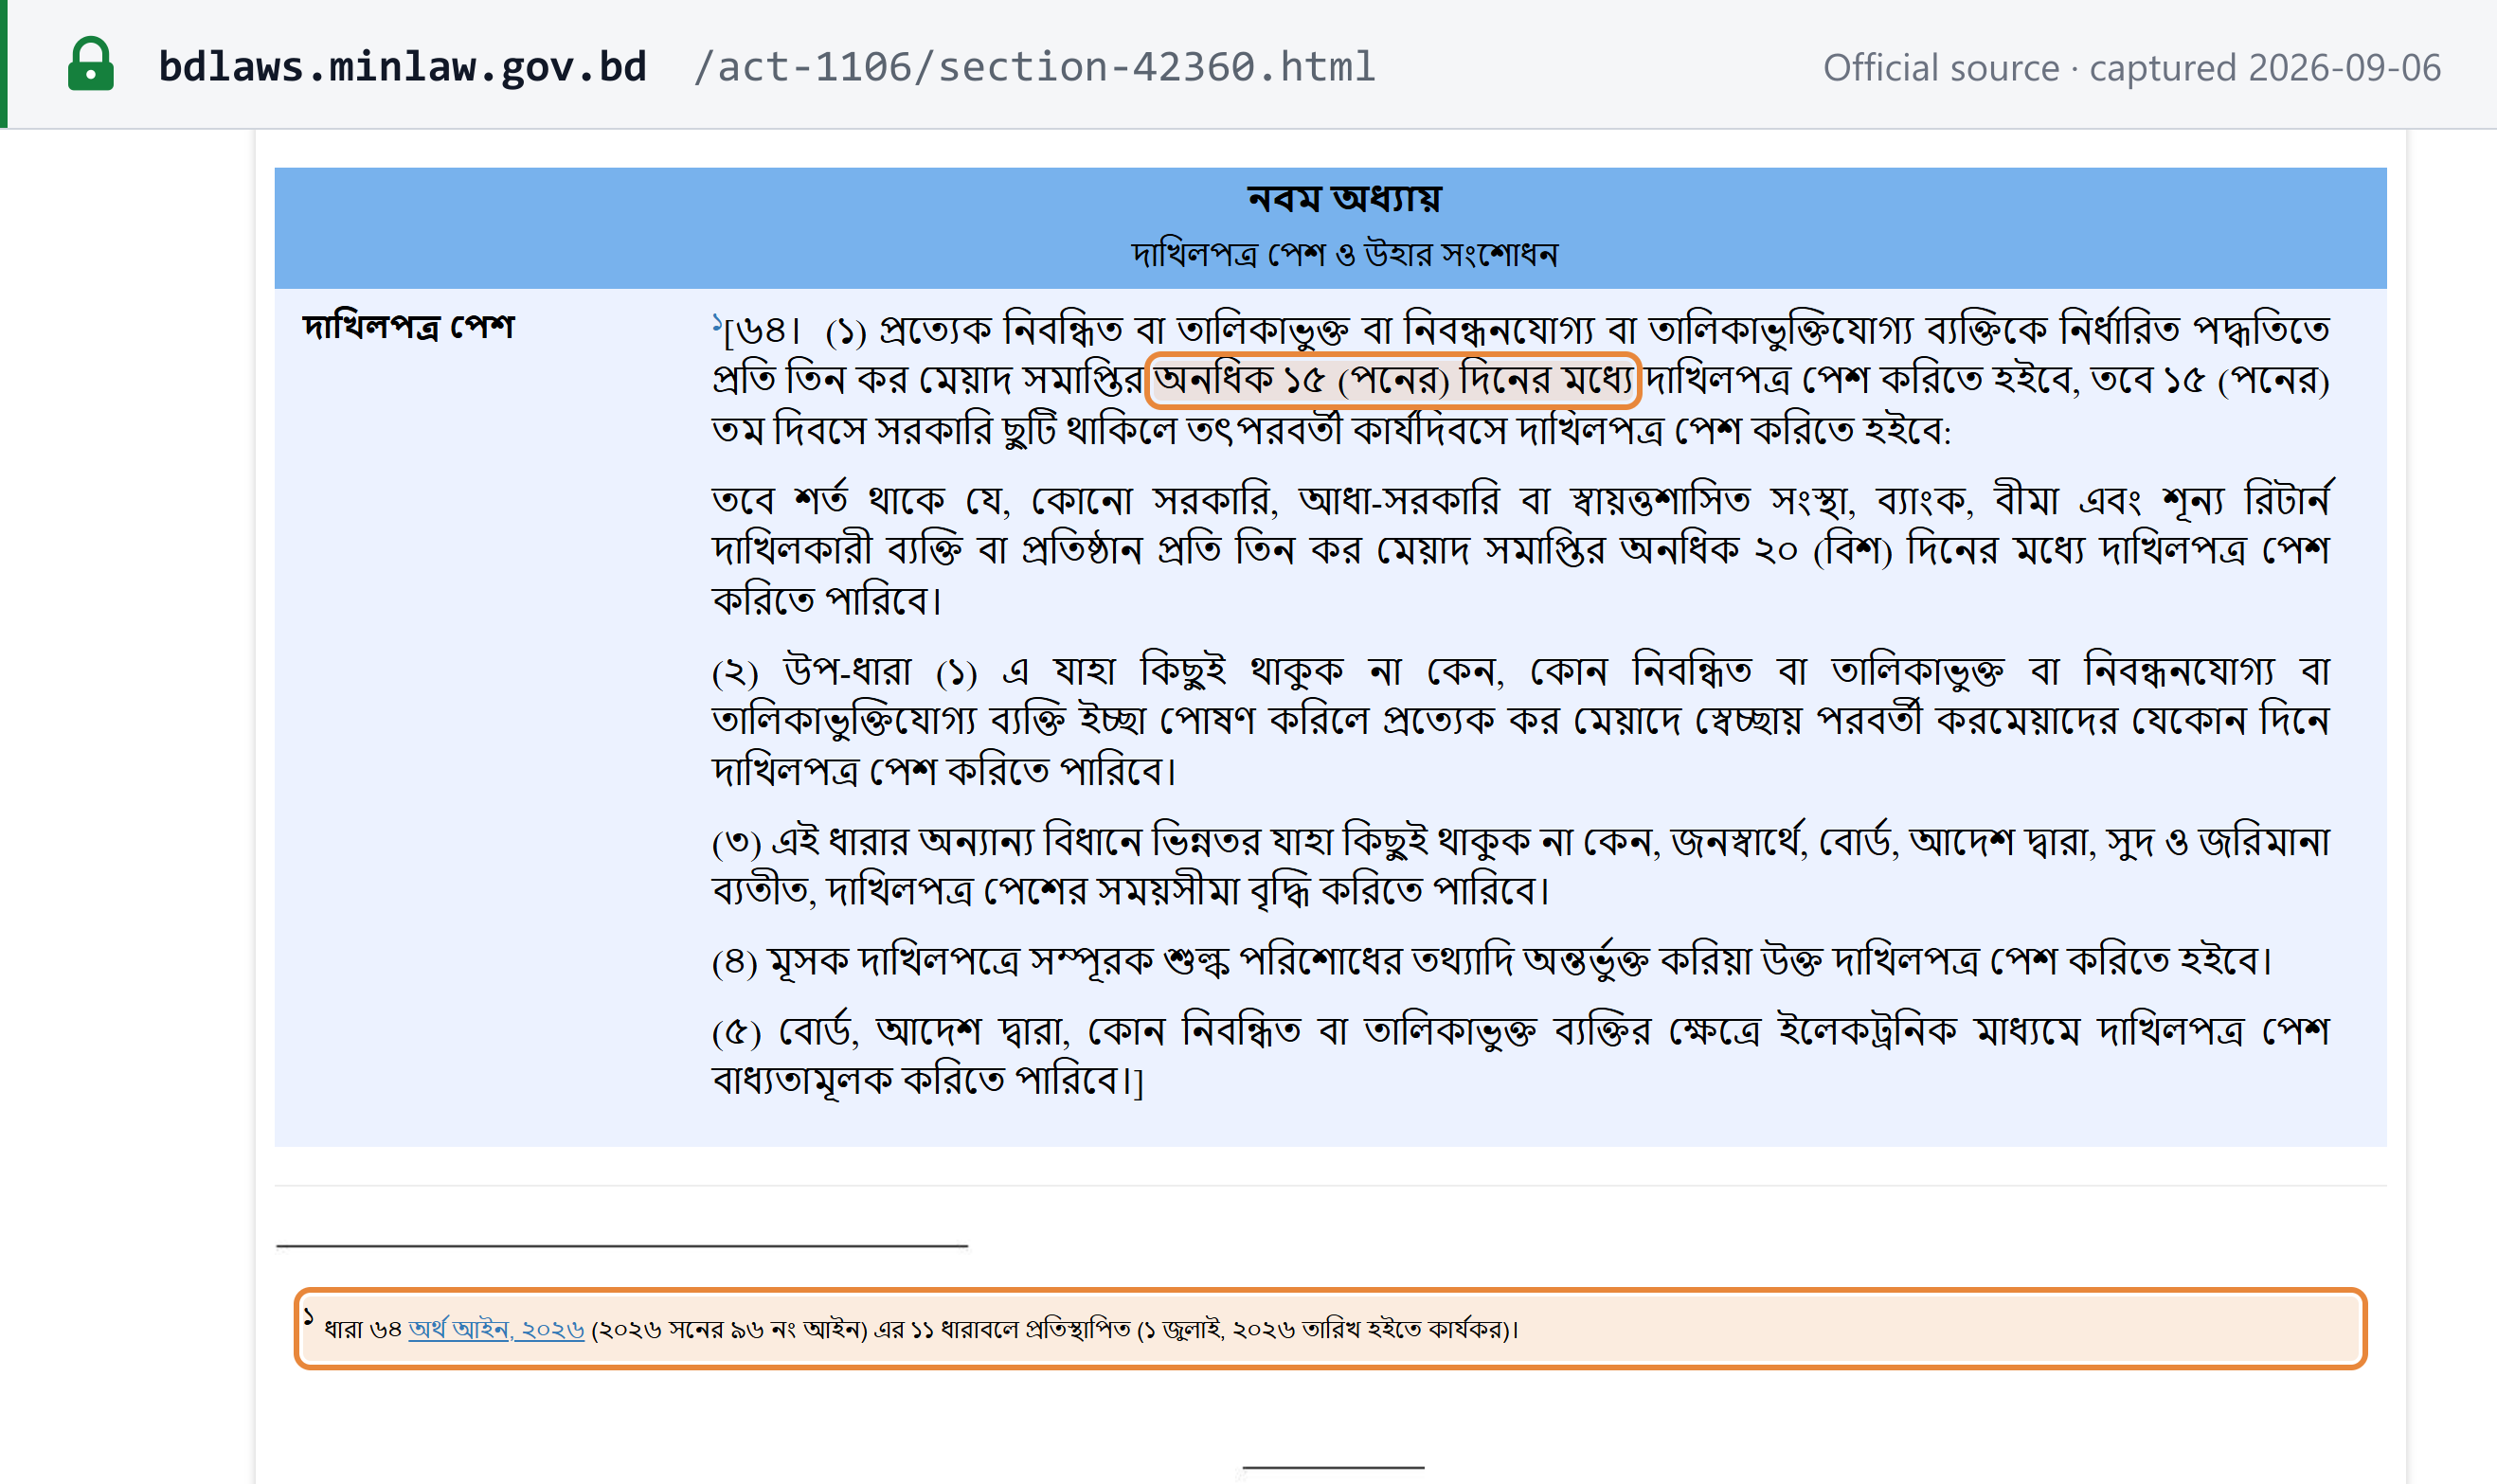
Screenshot of Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs showing the Mushak-9.1 — VAT return (quarterly) deadline Open full size Captured from Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs on 2026-09-07
Mushak-9.1 — VAT return (quarterly, 20-day permission)

Value Added Tax (VAT) and Supplementary Duty · Quarterly · return filing

20th of the month after the quarter ends Verified 2026-09-07
Who files
Government, semi-government and autonomous bodies, banks and insurance companies, and any person or entity filing a nil return for the quarter
Notes
Government, semi-government and autonomous bodies, banks and insurers may take 20 days after the quarter instead of 15 - and so may anyone filing a nil return, including a business that normally files on the 15th but had no activity in that quarter. It is a permission rather than a separate regime, so filing by the 15th stays open to you. Worth knowing: the holiday extension written into the 15-day rule is not repeated for the 20th, so a 20th falling on a weekly or public holiday has no reprieve of its own in the Act.
Source
মূল্য সংযোজন কর ও সম্পূরক শুল্ক আইন, ২০১২ — ধারা ৬৪(১) শর্তাংশ Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs
See the source text
“তবে শর্ত থাকে যে, কোনো সরকারি, আধা-সরকারি বা স্বায়ত্তশাসিত সংস্থা, ব্যাংক, বীমা এবং শূন্য রিটার্ন দাখিলকারী ব্যক্তি বা প্রতিষ্ঠান প্রতি তিন কর মেয়াদ সমাপ্তির অনধিক ২০ (বিশ) দিনের মধ্যে দাখিলপত্র পেশ করিতে পারিবে।”
Screenshot of Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs showing the Mushak-9.1 — VAT return (quarterly, 20-day permission) deadline Open full size Captured from Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs on 2026-09-07
Mushak-9.1 - VAT return (voluntary monthly filing)

Value Added Tax (VAT) and Supplementary Duty · Monthly · return filing

last day of the month after the month ends Verified 2026-09-07
Who files
Any registered, enlisted, registrable or enlistable person who chooses to keep filing every tax period rather than every quarter
Notes
Quarterly filing is the rule, not an obligation to wait: you may choose to keep filing every month, and the Act gives you any day of the following month to do it. Businesses in a regular refund position usually do, because a quarterly cycle holds their money three months instead of one. Note the deadline is the month end rather than the 15th, and the holiday extension written into the 15-day rule does not reach it.
Source
মূল্য সংযোজন কর ও সম্পূরক শুল্ক আইন, ২০১২ — ধারা ৬৪(২) Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs
See the source text
“প্রত্যেক নিবন্ধিত বা তালিকাভুক্ত বা নিবন্ধনযোগ্য বা তালিকাভুক্তিযোগ্য ব্যক্তিকে নির্ধারিত পদ্ধতিতে প্রতি তিন কর মেয়াদ সমাপ্তির অনধিক ১৫ (পনের) দিনের মধ্যে দাখিলপত্র পেশ করিতে হইবে, তবে ১৫ (পনের) তম দিবসে সরকারি ছুটি থাকিলে তৎপরবর্তী কার্যদিবসে দাখিলপত্র পেশ করিতে হইবে:”
Screenshot of Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs showing the Mushak-9.1 - VAT return (voluntary monthly filing) deadline Open full size Captured from Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs on 2026-09-07
Mushak-9.2 — turnover tax return (quarterly)

Turnover Tax · Quarterly · return filing

15th of the month after the quarter ends Verified 2026-09-07
Who files
Persons enlisted for turnover tax - turnover above BDT 3,000,000 but not above BDT 5,000,000 in any 12 months
Notes
Businesses enlisted for turnover tax rather than registered for VAT file this return instead, on the same quarterly cycle and the same 15-day deadline. Turnover tax runs at 4 per cent of turnover from 1 July 2026, up from 3 per cent, and the government may fix a specific amount by sector and area instead. As with the VAT return the tax must be paid before the return goes in - the payment is a precondition to filing, not a separate date later in the month.
Source
মূল্য সংযোজন কর ও সম্পূরক শুল্ক আইন, ২০১২ — ধারা ৬৪ (দাখিলপত্র পেশ) Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs
See the source text
“প্রত্যেক নিবন্ধিত বা তালিকাভুক্ত বা নিবন্ধনযোগ্য বা তালিকাভুক্তিযোগ্য ব্যক্তিকে নির্ধারিত পদ্ধতিতে প্রতি তিন কর মেয়াদ সমাপ্তির অনধিক ১৫ (পনের) দিনের মধ্যে দাখিলপত্র পেশ করিতে হইবে, তবে ১৫ (পনের) তম দিবসে সরকারি ছুটি থাকিলে তৎপরবর্তী কার্যদিবসে দাখিলপত্র পেশ করিতে হইবে:”
Screenshot of Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs showing the Mushak-9.2 — turnover tax return (quarterly) deadline Open full size Captured from Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs on 2026-09-07
Annual audited financial statements to the Commissioner

Value Added Tax (VAT) · Annually · report / listing

31st December each year Verified 2026-09-07
Who files
Registered limited companies
Notes
A registered limited company must lodge the audited financial statements for its previous business year with the Commissioner within the first six tax periods of the running financial year. The year begins on 1 July and a tax period is a calendar month, so that lands on 31 December. The Commissioner may allow a further six tax periods on a reasoned application, taking it to 30 June. This is an obligation under the VAT law owed to the VAT authority - meeting the company-registry filing date does nothing for it.
Source
মূল্য সংযোজন কর ও সম্পূরক শুল্ক আইন, ২০১২ — ধারা ৯০ক Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs
See the source text
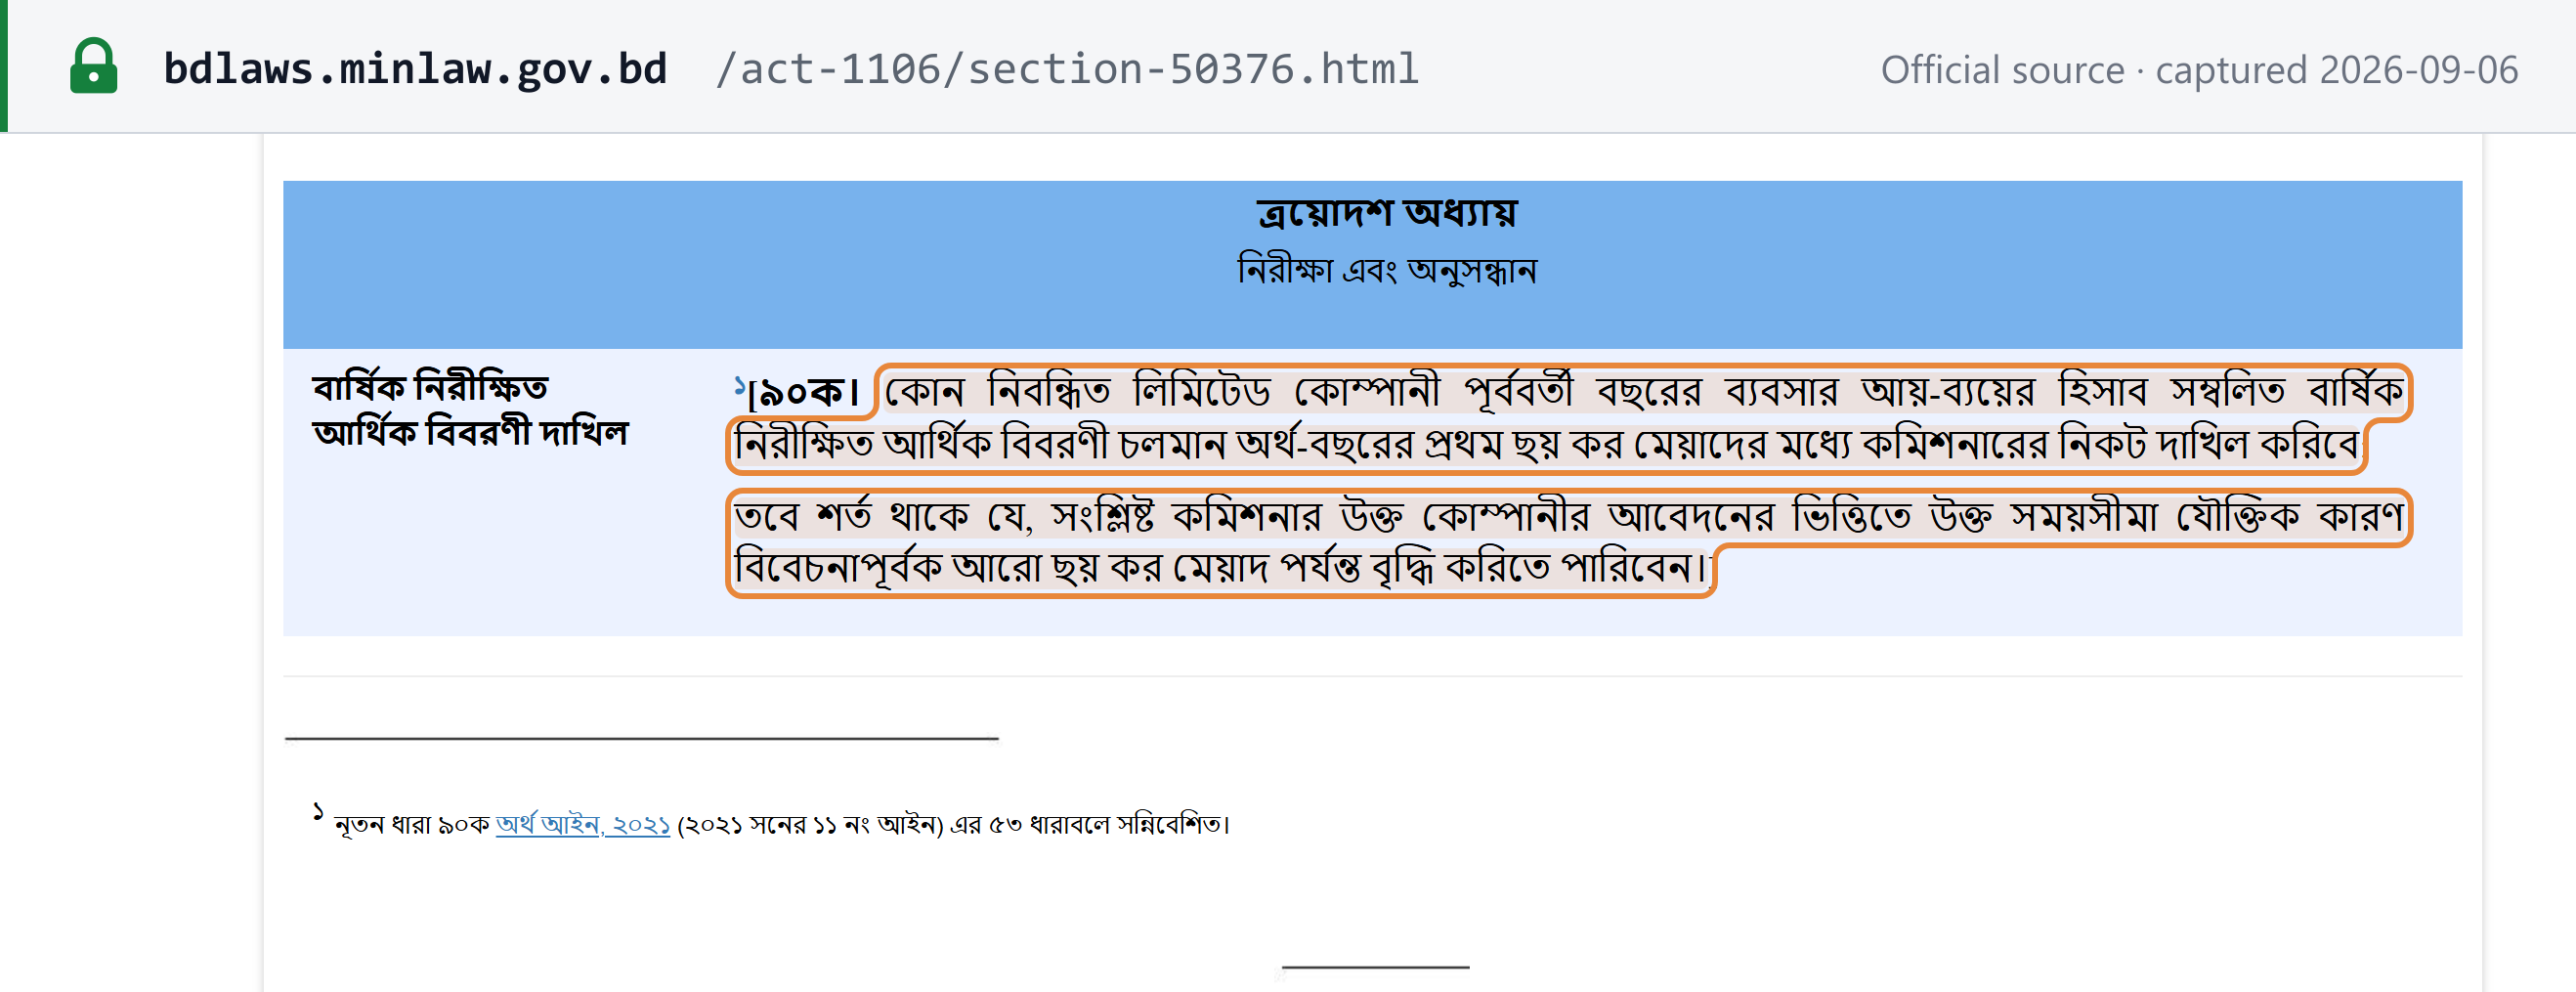
“৯০ক। কোন নিবন্ধিত লিমিটেড কোম্পানী পূর্ববর্তী বছরের ব্যবসার আয়-ব্যয়ের হিসাব সম্বলিত বার্ষিক নিরীক্ষিত আর্থিক বিবরণী চলমান অর্থ-বছরের প্রথম ছয় কর মেয়াদের মধ্যে কমিশনারের নিকট দাখিল করিবে:”
Screenshot of Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs showing the Annual audited financial statements to the Commissioner deadline Open full size Captured from Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs on 2026-09-07
VAT deducted at source — treasury deposit and Mushak-6.6 certificate

VAT deduction at source (VDS) · One-off · payment

within 15 days of payment of the consideration to the supplier Verified 2026-09-07
Who files
Withholding entities that are not themselves registered or enlisted, on each payment from which VAT is deducted at source
Notes
A buyer who is not registered or enlisted but has to withhold VAT at source gets 15 days from paying the supplier to deposit that VAT with the government treasury, and then three working days from the deposit to give the supplier a deduction certificate. The clock runs from the payment itself, not from the invoice or the end of a month, so every payment carries its own deadline. Where the bill is settled by an Accounts Officer the certificate instead follows notification by that officer, and where the supplier is unregistered or issues no invoice no certificate is issued at all.
Source
Value Added Tax and Supplementary Duty Rules, 2016 - rule 40(1)(f)(iii), authentic English text, PDF page 31 National Board of Revenue
See the source text
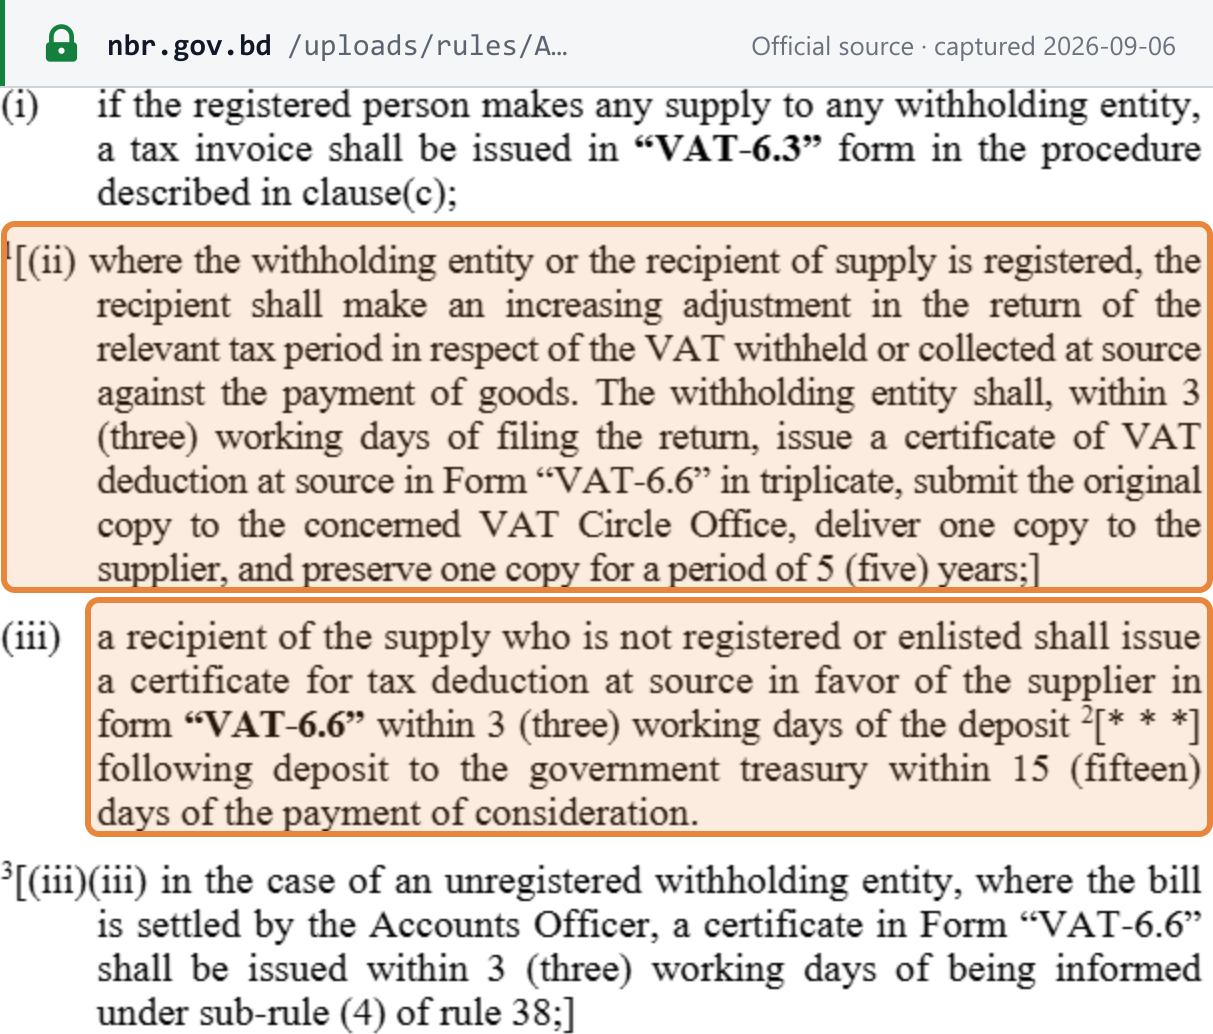
“(iii) a recipient of the supply who is not registered or enlisted shall issue a certificate for tax deduction at source in favor of the supplier in form "VAT-6.6" within 3 (three) working days of the deposit 2[* * *] following deposit to the government treasury within 15 (fifteen) days of the payment of consideration.”
Screenshot of National Board of Revenue showing the VAT deducted at source — treasury deposit and Mushak-6.6 certificate deadline Open full size Captured from National Board of Revenue on 2026-09-07

Mushak-6.6 — certificate of VAT deducted at source (registered withholding entity)

VAT deduction at source (VDS) · One-off · report / listing

within 3 business days of filing the return for the tax period in which the VAT was withheld Verified 2026-09-07
Who files
Withholding entities that are themselves registered or enlisted
Notes
Where the withholding entity is itself registered, the VAT withheld is settled as an increasing adjustment in that period's return rather than by a separate treasury deposit - so the certificate follows the return, not the payment. Three working days from filing to issue it in triplicate: the original goes to your VAT Circle Office, one copy to the supplier, and one is kept for five years. This route only came in on 1 July 2025, so a procedure written before then will not describe it.
Source
Value Added Tax and Supplementary Duty Rules, 2016 - rule 40(1)(f)(ii), authentic English text, PDF page 31 National Board of Revenue
See the source text
“the recipient shall make an increasing adjustment in the return of the relevant tax period in respect of the VAT withheld or collected at source against the payment of goods. The withholding entity shall, within 3 (three) working days of filing the return, issue a certificate of VAT deduction at source in Form "VAT-6.6" in triplicate, submit the original copy to the concerned VAT Circle Office, deliver one copy to the supplier, and preserve one copy for a period of 5 (five) years;”
Screenshot of National Board of Revenue showing the Mushak-6.6 — certificate of VAT deducted at source (registered withholding entity) deadline Open full size Captured from National Board of Revenue on 2026-09-07

Excise duty on air tickets - monthly deposit and report

আবগারি শুল্ক (excise duty) on air tickets · Monthly · payment

30th of the month after the month ends Verified 2026-09-07
Who files
Airlines and ticket sellers collecting excise duty on air tickets issued in Bangladesh
Notes
Excise duty collected on air tickets has its own monthly cycle, separate from VAT and a fortnight later in the month. The duty taken in one month must be paid into the government treasury by challan by the 30th of the next, and a report in the prescribed form, with a copy of the challan, goes to your local VAT office by the same date. Both limbs share the deadline, so treat it as one date with two things due on it.
Source
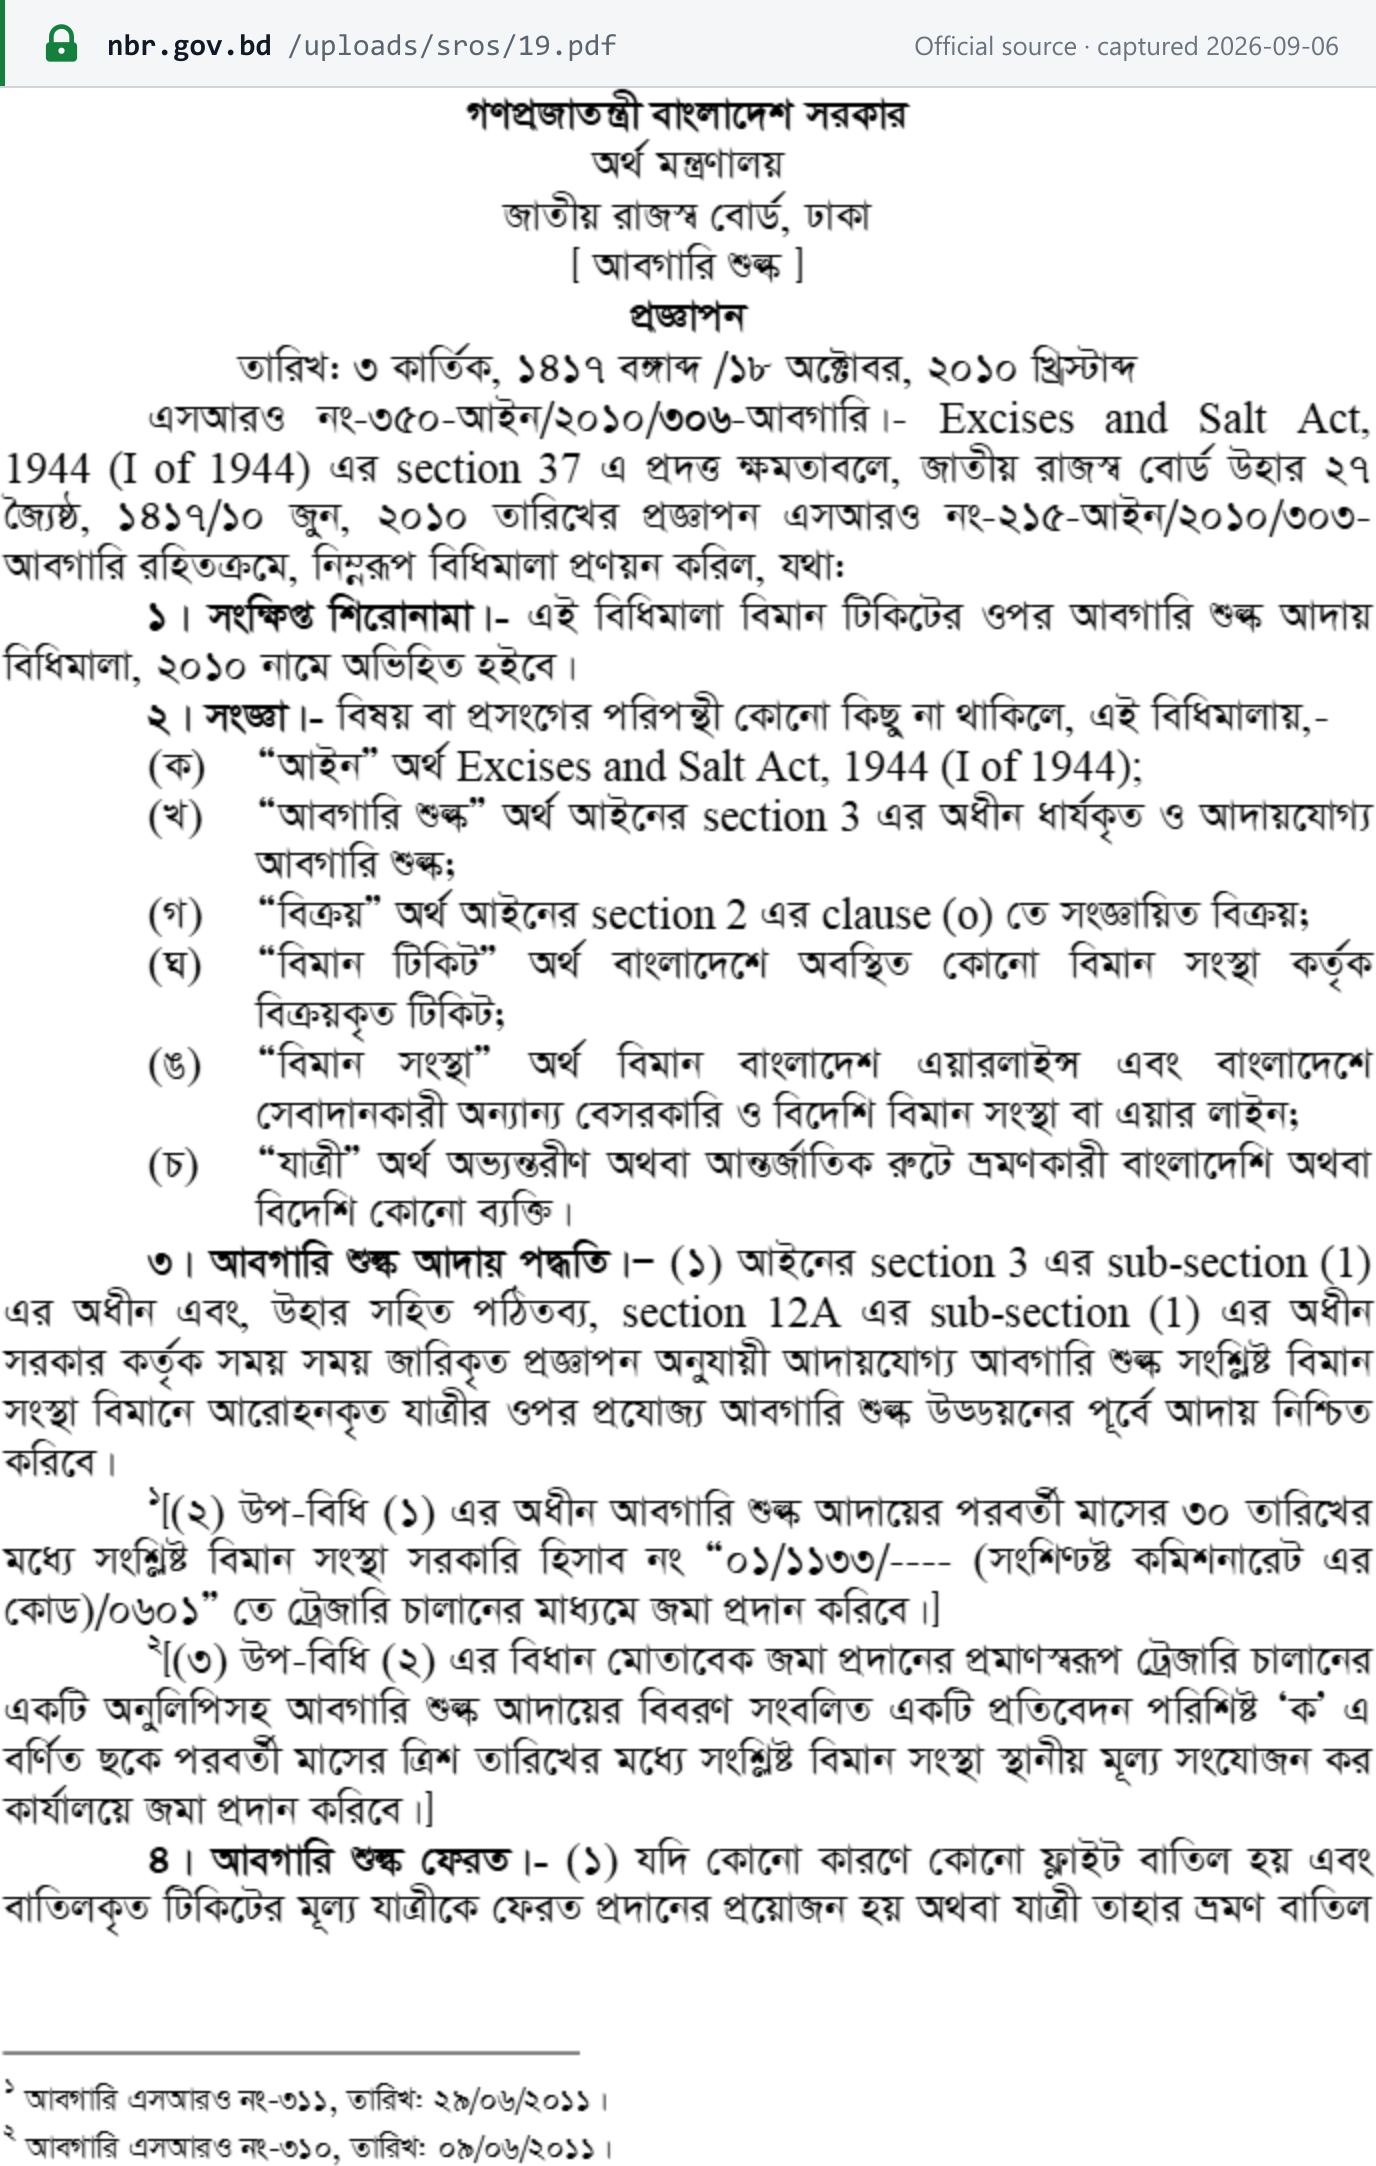
বিমান টিকিটের উপর আবগারি শুল্ক আদায় বিধিমালা, ২০১০ - SRO 350-Ain/2010/306-Excise, rule 3, as amended National Board of Revenue
See the source text
“পরবর্তী মাসের ৩০ তারিখের মধ্যে”
Screenshot of National Board of Revenue showing the Excise duty on air tickets - monthly deposit and report deadline Open full size Captured from National Board of Revenue on 2026-09-07

VAT registration application (Mushak-2.1 / Mushak-2.2)

Value Added Tax (VAT) · One-off · registration

within 15 days of the day the obligation to register arose - the first day of the month in which the 12-month turnover test is crossed Verified 2026-09-07
Who files
Anyone whose turnover crosses BDT 5,000,000 in any 12 months, and anyone caught by the activity tests that require registration regardless of turnover
Notes
Registration is due within 15 days of the day the obligation arises, and liability starts on the first day of a month, so in practice the application is due by the 15th of that month. Turnover is not the only trigger, and this is the part filers get wrong: supplying or importing goods or services subject to supplementary duty, supplying under a tender, contract or work order, running an import-export business, opening a branch, liaison or project office of a foreign company, or being appointed a VAT agent all require registration whatever the turnover. Residents apply on Mushak-2.1 and non-residents on Mushak-2.2.
Source
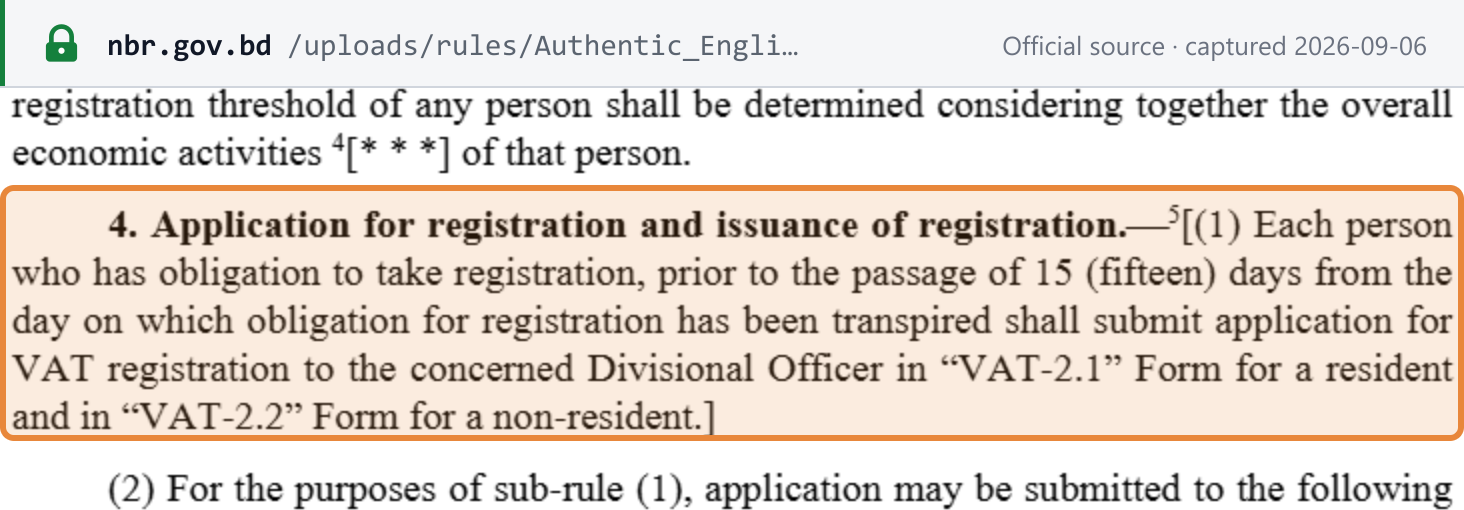
Value Added Tax and Supplementary Duty Rules, 2016 - rule 4(1), authentic English text, PDF page 4 National Board of Revenue
See the source text
“Each person who has obligation to take registration, prior to the passage of 15 (fifteen) days from the day on which obligation for registration has been transpired shall submit application for VAT registration to the concerned Divisional Officer in "VAT-2.1" Form for a resident and in "VAT-2.2" Form for a non-resident.”
Screenshot of National Board of Revenue showing the VAT registration application (Mushak-2.1 / Mushak-2.2) deadline Open full size Captured from National Board of Revenue on 2026-09-07

Turnover tax enlistment application (eVAT)

Turnover Tax · One-off · registration

within 30 days of crossing the turnover-tax enlistment threshold in any 12-month period without crossing the VAT registration threshold Verified 2026-09-07
Who files
Anyone whose turnover crosses BDT 3,000,000 in any 12 months without crossing the BDT 5,000,000 VAT registration threshold
Notes
Cross BDT 3,000,000 of turnover in any 12 months without crossing BDT 5,000,000 and you must apply to be enlisted as a turnover-tax payer within 30 days, through the eVAT system. Note the asymmetry with VAT registration, which allows only 15 - the two are commonly quoted as if they were the same deadline. Both the 30-day rule and the eVAT channel, with its automatic approval, took effect on 1 July 2026.
Source
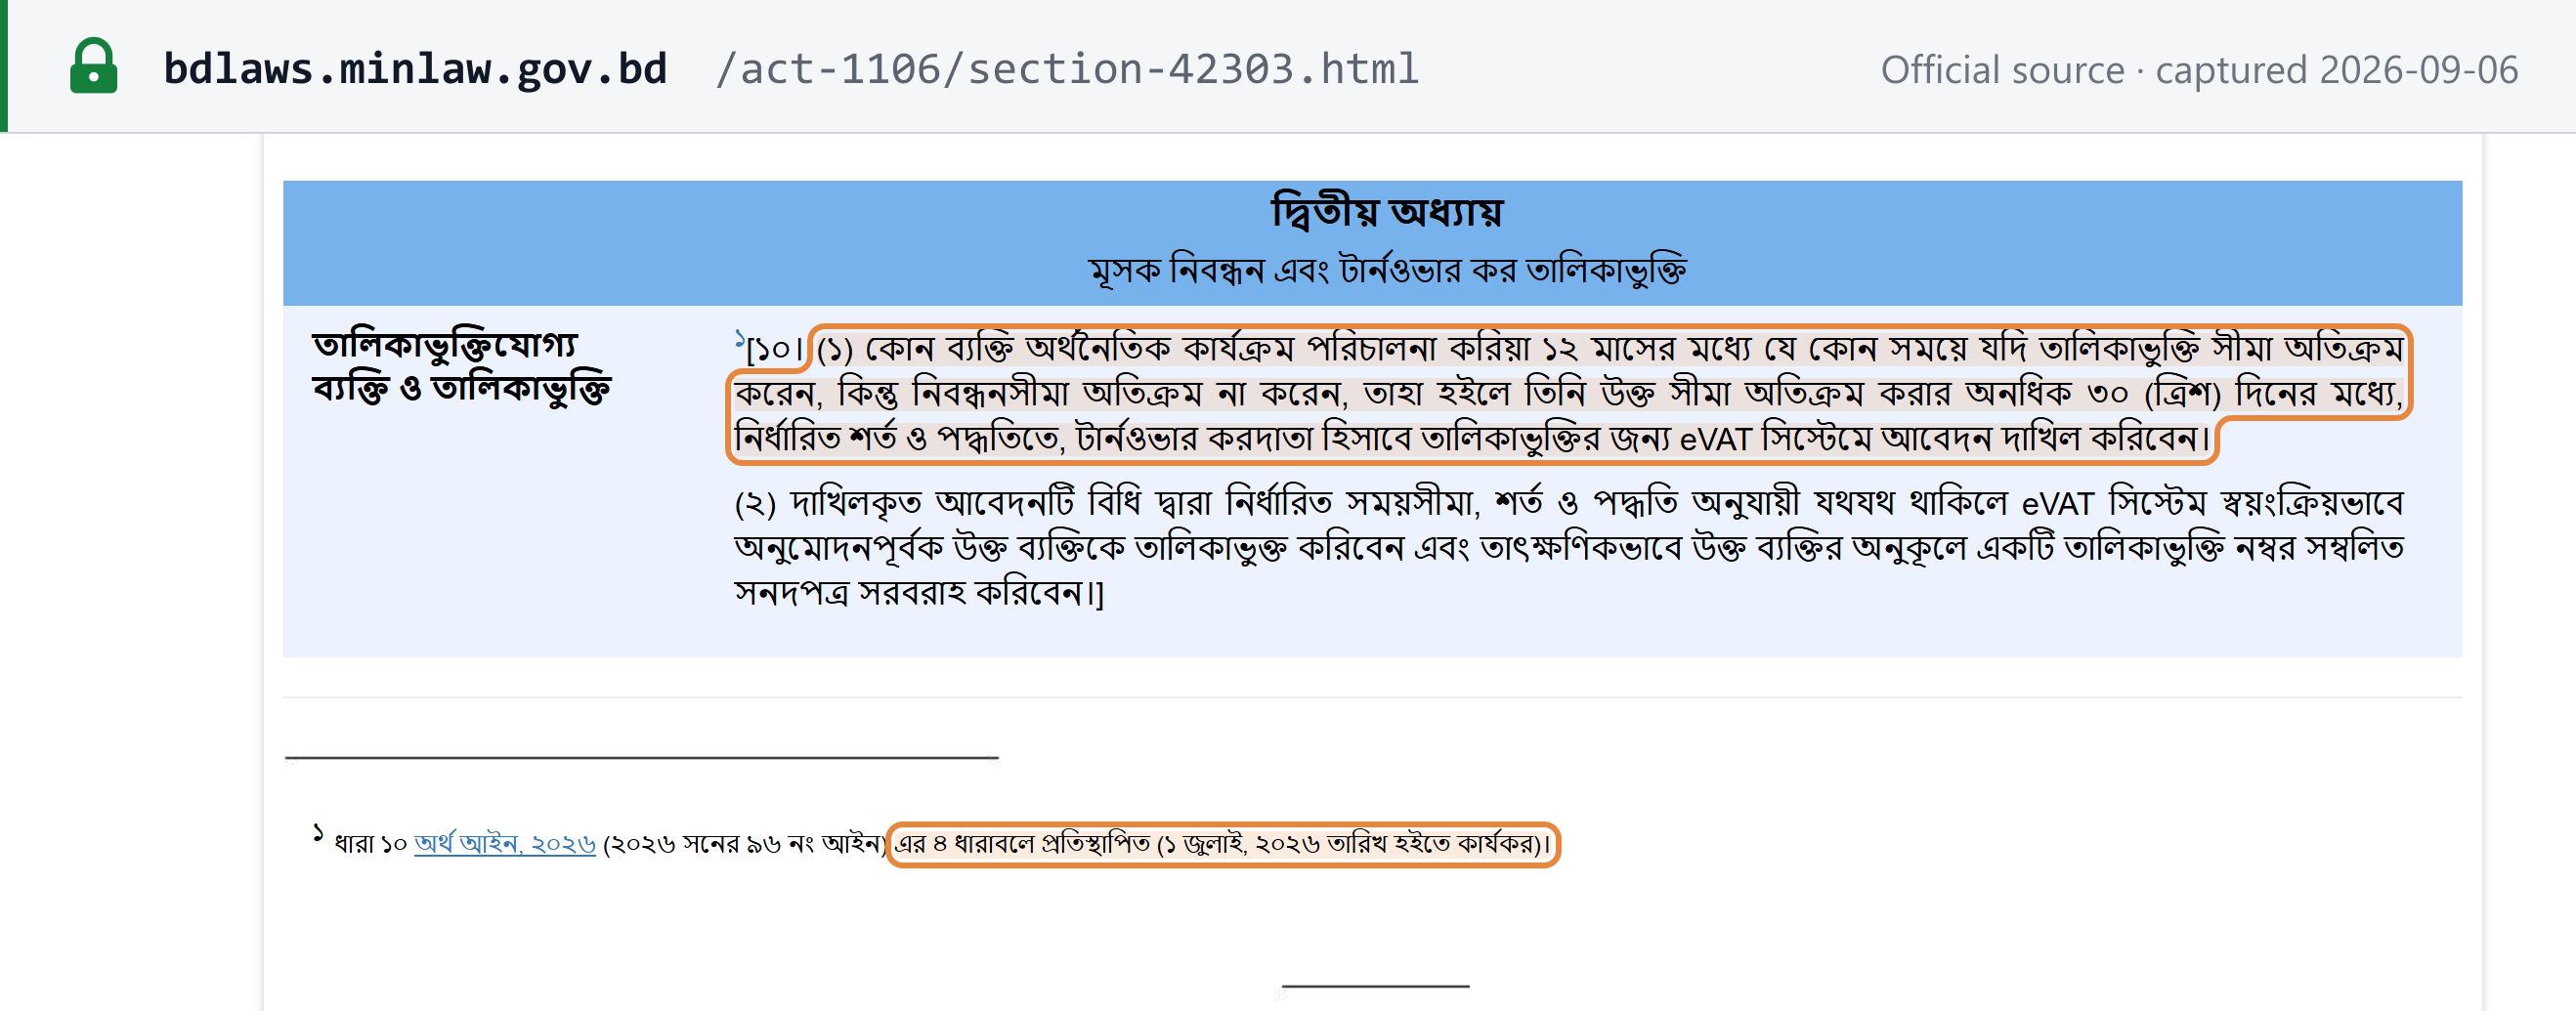
মূল্য সংযোজন কর ও সম্পূরক শুল্ক আইন, ২০১২ — ধারা ১০ (তালিকাভুক্তি) Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs
See the source text
“১০। (১) কোন ব্যক্তি অর্থনৈতিক কার্যক্রম পরিচালনা করিয়া ১২ মাসের মধ্যে যে কোন সময়ে যদি তালিকাভুক্তি সীমা অতিক্রম করেন, কিন্তু নিবন্ধনসীমা অতিক্রম না করেন, তাহা হইলে তিনি উক্ত সীমা অতিক্রম করার অনধিক ৩০ (ত্রিশ) দিনের মধ্যে, নির্ধারিত শর্ত ও পদ্ধতিতে, টার্নওভার করদাতা হিসাবে তালিকাভুক্তির জন্য eVAT সিস্টেমে আবেদন দাখিল করিবেন।”
Screenshot of Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs showing the Turnover tax enlistment application (eVAT) deadline Open full size Captured from Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs on 2026-09-07

Bangladesh files VAT quarterly, not monthly - the change took effect on 1 July 2026 and most published calendars have not caught up. There is no annual VAT reconciliation of the Indian or German kind; the annual obligation here is a limited company's audited financial statements. Supplementary duty needs no return of its own because the Act requires its particulars inside the VAT return, and customs duty is charged per consignment rather than on a cycle. The dates shown are the statutory ones, and the Board regularly extends them by public order when a deadline falls near a long holiday, so they are the earliest a return is due and never the latest. Public holidays are not modelled: the largest - the two Eids, Ashura, Eid-e-Miladunnabi, Shab-e-Barat and Shab-e-Qadr - are lunar and fixed by moon sighting only days ahead, so no multi-year list can exist, and that omission can only ever show a date on or before the true deadline. The weekend here is Friday and Saturday, and Sunday is an ordinary working day. Excise duty on air tickets is covered; the excise on bank and financial-institution account balances is not, because it is an annual rate table keyed to the balance with no filing cycle of its own. Still genuinely uncovered rather than absent: the 1 per cent health development surcharge on tobacco under the Development Surcharge and Levy (Imposition and Collection) Act 2015, and the deregistration and cancellation timetable in rules 7 and 8, where rule 7 carries the 15-day steps around the final return. Direct tax, payroll and company-registry deadlines are out of scope for this calendar.

“1[৬৪। (১) প্রত্যেক নিবন্ধিত বা তালিকাভুক্ত বা নিবন্ধনযোগ্য বা তালিকাভুক্তিযোগ্য ব্যক্তিকে নির্ধারিত পদ্ধতিতে প্রতি তিন কর মেয়াদ সমাপ্তির অনধিক ১৫ (পনের) দিনের মধ্যে দাখিলপত্র পেশ করিতে হইবে, তবে ১৫ (পনের) তম দিবসে সরকারি ছুটি থাকিলে তৎপরবর্তী কার্যদিবসে দাখিলপত্র পেশ করিতে হইবে:”
Screenshot of the official source stating the rule that governs Bangladesh's deadlines
মূল্য সংযোজন কর ও সম্পূরক শুল্ক আইন, ২০১২ — ধারা ৬৪(১) শর্তাংশ — Legislative and Parliamentary Affairs Division, Ministry of Law, Justice and Parliamentary Affairs, captured 2026-09-07

What this calendar does not list

  • Not applicable Recapitulative listing — Bangladesh has no recapitulative or periodic listing return. The nearest thing is the Mushak-6.10 transmission of details of invoices above BDT 200,000, both issued and received, to the VAT Computer System - but rule 42(1) expressly allows it "before or after submission of return of the tax period", so it fixes no date a calendar could show, and rule 42(7) waives it entirely where the same data already reaches the system through enlisted software, a POS or an ECR. The purchase and sales books (Mushak-6.1, 6.2 and 6.2.1) are preservation duties, not filings.
  • Not applicable E-invoicing / e-reporting cycle — No continuous-transaction-control mandate fixes a submission cycle. Invoicing is governed by section 51 and rule 40(1)(c), which set when an invoice must be ISSUED, not when anything is submitted. NBR's Electronic Fiscal Device and Sales Data Controller programme fiscalises sales at the till and relays them, and the only Rules provision touching it is rule 42(5) - a power for the Board to pull data from a POS, ECR or other sale machine from a date it determines, with no taxpayer-side deadline. The terms "Electronic Fiscal", "EFD", "Sales Data Controller" and "SDC" appear nowhere in the consolidated Rules.

About this calendar

Which Bangladesh tax deadlines does this calendar cover?

10 recurring indirect-tax obligations — Turnover Tax, Value Added Tax (VAT), VAT deduction at source (VDS) and আবগারি শুল্ক (excise duty) on air tickets returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-09-07). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.