Croatia compliance calendar

15 recurring Porez na dodanu vrijednost (VAT) and Fiskalizacija eRačuna (e-reporting) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Croatia rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Report / listing Return filing Payment Law change takes effect

Dates already include the weekend and public-holiday shift where Croatia applies one — 4 of 15 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Prijava PDV-a (Obrazac PDV) — monthly

Porez na dodanu vrijednost (VAT) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-07
Who files
VAT-registered taxpayers on the default monthly period — anyone above EUR 110,000 of prior-year supplies including VAT, every business making intra-EU transactions, and every non-established registrant
Notes
Due by the last day of the month after the month ends — no longer the 20th. The VAT Act amendment in Narodne novine 151/2025 moved it with effect from the January 2026 return, which was due at the end of February. File every month, even with nothing to declare. When the last day is a Saturday, Sunday or public holiday the return is due the next working day: the September 2026 return on Monday 2 November, and September 2027 on Tuesday 2 November, because 1 November is All Saints' Day. The separate book of received invoices (U-RA) that used to go in with the return was abolished from 2026.
Source
Zakon o izmjenama i dopunama Zakona o porezu na dodanu vrijednost (NN 151/2025) — čl. 4. (čl. 85. st. 6. Zakona) Narodne novine
See the source text
“U članku 85. stavku 6. riječi: »do 20-og dana u mjesecu« zamjenjuju se riječima: »do zadnjeg dana u tekućem mjesecu«.”
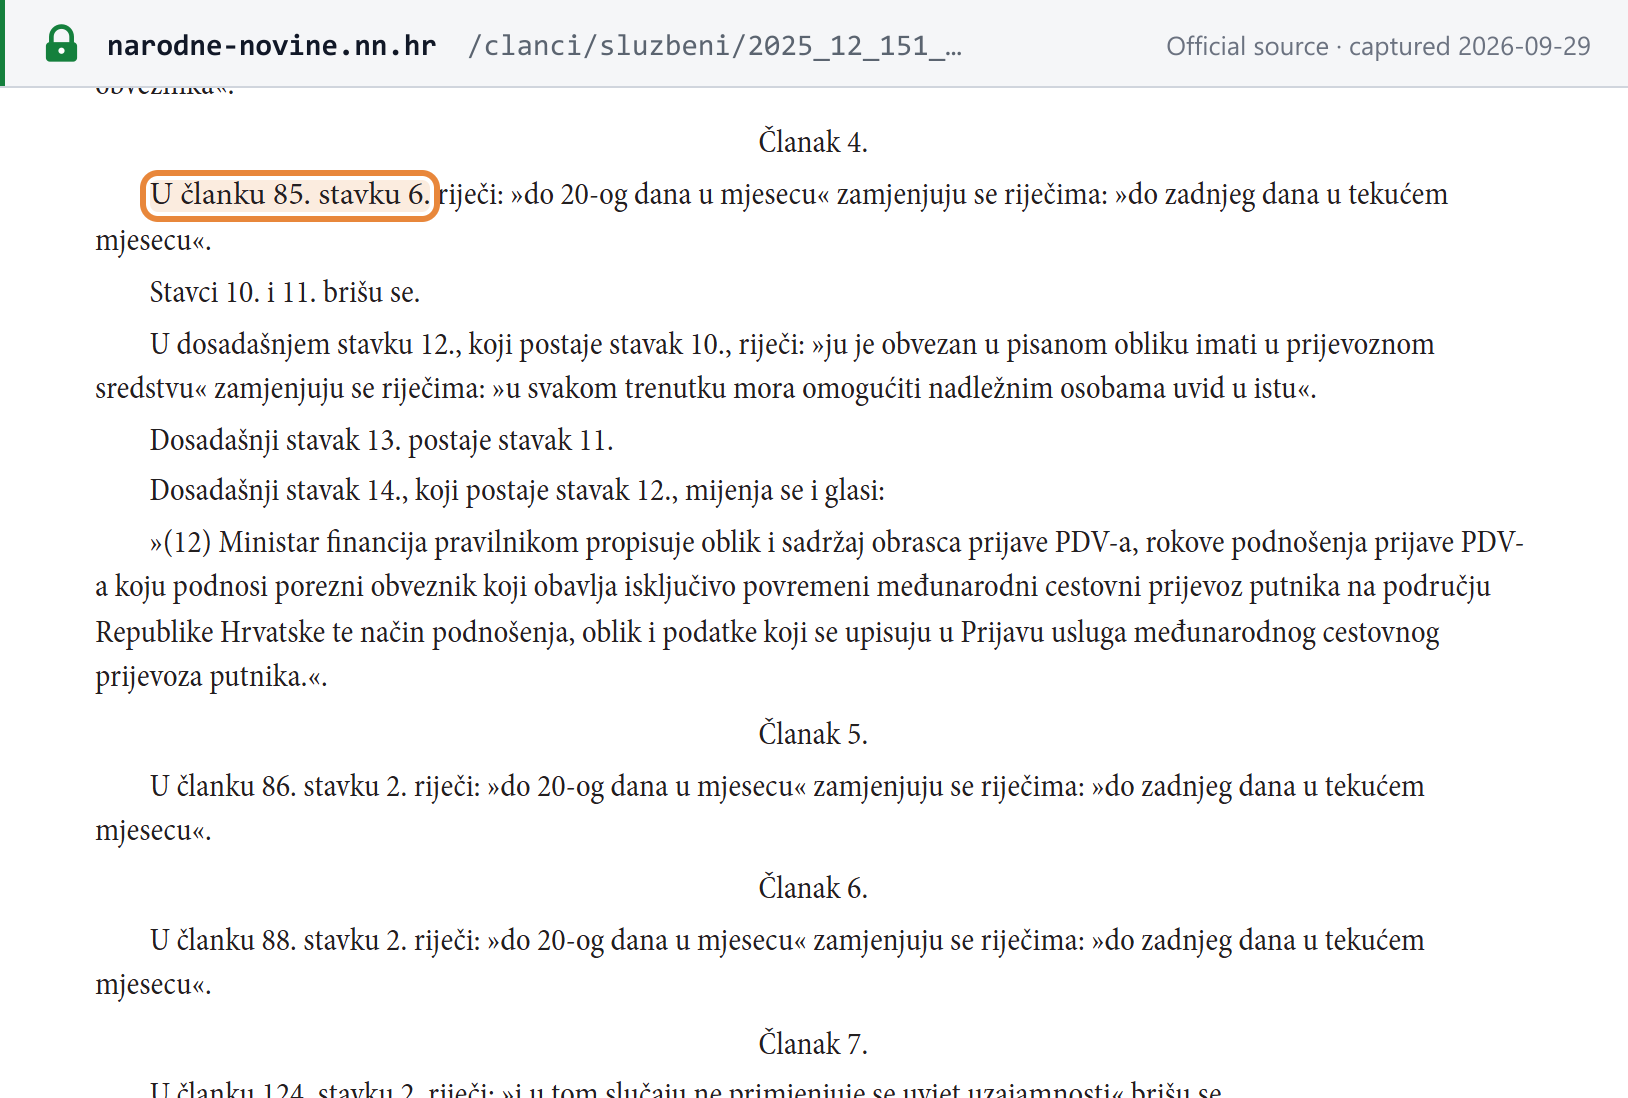
Screenshot of Narodne novine showing the Prijava PDV-a (Obrazac PDV) — monthly deadline Open full size Captured from Narodne novine on 2026-10-07
Prijava PDV-a (Obrazac PDV) — quarterly

Porez na dodanu vrijednost (VAT) · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-07
Who files
Established taxpayers whose supplies including VAT were below EUR 110,000 in the previous calendar year, unless they make intra-EU transactions; the choice between monthly and quarterly is made by 15 January
Notes
Smaller businesses file four returns a year, by 30 April, 31 July, 31 October and 31 January. The test is supplies of under EUR 110,000 in the previous year, counted including VAT, and it is closed to anyone trading goods or services with other EU countries, who stays monthly. You can move between monthly and quarterly filing by 15 January for the whole year. A weekend or holiday deadline slips to the next working day — the second quarter of 2027 is due Monday 2 August. Nil returns are still required. The first quarter of 2026 was the first one due at the end of the month rather than on the 20th.
Source
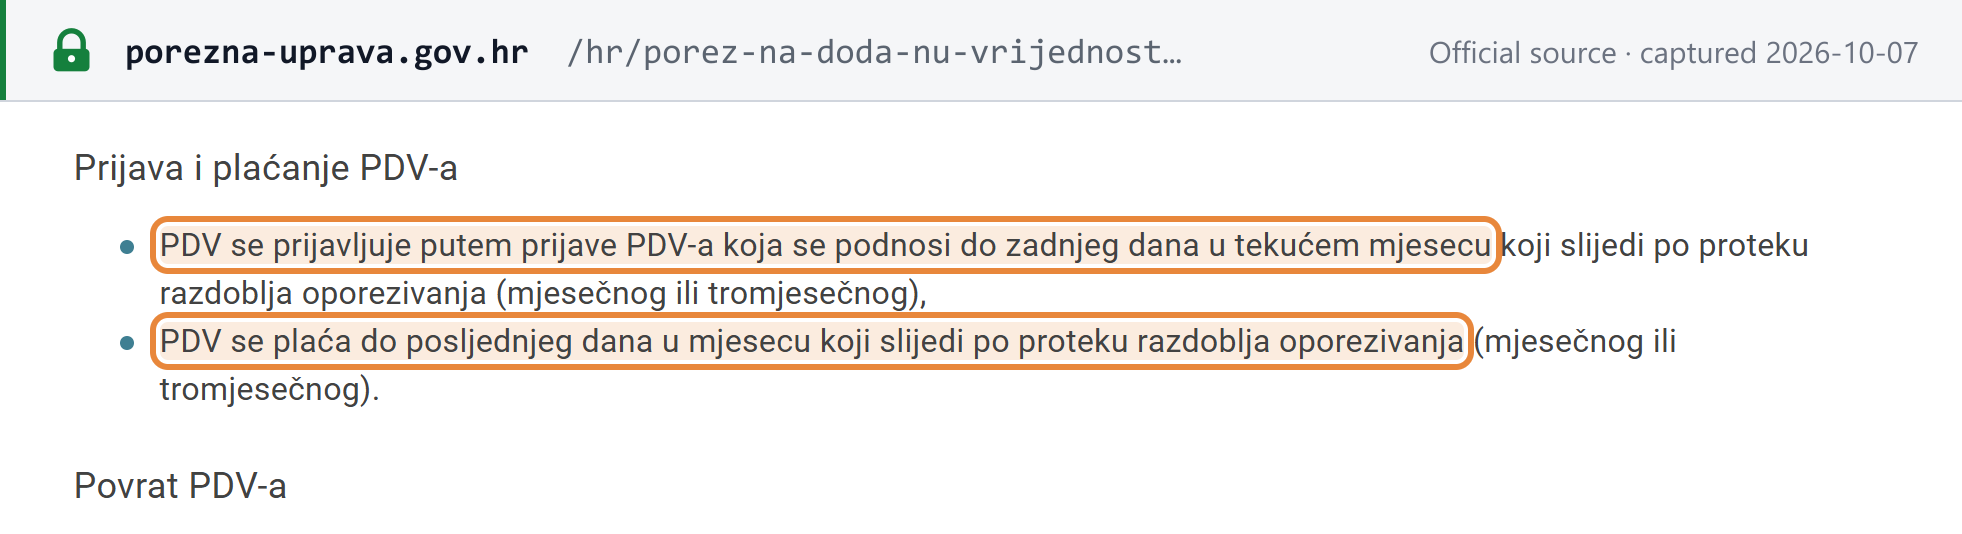
Porezna uprava — Porez na dodanu vrijednost: Prijava i plaćanje PDV-a Porezna uprava
See the source text
“PDV se prijavljuje putem prijave PDV-a koja se podnosi do zadnjeg dana u tekućem mjesecu koji slijedi po proteku razdoblja oporezivanja (mjesečnog ili tromjesečnog)”
Screenshot of Porezna uprava showing the Prijava PDV-a (Obrazac PDV) — quarterly deadline Open full size Captured from Porezna uprava on 2026-10-07

Plaćanje PDV-a — monthly payers

Porez na dodanu vrijednost (VAT) · Monthly · payment

last day of the month after the month ends Verified 2026-10-07
Who files
Taxpayers on the monthly VAT period
Notes
The VAT for each month is payable by the last day of the following month — the same day the return is now due. For September 2026 that is Saturday 31 October, and it stays there. Tax counts as paid on the day the bank holding the tax account receives it, and interbank payments do not settle on non-working days — before Good Friday 2026 Porezna uprava told payers to send them the day before — so pay by the last working day before a weekend deadline. VAT you account for under the reverse charge is treated as paid once it is shown in the return.
Source
Porezna uprava — Porez na dodanu vrijednost: Prijava i plaćanje PDV-a Porezna uprava
See the source text
“PDV se plaća do posljednjeg dana u mjesecu koji slijedi po proteku razdoblja oporezivanja (mjesečnog ili tromjesečnog).”
Screenshot of Porezna uprava showing the Plaćanje PDV-a — monthly payers deadline Open full size Captured from Porezna uprava on 2026-10-07

Plaćanje PDV-a — quarterly payers

Porez na dodanu vrijednost (VAT) · Quarterly · payment

last day of the month after the quarter ends Verified 2026-10-07
Who files
Taxpayers on the quarterly VAT period
Notes
Quarterly filers pay the quarter's VAT by the end of the month after it: 30 April, 31 July, 31 October and 31 January. Sunday 31 January 2027 stays the payment date for the last quarter of 2026, even though the return for that quarter can go in on Monday 1 February — so the money should leave your bank by Friday 29 January.
Source
Porezna uprava — Porez na dodanu vrijednost: Prijava i plaćanje PDV-a Porezna uprava
See the source text
“PDV se plaća do posljednjeg dana u mjesecu koji slijedi po proteku razdoblja oporezivanja (mjesečnog ili tromjesečnog).”
Screenshot of Porezna uprava showing the Plaćanje PDV-a — quarterly payers deadline Open full size Captured from Porezna uprava on 2026-10-07

Obrazac PDV-S (Prijava za stjecanje dobara i primljene usluge iz drugih država članica EU)

Porez na dodanu vrijednost (VAT) · Monthly · report / listing

last day of the month after the month ends Verified 2026-10-07
Who files
VAT-registered persons that acquired goods or received services from suppliers in other EU Member States in the month — quarterly VAT filers included
Notes
The PDV-S lists what you bought from suppliers elsewhere in the EU, supplier by supplier. It runs on calendar months for everybody, so a business filing its VAT return quarterly still files a PDV-S for each month in which it made such purchases; a month with none needs no form. It is due by the last day of the following month — the 20th until the end of 2025 — and a deadline on a non-working day moves to the next working day, so January 2027 is due Monday 1 March 2027.
Source
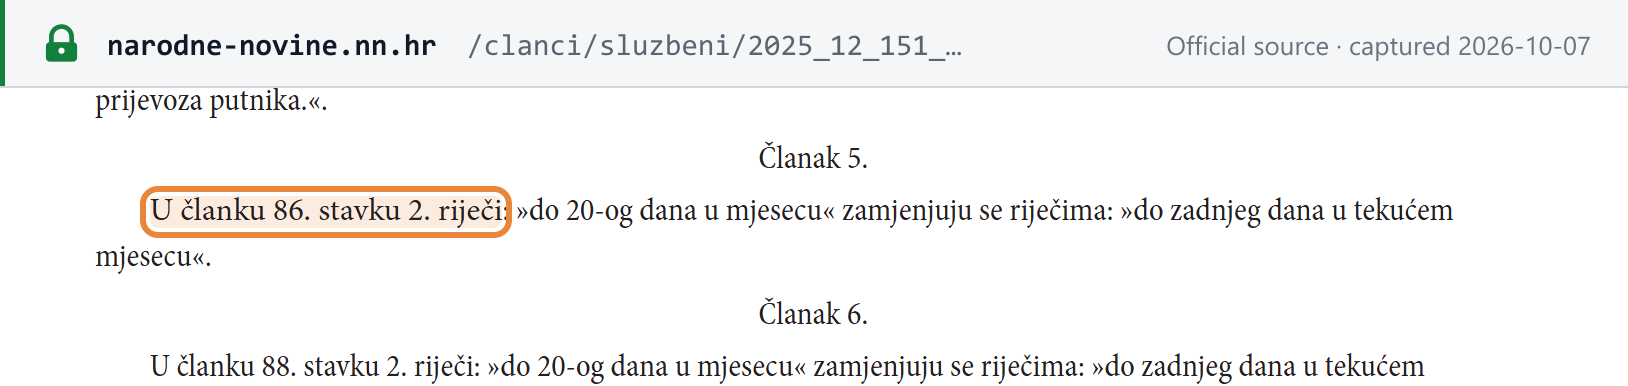
Zakon o izmjenama i dopunama Zakona o porezu na dodanu vrijednost (NN 151/2025) — čl. 5. (čl. 86. st. 2. Zakona) Narodne novine
See the source text
“U članku 86. stavku 2. riječi: »do 20-og dana u mjesecu« zamjenjuju se riječima: »do zadnjeg dana u tekućem mjesecu«.”
Screenshot of Narodne novine showing the Obrazac PDV-S (Prijava za stjecanje dobara i primljene usluge iz drugih država članica EU) deadline Open full size Captured from Narodne novine on 2026-10-07
Zbirna prijava (Obrazac ZP) — EC Sales List

Porez na dodanu vrijednost (VAT) · Monthly · report / listing

last day of the month after the month ends Verified 2026-10-07
Who files
VAT-registered persons that made intra-EU supplies of goods (including transfers and triangular supplies) or general-rule B2B services to other Member States in the month
Notes
Monthly for every filer — Croatia has no quarterly EC Sales List — and due by the last day of the following month, shifted to the next working day where needed (the July 2027 list is due Tuesday 31 August, the June list Monday 2 August). Skip months with no EU supplies. A domestic business acting for a foreign importer under customs procedure 42 or 63 also files a monthly PZ 42 i 63 report by the same date. The quarterly domestic reverse-charge listing (PPO) was abolished from 2026; the last one covered the fourth quarter of 2025.
Source
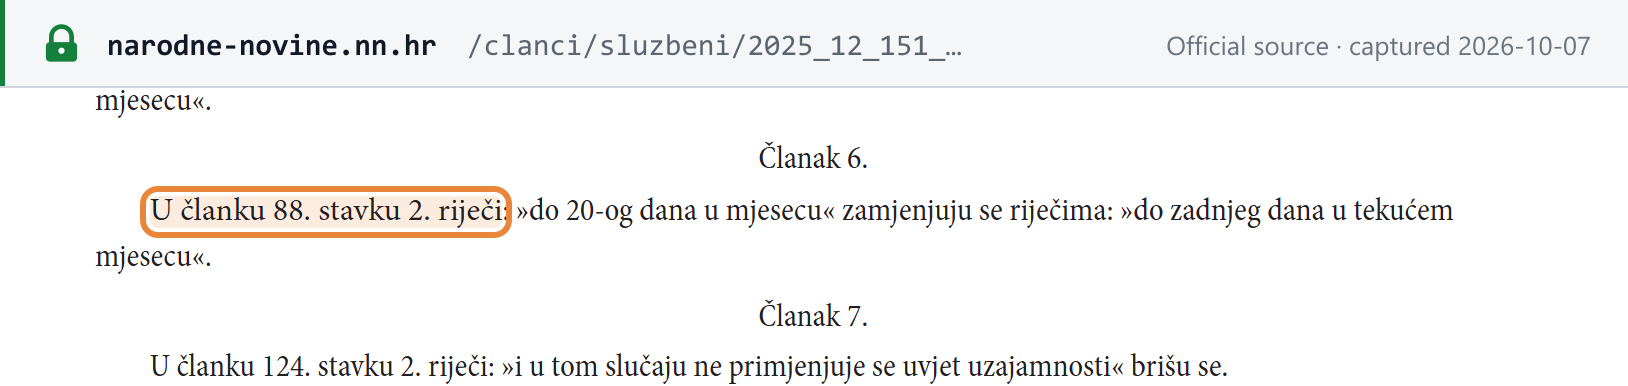
Zakon o izmjenama i dopunama Zakona o porezu na dodanu vrijednost (NN 151/2025) — čl. 6. (čl. 88. st. 2. Zakona) Narodne novine
See the source text
“U članku 88. stavku 2. riječi: »do 20-og dana u mjesecu« zamjenjuju se riječima: »do zadnjeg dana u tekućem mjesecu«.”
Screenshot of Narodne novine showing the Zbirna prijava (Obrazac ZP) — EC Sales List deadline Open full size Captured from Narodne novine on 2026-10-07
Obrazac e-trgovina — annual overview of EU distance sales under the EUR 10,000 threshold

Porez na dodanu vrijednost (VAT) · Annually · report / listing

31st January each year Verified 2026-10-07
Who files
Croatia-established taxpayers whose distance sales of goods and telecommunications, broadcasting and electronic services to consumers in other Member States stayed under EUR 10,000 in the year
Notes
If you sell to consumers in other EU countries but stay under the EUR 10,000 threshold, you file this overview for the previous year by the end of January — moved from 20 January by the Rulebook amendment in Narodne novine 11/2026, so the overview for 2026 is the first due at month-end, on Sunday 31 January 2027. Porezna uprava's own OSS page still shows the old 20 January date. Cross the threshold during the year and the form is due within 8 days of the sale that took you over it.
Source
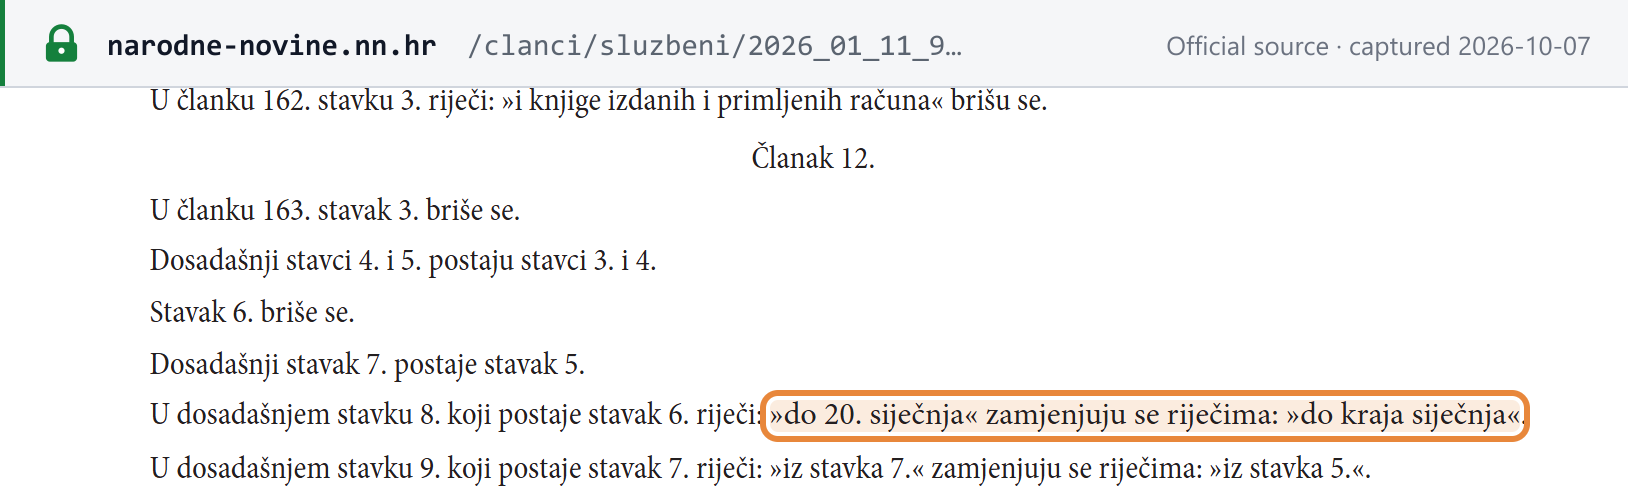
Pravilnik o izmjenama i dopunama Pravilnika o porezu na dodanu vrijednost (NN 11/2026) — čl. 12. (čl. 163. Pravilnika) Narodne novine
See the source text
“U dosadašnjem stavku 8. koji postaje stavak 6. riječi: »do 20. siječnja« zamjenjuju se riječima: »do kraja siječnja«.”
Screenshot of Narodne novine showing the Obrazac e-trgovina — annual overview of EU distance sales under the EUR 10,000 threshold deadline Open full size Captured from Narodne novine on 2026-10-07
Prijava PDV-a za posebni postupak oporezivanja — OSS Union scheme

Porez na dodanu vrijednost (VAT) · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-07
Who files
Taxpayers registered in Croatia for the OSS Union scheme (intra-EU distance sales of goods, deemed supplies by platforms, B2C services in Member States where they are not established)
Notes
One return a quarter covering your sales to consumers in every other EU country, due with the payment by the last day of the month after the quarter, and required even for a quarter with no such sales. Amounts are in euro. The European Commission states that this deadline does not move for a weekend or public holiday, so the third quarter of 2026 is due on Saturday 31 October.
Source
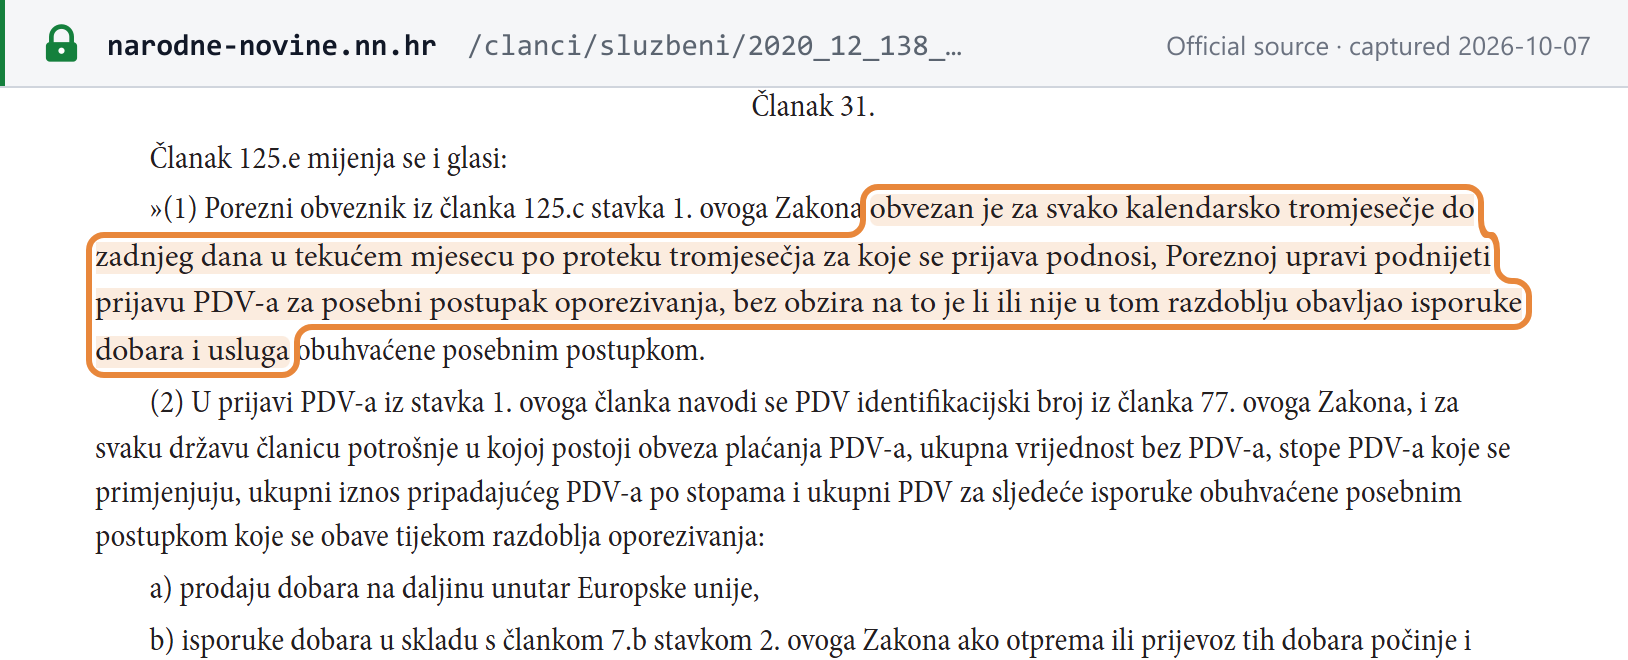
Zakon o izmjenama i dopunama Zakona o porezu na dodanu vrijednost (NN 138/2020) — čl. 31. (čl. 125.e st. 1. Zakona) Narodne novine
See the source text
“obvezan je za svako kalendarsko tromjesečje do zadnjeg dana u tekućem mjesecu po proteku tromjesečja za koje se prijava podnosi, Poreznoj upravi podnijeti prijavu PDV-a za posebni postupak oporezivanja, bez obzira na to je li ili nije u tom razdoblju obavljao isporuke dobara i usluga obuhvaćene posebnim postupkom.”
Screenshot of Narodne novine showing the Prijava PDV-a za posebni postupak oporezivanja — OSS Union scheme deadline Open full size Captured from Narodne novine on 2026-10-07
Prijava PDV-a za posebni postupak oporezivanja — OSS non-Union scheme

Porez na dodanu vrijednost (VAT) · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-07
Who files
Businesses established outside the EU that chose Croatia to declare B2C services supplied to consumers in EU Member States
Notes
Non-EU businesses selling services to EU consumers through Croatia follow the same quarterly timetable as the Union scheme: return and payment by the end of the month after the quarter, with a nil return when nothing was sold. A weekend does not extend it — Sunday 31 January 2027 is the deadline for the fourth quarter of 2026 — so plan to file on the Friday before.
Source
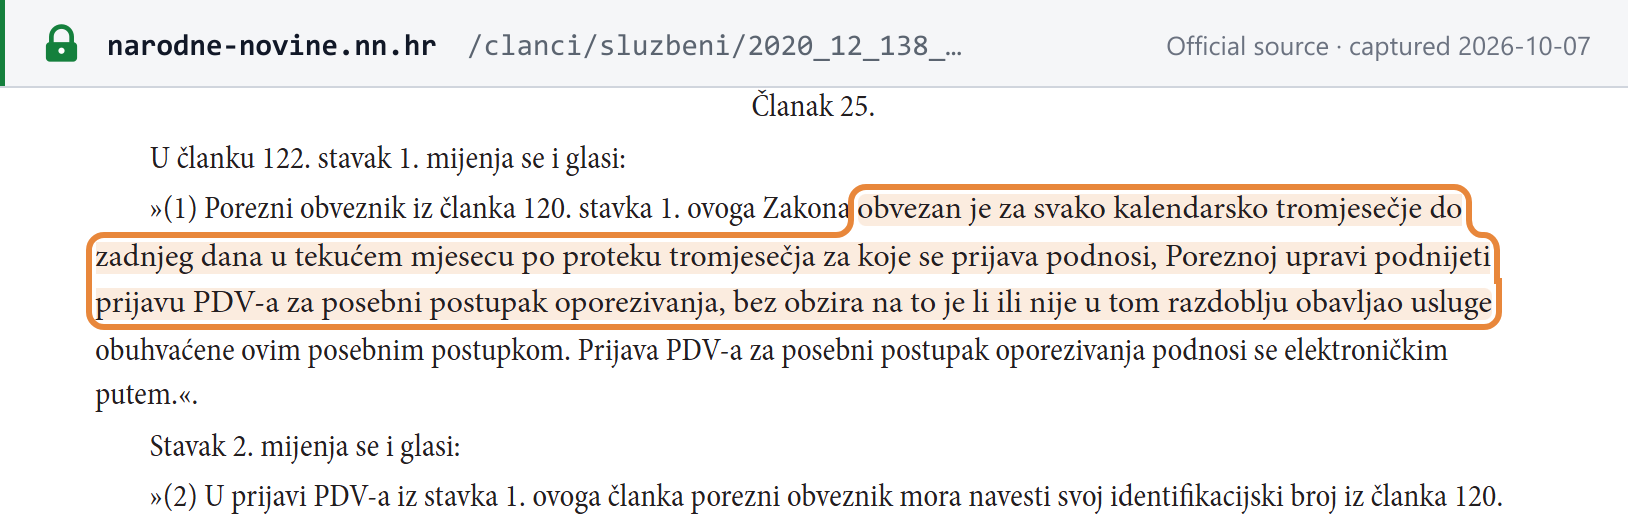
Zakon o izmjenama i dopunama Zakona o porezu na dodanu vrijednost (NN 138/2020) — čl. 25. (čl. 122. st. 1. Zakona) Narodne novine
See the source text
“obvezan je za svako kalendarsko tromjesečje do zadnjeg dana u tekućem mjesecu po proteku tromjesečja za koje se prijava podnosi, Poreznoj upravi podnijeti prijavu PDV-a za posebni postupak oporezivanja, bez obzira na to je li ili nije u tom razdoblju obavljao usluge obuhvaćene ovim posebnim postupkom.”
Screenshot of Narodne novine showing the Prijava PDV-a za posebni postupak oporezivanja — OSS non-Union scheme deadline Open full size Captured from Narodne novine on 2026-10-07
Prijava PDV-a za posebni postupak oporezivanja — IOSS (import scheme)

Porez na dodanu vrijednost (VAT) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-07
Who files
Sellers and intermediaries registered in Croatia for the import scheme (distance sales of goods imported from outside the EU in consignments of up to EUR 150)
Notes
The import scheme is monthly — a common slip for sellers who also use the quarterly One-Stop-Shop. Each month's return, quoting its reference number on the payment, is due with the tax by the last day of the following month, and a nil return is compulsory. Sunday 28 February 2027 is a live deadline, not Monday 1 March.
Source
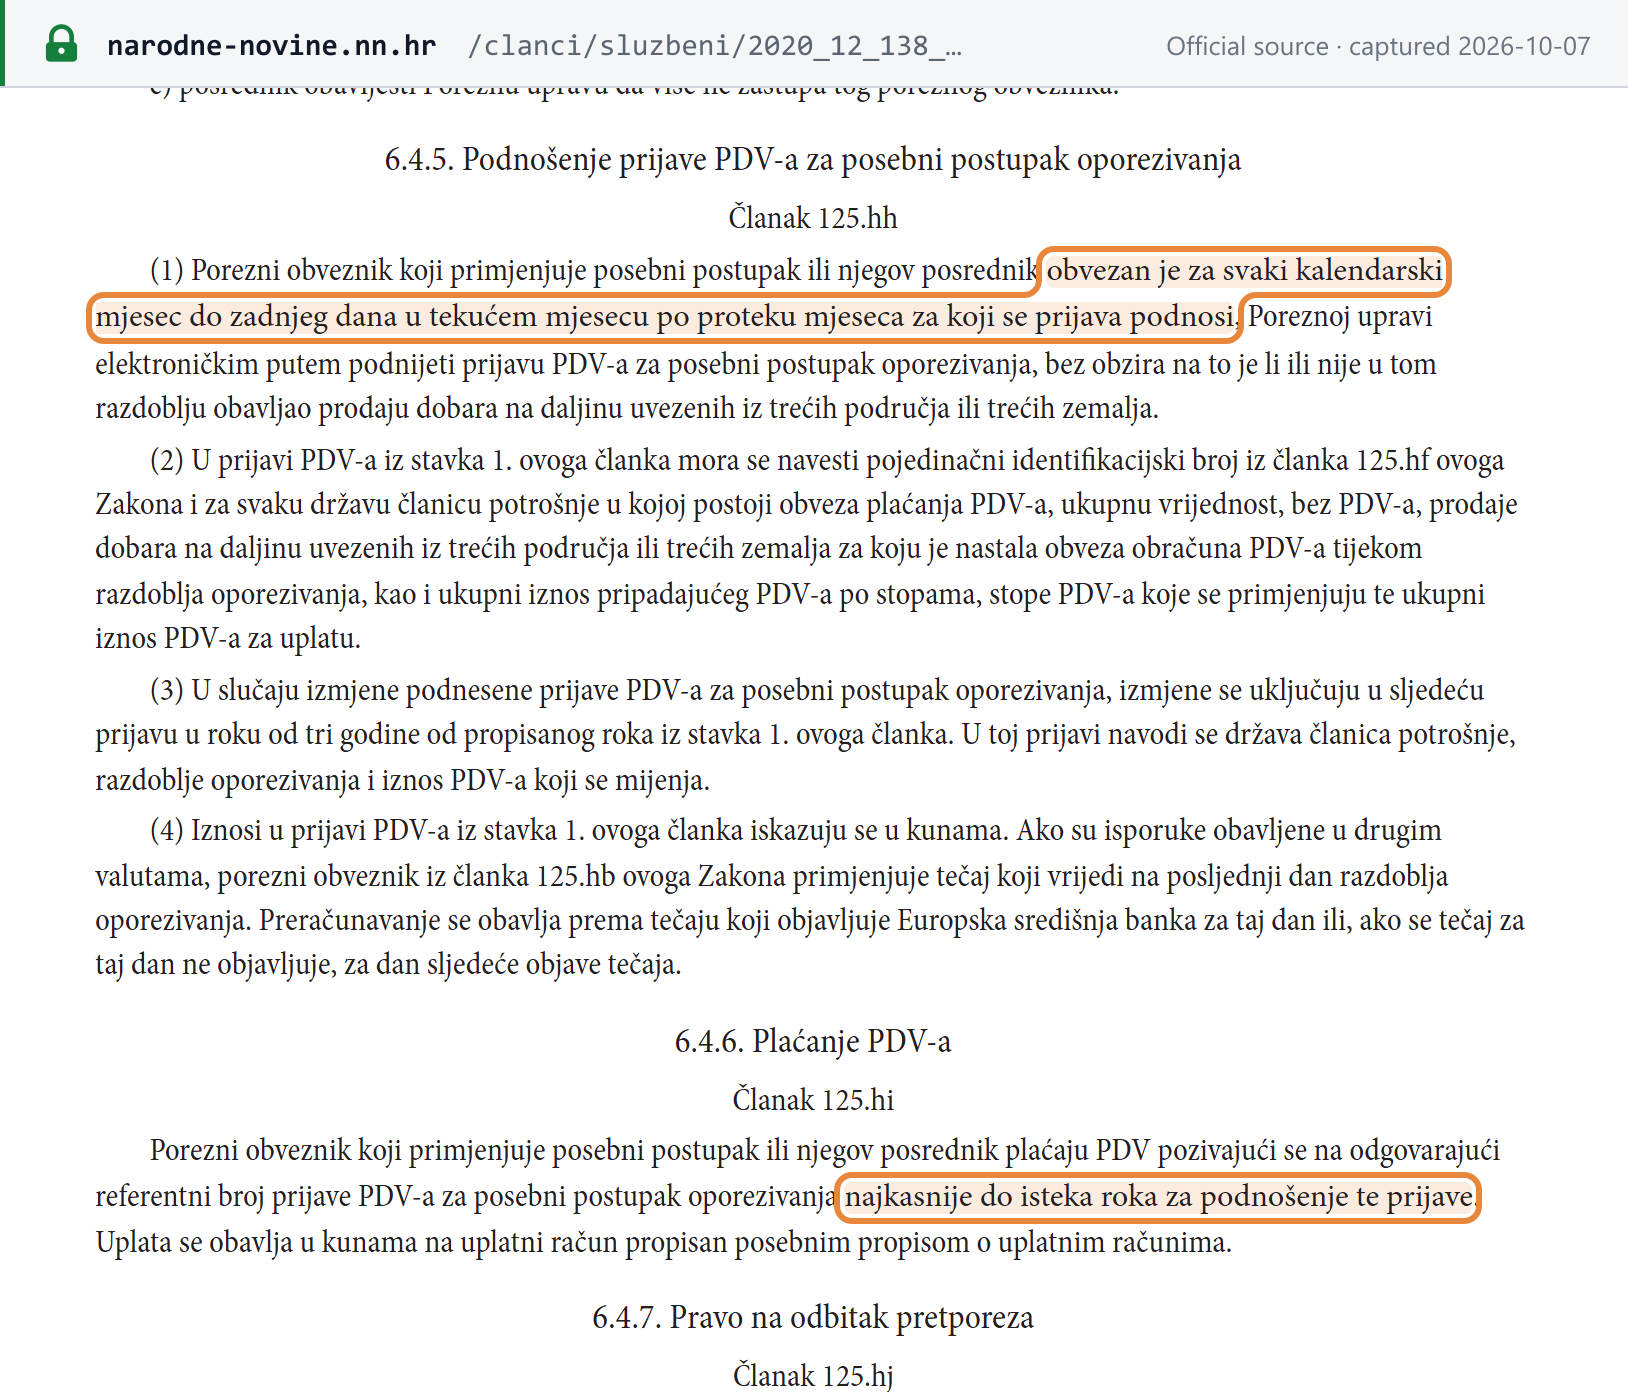
Zakon o izmjenama i dopunama Zakona o porezu na dodanu vrijednost (NN 138/2020) — čl. 125.hh i 125.hi Zakona Narodne novine
See the source text
“obvezan je za svaki kalendarski mjesec do zadnjeg dana u tekućem mjesecu po proteku mjeseca za koji se prijava podnosi, Poreznoj upravi elektroničkim putem podnijeti prijavu PDV-a za posebni postupak oporezivanja”
Screenshot of Narodne novine showing the Prijava PDV-a za posebni postupak oporezivanja — IOSS (import scheme) deadline Open full size Captured from Narodne novine on 2026-10-07
Mjesečna prijava — posebni postupak za prijavu i plaćanje PDV-a na uvoz (special arrangement for low-value imports)

Porez na dodanu vrijednost (VAT) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-07
Who files
Postal operators, couriers and customs agents presenting goods of up to EUR 150 to customs on the customer's behalf outside IOSS and collecting the import VAT from the customer
Notes
Carriers using the special arrangement file one monthly return of all the import VAT they collected, by the last day of the following month — Saturday 31 July 2027 included. The money itself follows the customs-duty payment deadline rather than this date, so it is not shown here.
Source
Zakon o izmjenama i dopunama Zakona o porezu na dodanu vrijednost (NN 138/2020) — čl. 125.ho Zakona Narodne novine
See the source text
“(2) Prijava iz stavka 1. ovoga članka podnosi se do zadnjeg dana u tekućem mjesecu za prethodni mjesec.”
Captured from Narodne novine on 2026-10-07
Tromjesečno izvješće — EU cross-border SME scheme quarterly report

Porez na dodanu vrijednost (VAT) · Quarterly · report / listing

30th of the month after the quarter ends — but the 31st in January Verified 2026-10-07
Who files
Croatia-established businesses using the SME VAT exemption in one or more other Member States
Notes
Using the EU-wide small-business exemption means filing one quarterly report with the Croatian tax office, covering your turnover in Croatia and in every other EU country — with a zero where there were no sales — within one month of the quarter's end. We show 30 April, 30 July, 30 October and 31 January; reporting by then is safe however the month is counted. If you pass the EUR 100,000 EU-wide limit you must tell the tax office within 15 working days.
Source
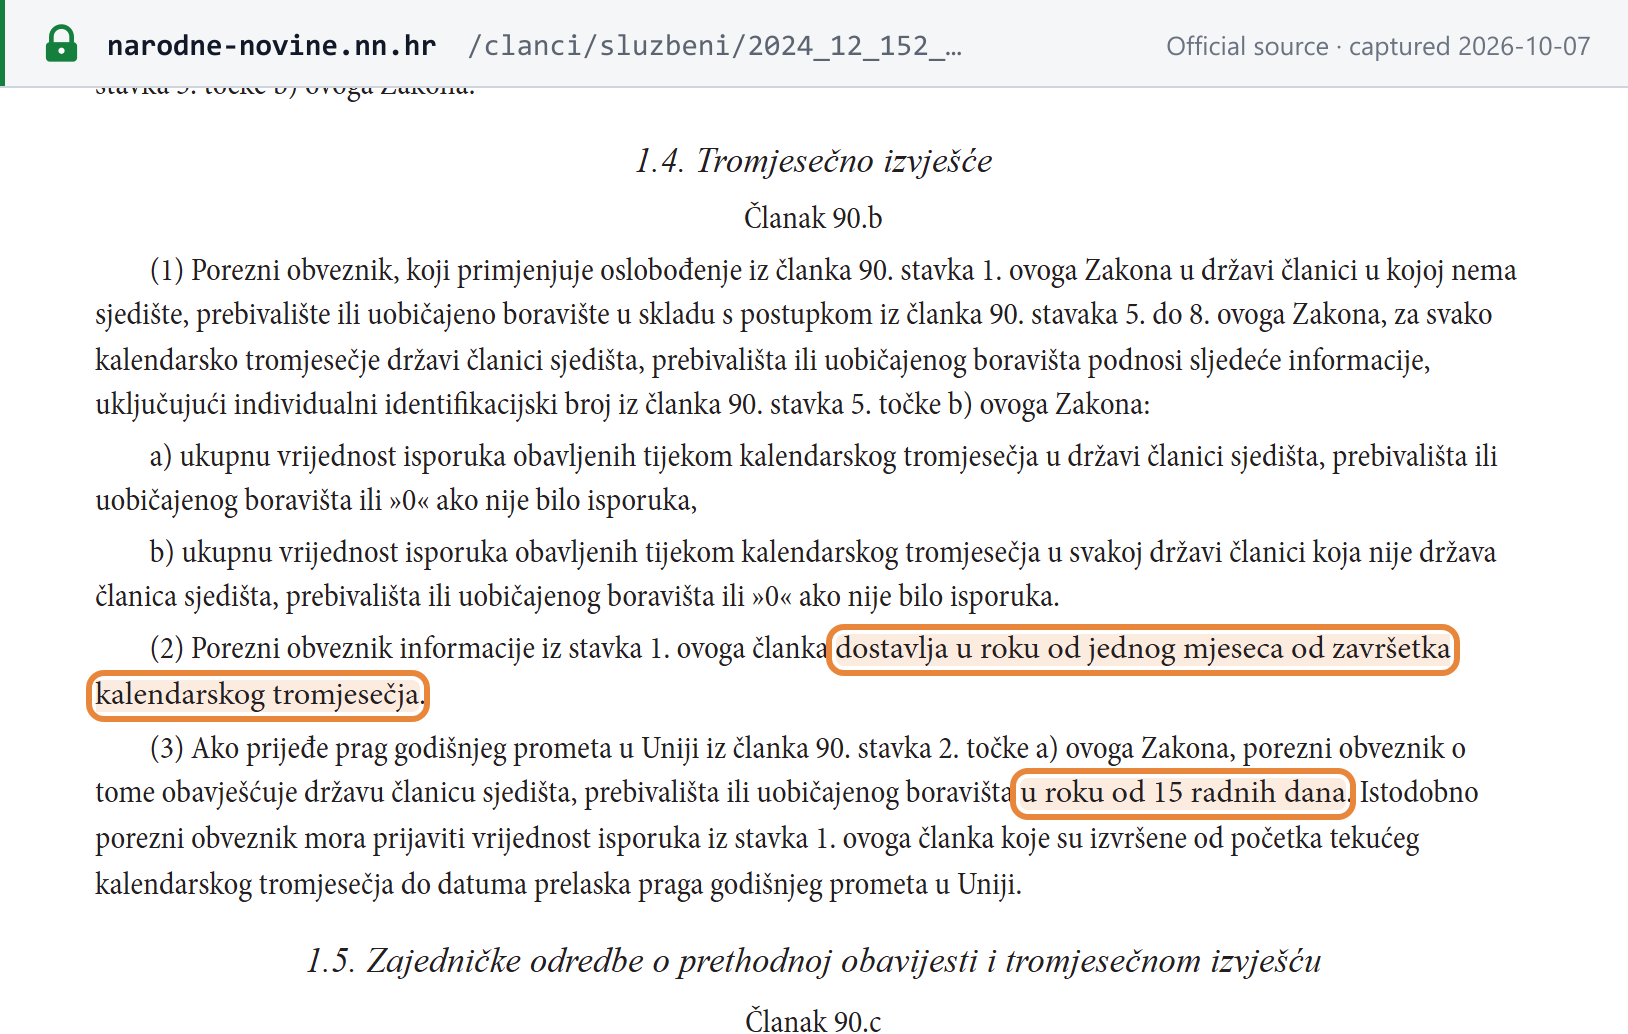
Zakon o izmjenama i dopunama Zakona o porezu na dodanu vrijednost (NN 152/2024) — čl. 90.b Zakona Narodne novine
See the source text
“(2) Porezni obveznik informacije iz stavka 1. ovoga članka dostavlja u roku od jednog mjeseca od završetka kalendarskog tromjesečja.”
Screenshot of Narodne novine showing the Tromjesečno izvješće — EU cross-border SME scheme quarterly report deadline Open full size Captured from Narodne novine on 2026-10-07
eIzvještavanje o naplati eRačuna — monthly eRačun payment report

Fiskalizacija eRačuna (e-reporting) · Monthly · report / listing

20th of the month after the month ends Verified 2026-10-07
Who files
Issuers of eRačun: in 2026, VAT-registered taxpayers established in Croatia; from the January 2027 period also non-VAT income- and profit-tax payers and non-VAT public bodies
Notes
If you issue eRačun, by the 20th of each month you report which of them were paid in the previous month — invoice date and number, amount, payment method and payment date — and the same goes for paper invoices you had to issue because the customer could not receive an eRačun. The duty began with January 2026, reported by 20 February 2026. From 2027 businesses outside the VAT system also start issuing eRačun, so they owe this report from the January 2027 period, due Saturday 20 February 2027.
Source
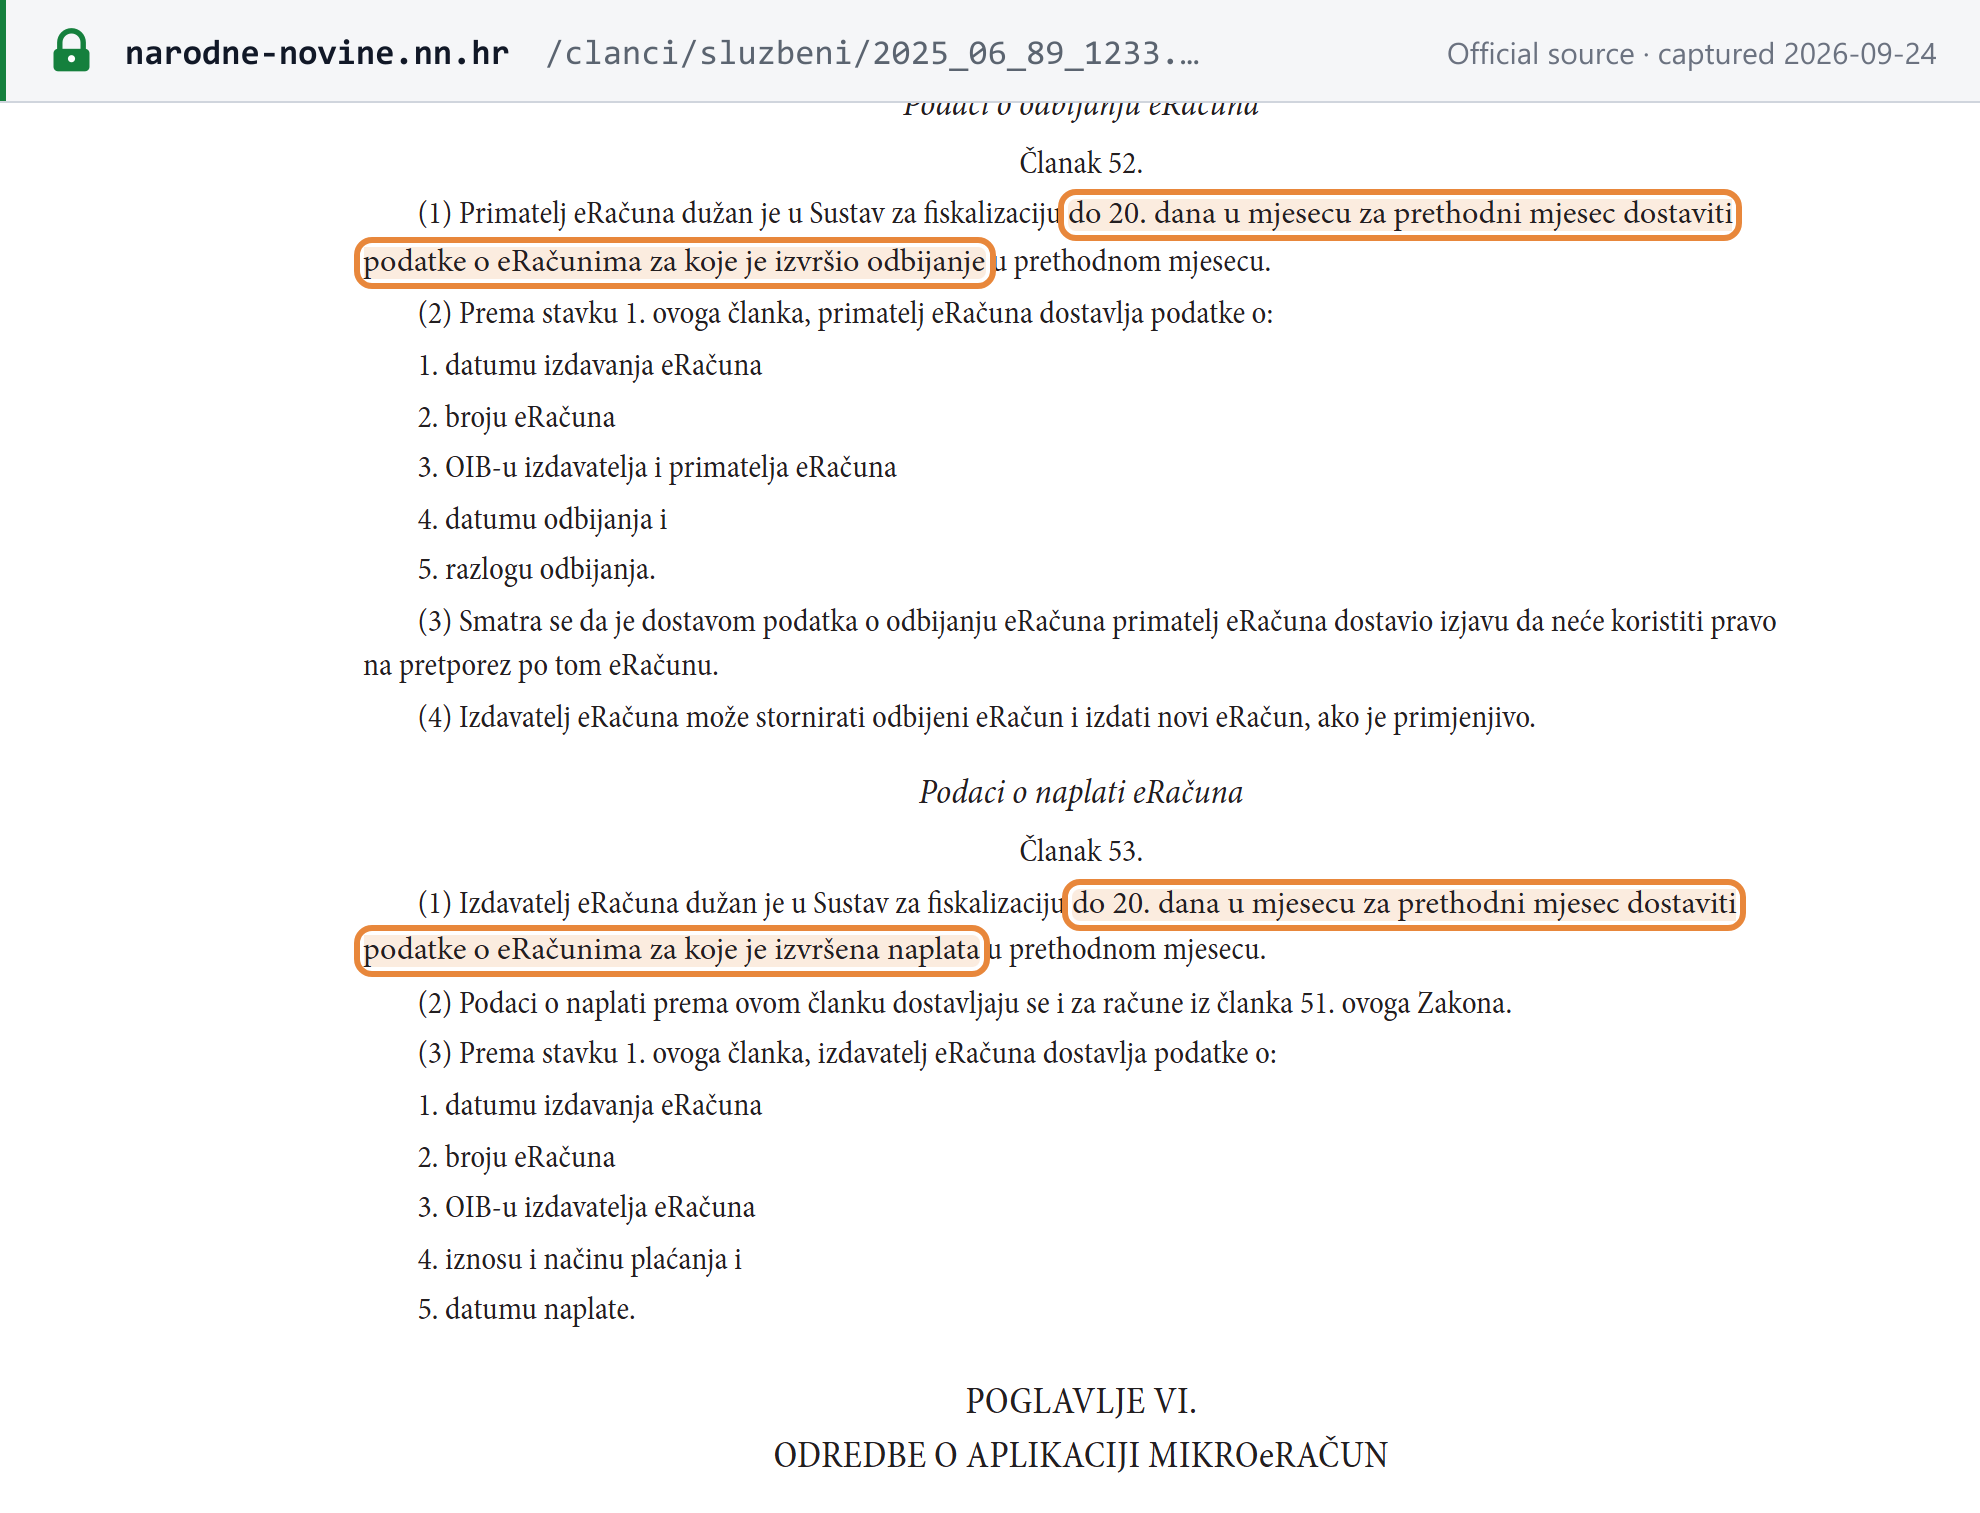
Zakon o fiskalizaciji (NN 89/2025) — čl. 53. st. 1. Narodne novine
See the source text
“(1) Izdavatelj eRačuna dužan je u Sustav za fiskalizaciju do 20. dana u mjesecu za prethodni mjesec dostaviti podatke o eRačunima za koje je izvršena naplata u prethodnom mjesecu.”
Screenshot of Narodne novine showing the eIzvještavanje o naplati eRačuna — monthly eRačun payment report deadline Open full size Captured from Narodne novine on 2026-10-07
eIzvještavanje o odbijanju eRačuna — monthly eRačun rejection report

Fiskalizacija eRačuna (e-reporting) · Monthly · report / listing

20th of the month after the month ends Verified 2026-10-07
Who files
Every recipient obliged to receive eRačun from 2026 — VAT-registered taxpayers, non-VAT income- and profit-tax payers and non-VAT public bodies alike — for months in which it rejected one
Notes
Rejected an eRačun last month? Report it by the 20th — the invoice date and number, both tax numbers, when you rejected it and why; November 2026's rejections are due Sunday 20 December. Reporting a rejection counts as declaring that you will not deduct input VAT on that invoice. This applies to businesses outside the VAT system too, from 2026, because they already have to receive eRačun. Separately, each eRačun you receive must be fiscalised within five working days.
Source
Zakon o fiskalizaciji (NN 89/2025) — čl. 52. st. 1. Narodne novine
See the source text
“(1) Primatelj eRačuna dužan je u Sustav za fiskalizaciju do 20. dana u mjesecu za prethodni mjesec dostaviti podatke o eRačunima za koje je izvršio odbijanje u prethodnom mjesecu.”
Screenshot of Narodne novine showing the eIzvještavanje o odbijanju eRačuna — monthly eRačun rejection report deadline Open full size Captured from Narodne novine on 2026-10-07
Zahtjev za registriranje za potrebe PDV-a (Obrazac P-PDV) on crossing EUR 60,000

Porez na dodanu vrijednost (VAT) · One-off · registration

within 8 days of the day annual domestic turnover exceeded EUR 60,000 (Rulebook Art 186(5)) Verified 2026-10-07
Who files
Taxable persons established in Croatia whose domestic turnover in the calendar year exceeds EUR 60,000
Notes
You enter the VAT register from the day after your turnover passes EUR 60,000 in the calendar year, and you have 8 days to apply on form P-PDV. Miss it and the tax office registers you itself, backdated to the same day. Older guidance pointing to 15 January of the following year describes a rule that no longer applies; the only 15 January dates today are the requests to leave the register or to change between monthly and quarterly returns. Businesses established outside Croatia must register before their first Croatian taxable supply, unless an EU-established business uses the cross-border SME exemption in Croatia.
Source
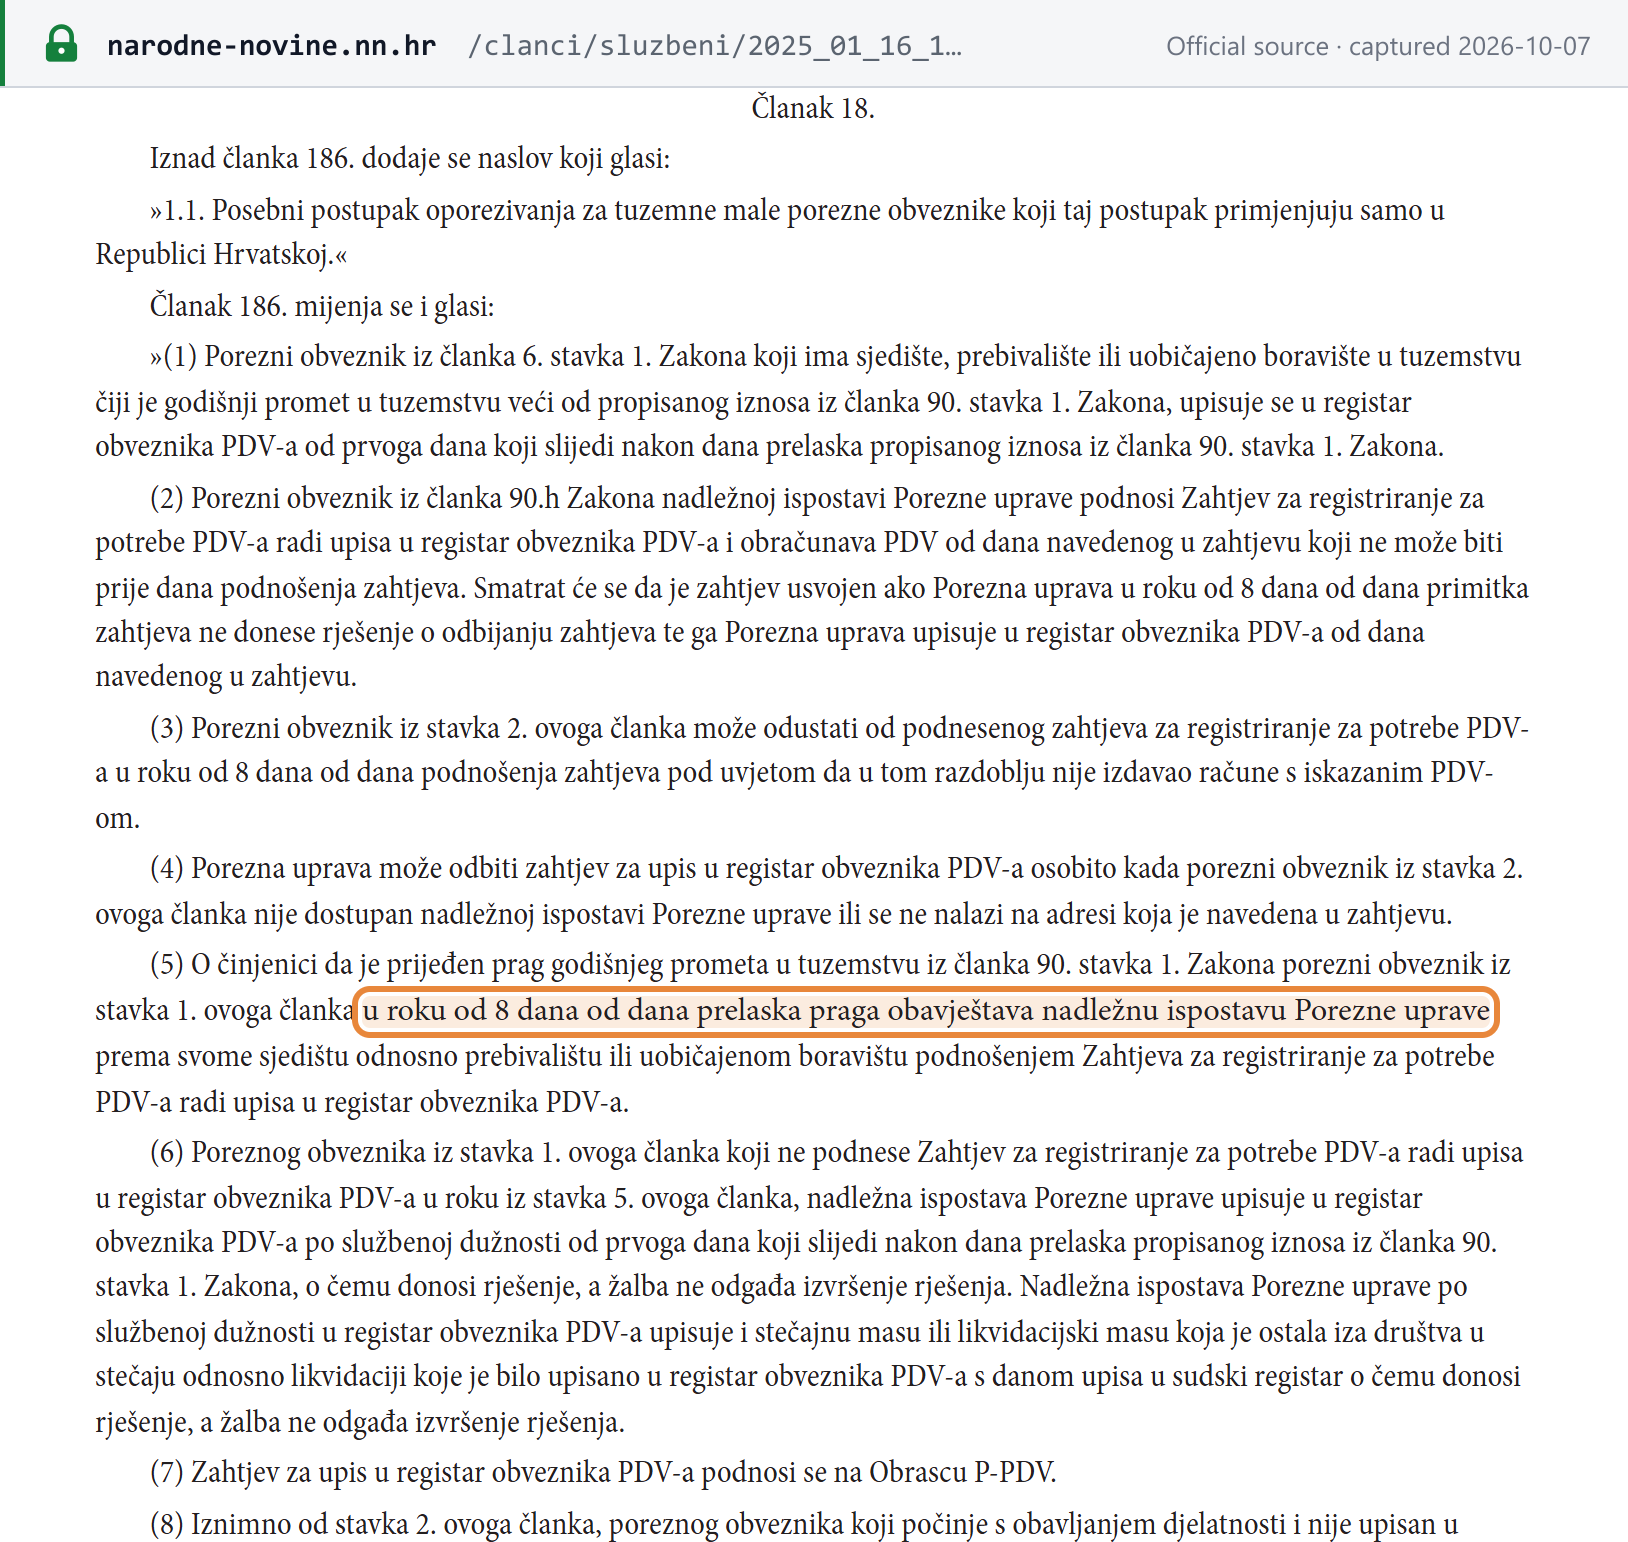
Pravilnik o izmjenama i dopunama Pravilnika o porezu na dodanu vrijednost (NN 16/2025) — čl. 18. (čl. 186. Pravilnika) Narodne novine
See the source text
“u roku od 8 dana od dana prelaska praga obavještava nadležnu ispostavu Porezne uprave prema svome sjedištu odnosno prebivalištu ili uobičajenom boravištu podnošenjem Zahtjeva za registriranje za potrebe PDV-a radi upisa u registar obveznika PDV-a.”
Screenshot of Narodne novine showing the Zahtjev za registriranje za potrebe PDV-a (Obrazac P-PDV) on crossing EUR 60,000 deadline Open full size Captured from Narodne novine on 2026-10-07

Porezna uprava has moved a Saturday filing deadline to the following Monday, and the same is applied here to the VAT return, the PDV-S and the EC Sales List: when their last day is a Saturday, Sunday or public holiday, they are shown on the next working day. Every other date in this calendar is shown exactly as the law states it, because we have found no official rule that moves it — so treat a weekend date there as final. Public holidays come from the holidays act; a holiday falling on a Sunday creates no substitute day. Since January 2026 the return, PDV-S and EC Sales List are due on the last day of the following month instead of the 20th, and the book of received invoices (U-RA) and the domestic reverse-charge listing (PPO) were abolished. There has been no annual VAT return (PDV-K) since 2015. Not shown because they run from events: the threshold notice under the EU small-business scheme and the per-invoice eRačun fiscalisation duties. Excise, the local consumption tax, income and profit tax and payroll are out of scope.

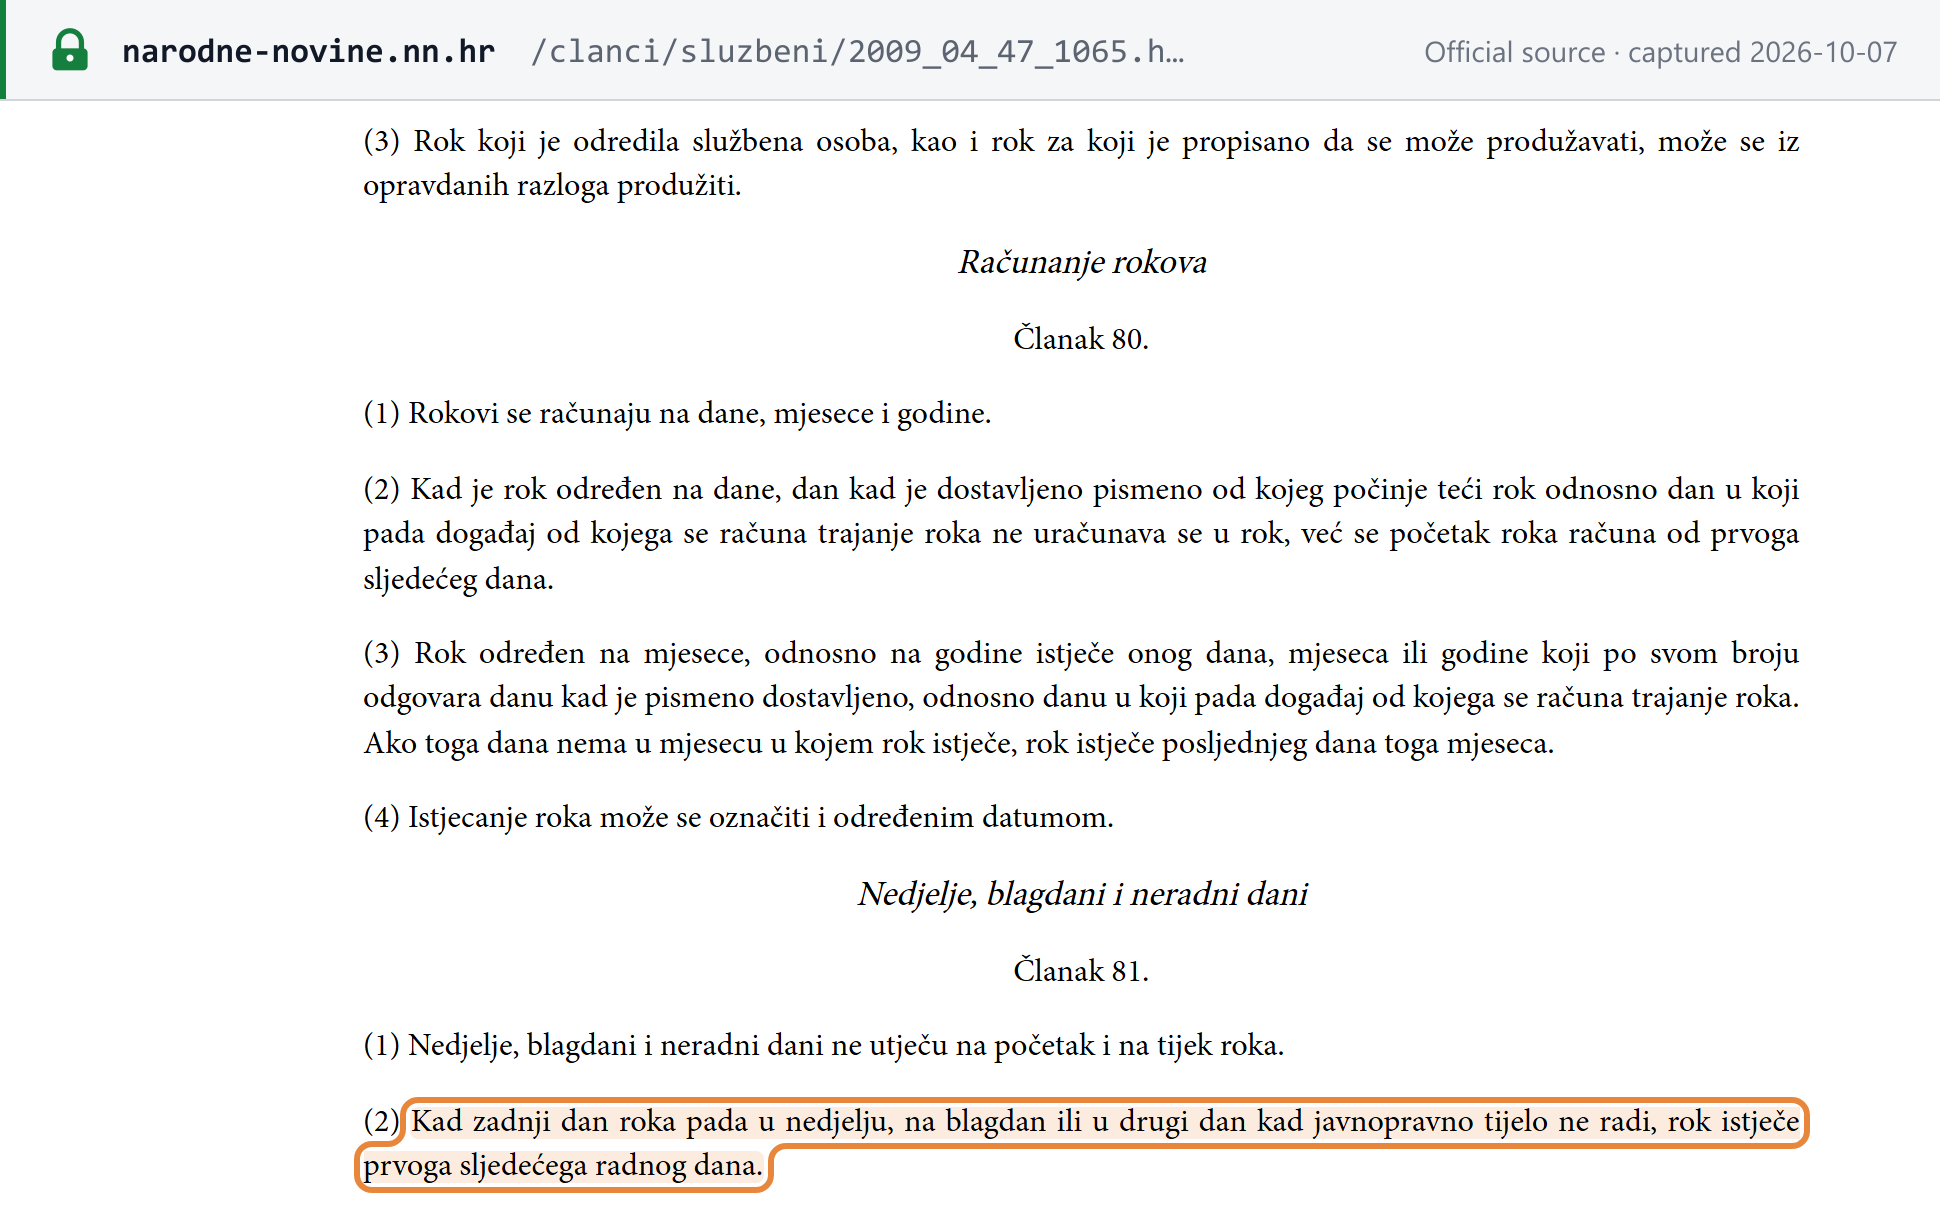
“(2) Kad zadnji dan roka pada u nedjelju, na blagdan ili u drugi dan kad javnopravno tijelo ne radi, rok istječe prvoga sljedećega radnog dana.”
Screenshot of the official source stating the rule that governs Croatia's deadlines
Zakon o općem upravnom postupku (NN 47/2009) — čl. 81. st. 2. (nedjelje, blagdani i neradni dani) — Narodne novine, captured 2026-10-07

What this calendar does not list

  • Not applicable Annual or reconciliation return — Croatia has had no annual VAT return since tax year 2015. The annual final return (konačni obračun PDV-a, Obrazac PDV-K, due by the end of February) was abolished by the VAT Act amendment in Narodne novine 143/2014, which replaced Art 85(7) with a duty to make every adjustment and correction for the calendar year in the return for the last tax period of that year: "(7) Porezni obveznik mora u prijavi PDV-a koju podnosi za posljednje razdoblje oporezivanja kalendarske godine napraviti sva usklađenja i ispravke za tu kalendarsku godinu." The Rulebook mirrored it (NN 157/2014, Art 173(6)) and its transitional rule made the 2014 PDV-K the last one. Every VAT Act and Rulebook amendment 2015-2026 was searched for "PDV-K" and "konačni obračun" with no revival found (checked 2026-10-07).

New Croatia rules taking effect

Confirmed changes from the weekly scan — each links to its full record with the official source.

About this calendar

Which Croatia tax deadlines does this calendar cover?

15 recurring indirect-tax obligations — Porez na dodanu vrijednost (VAT) and Fiskalizacija eRačuna (e-reporting) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-07). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.