Přiznání k DPH — monthly
Daň z přidané hodnoty (VAT) · Monthly · return filing
25th of the month after the month ends Verified 2026-09-23- Who files
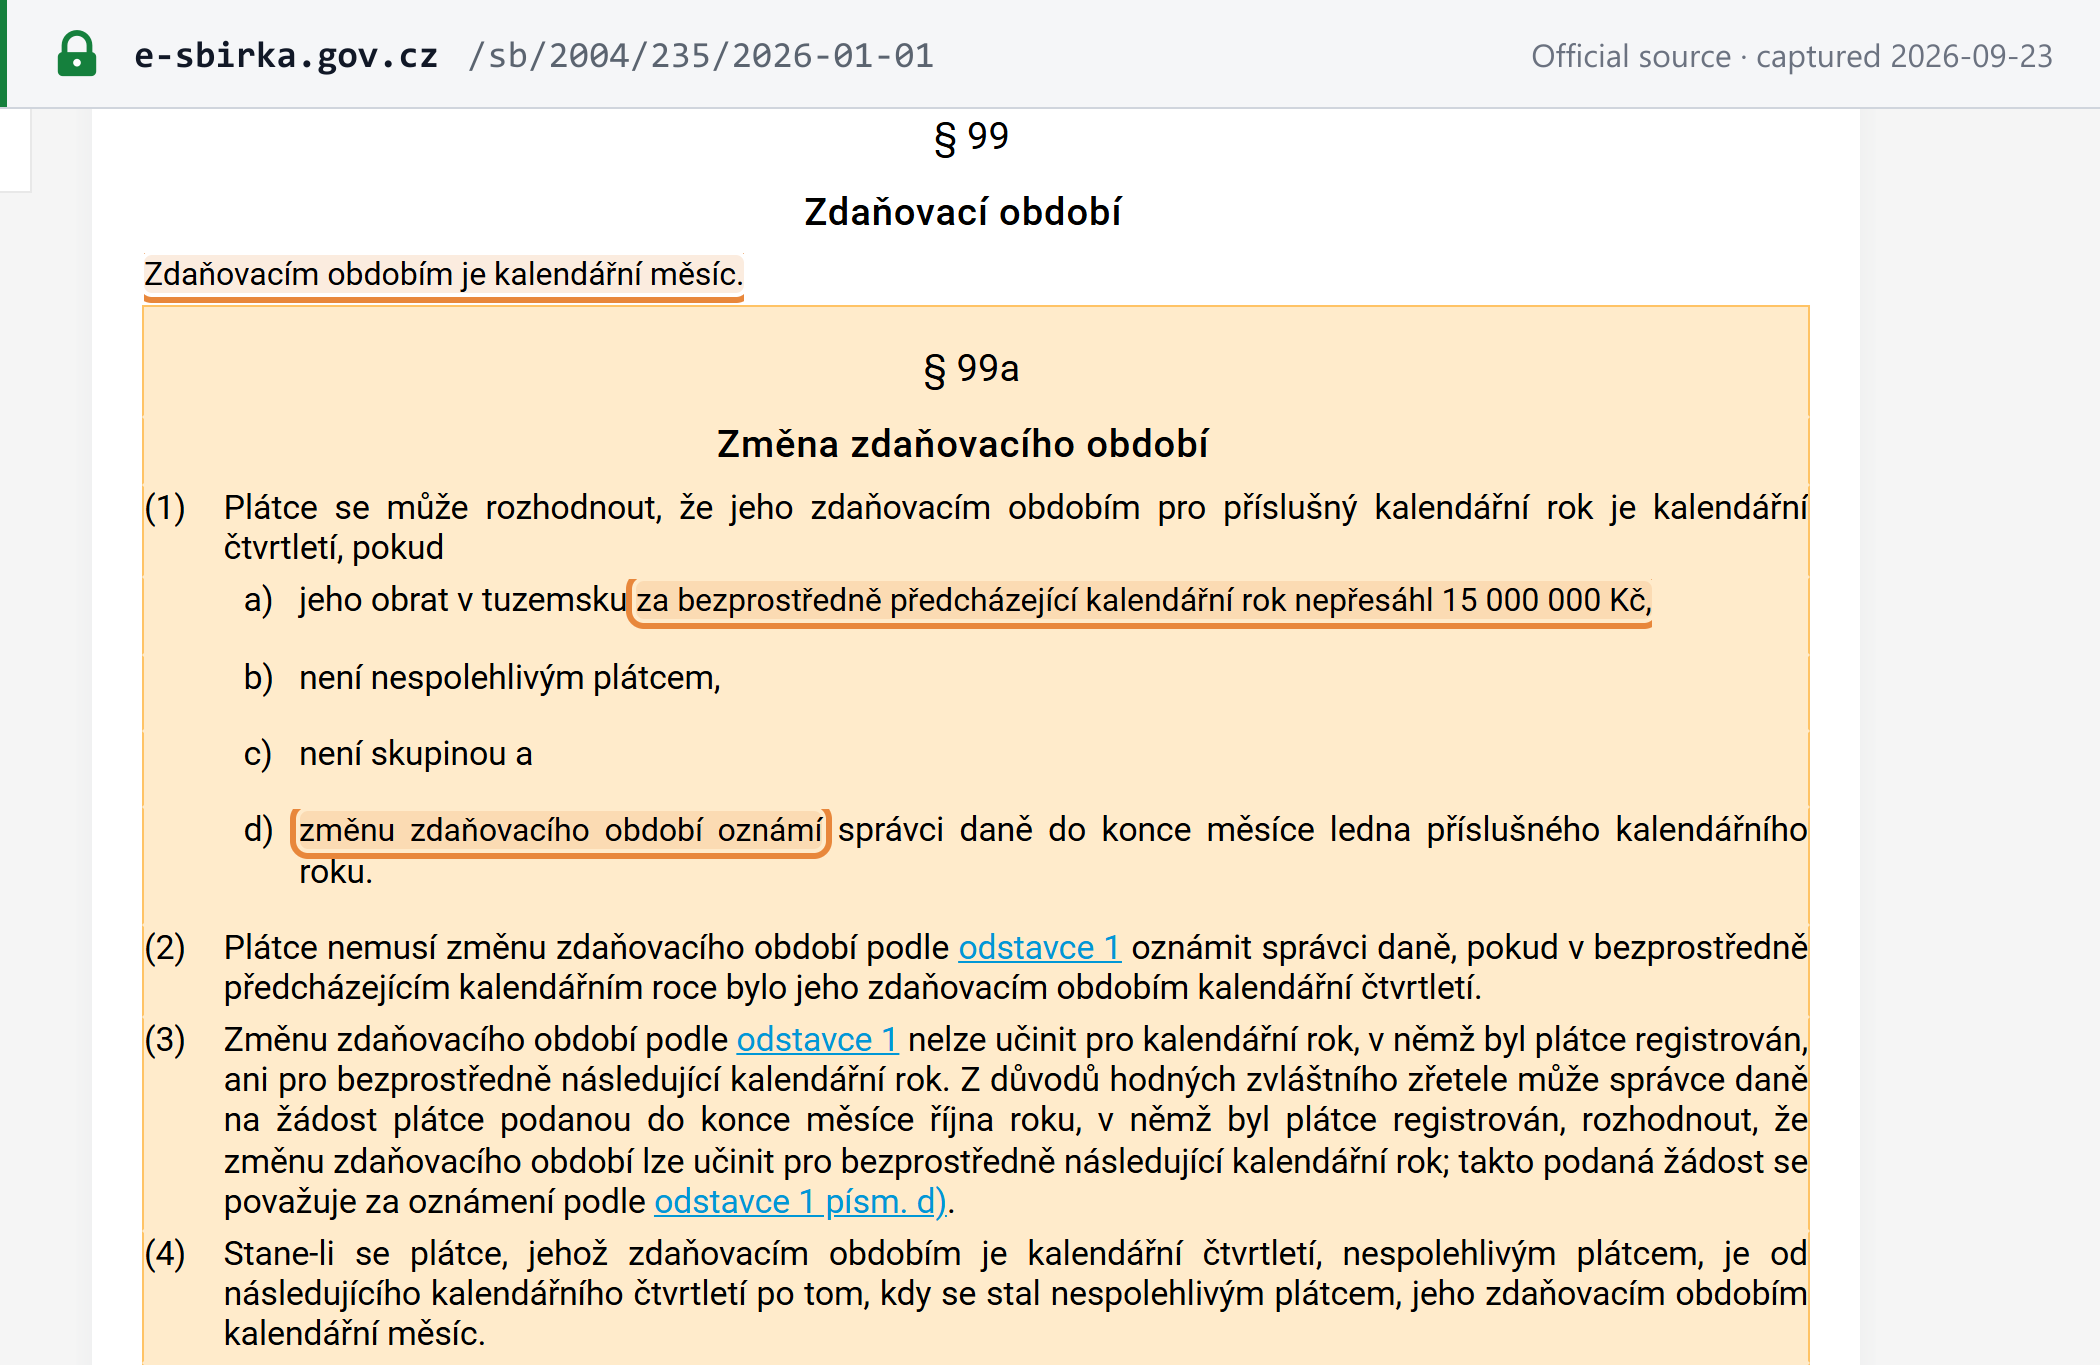
- Every VAT payer (plátce) on the default monthly tax period — anyone who has not elected, or cannot elect, the calendar quarter, including every VAT group and every unreliable payer
- Notes
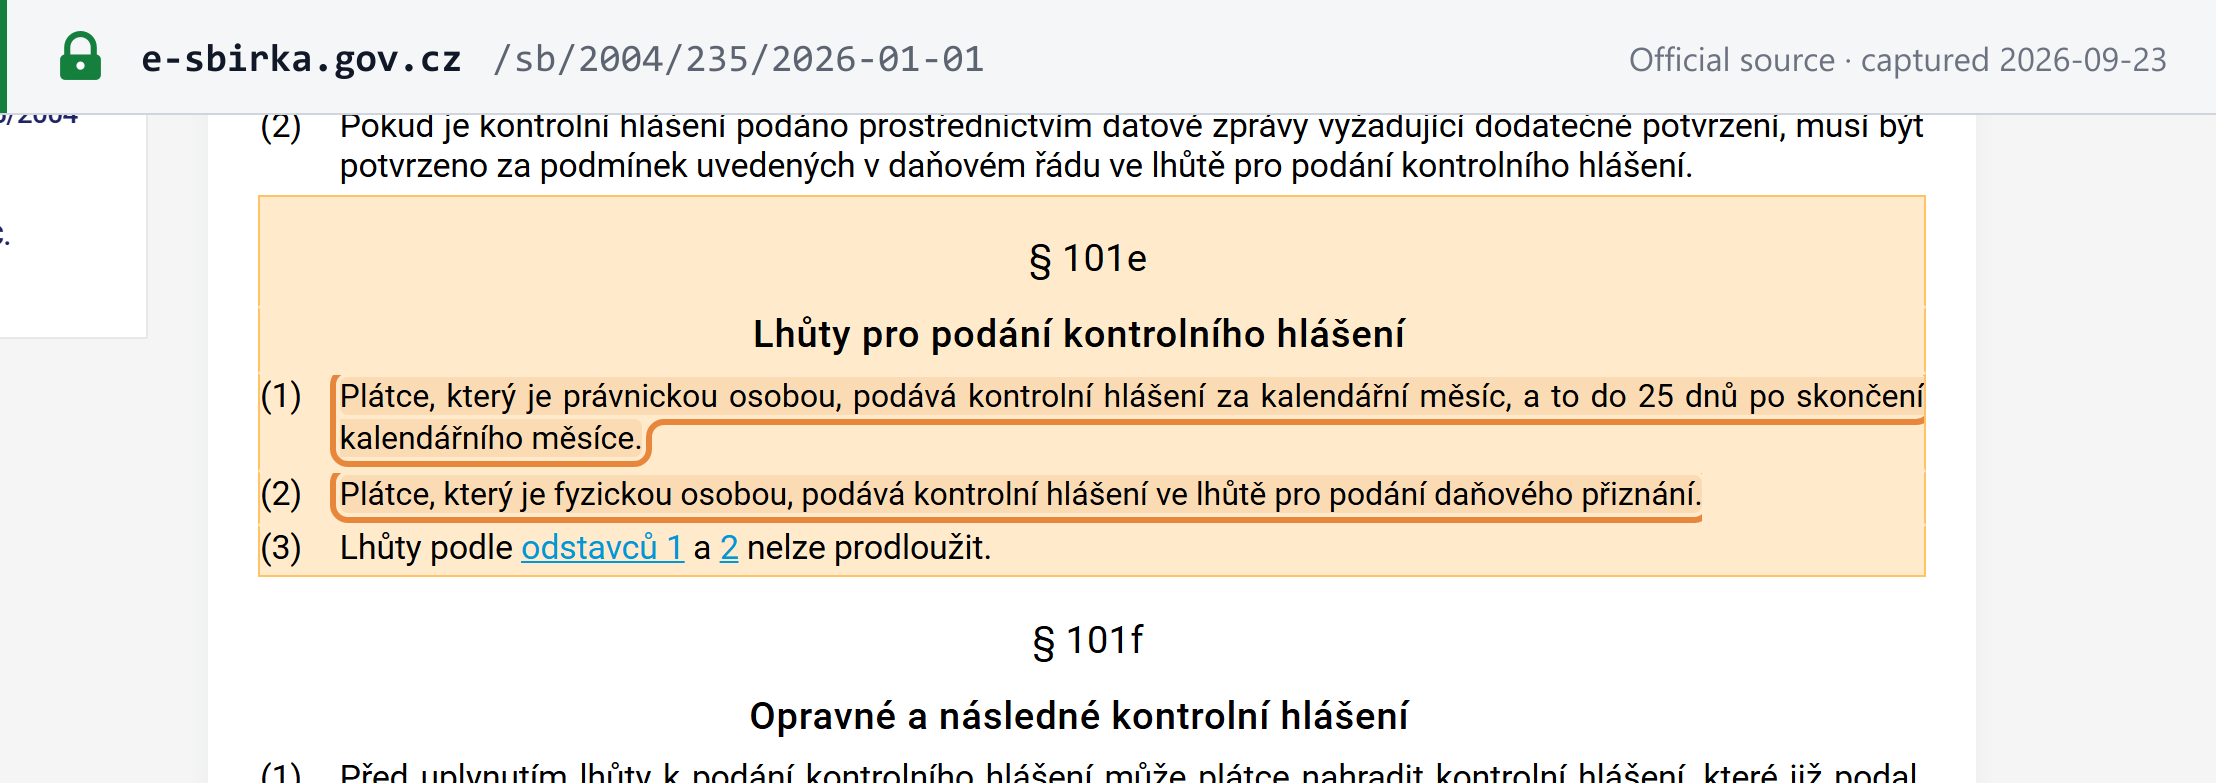
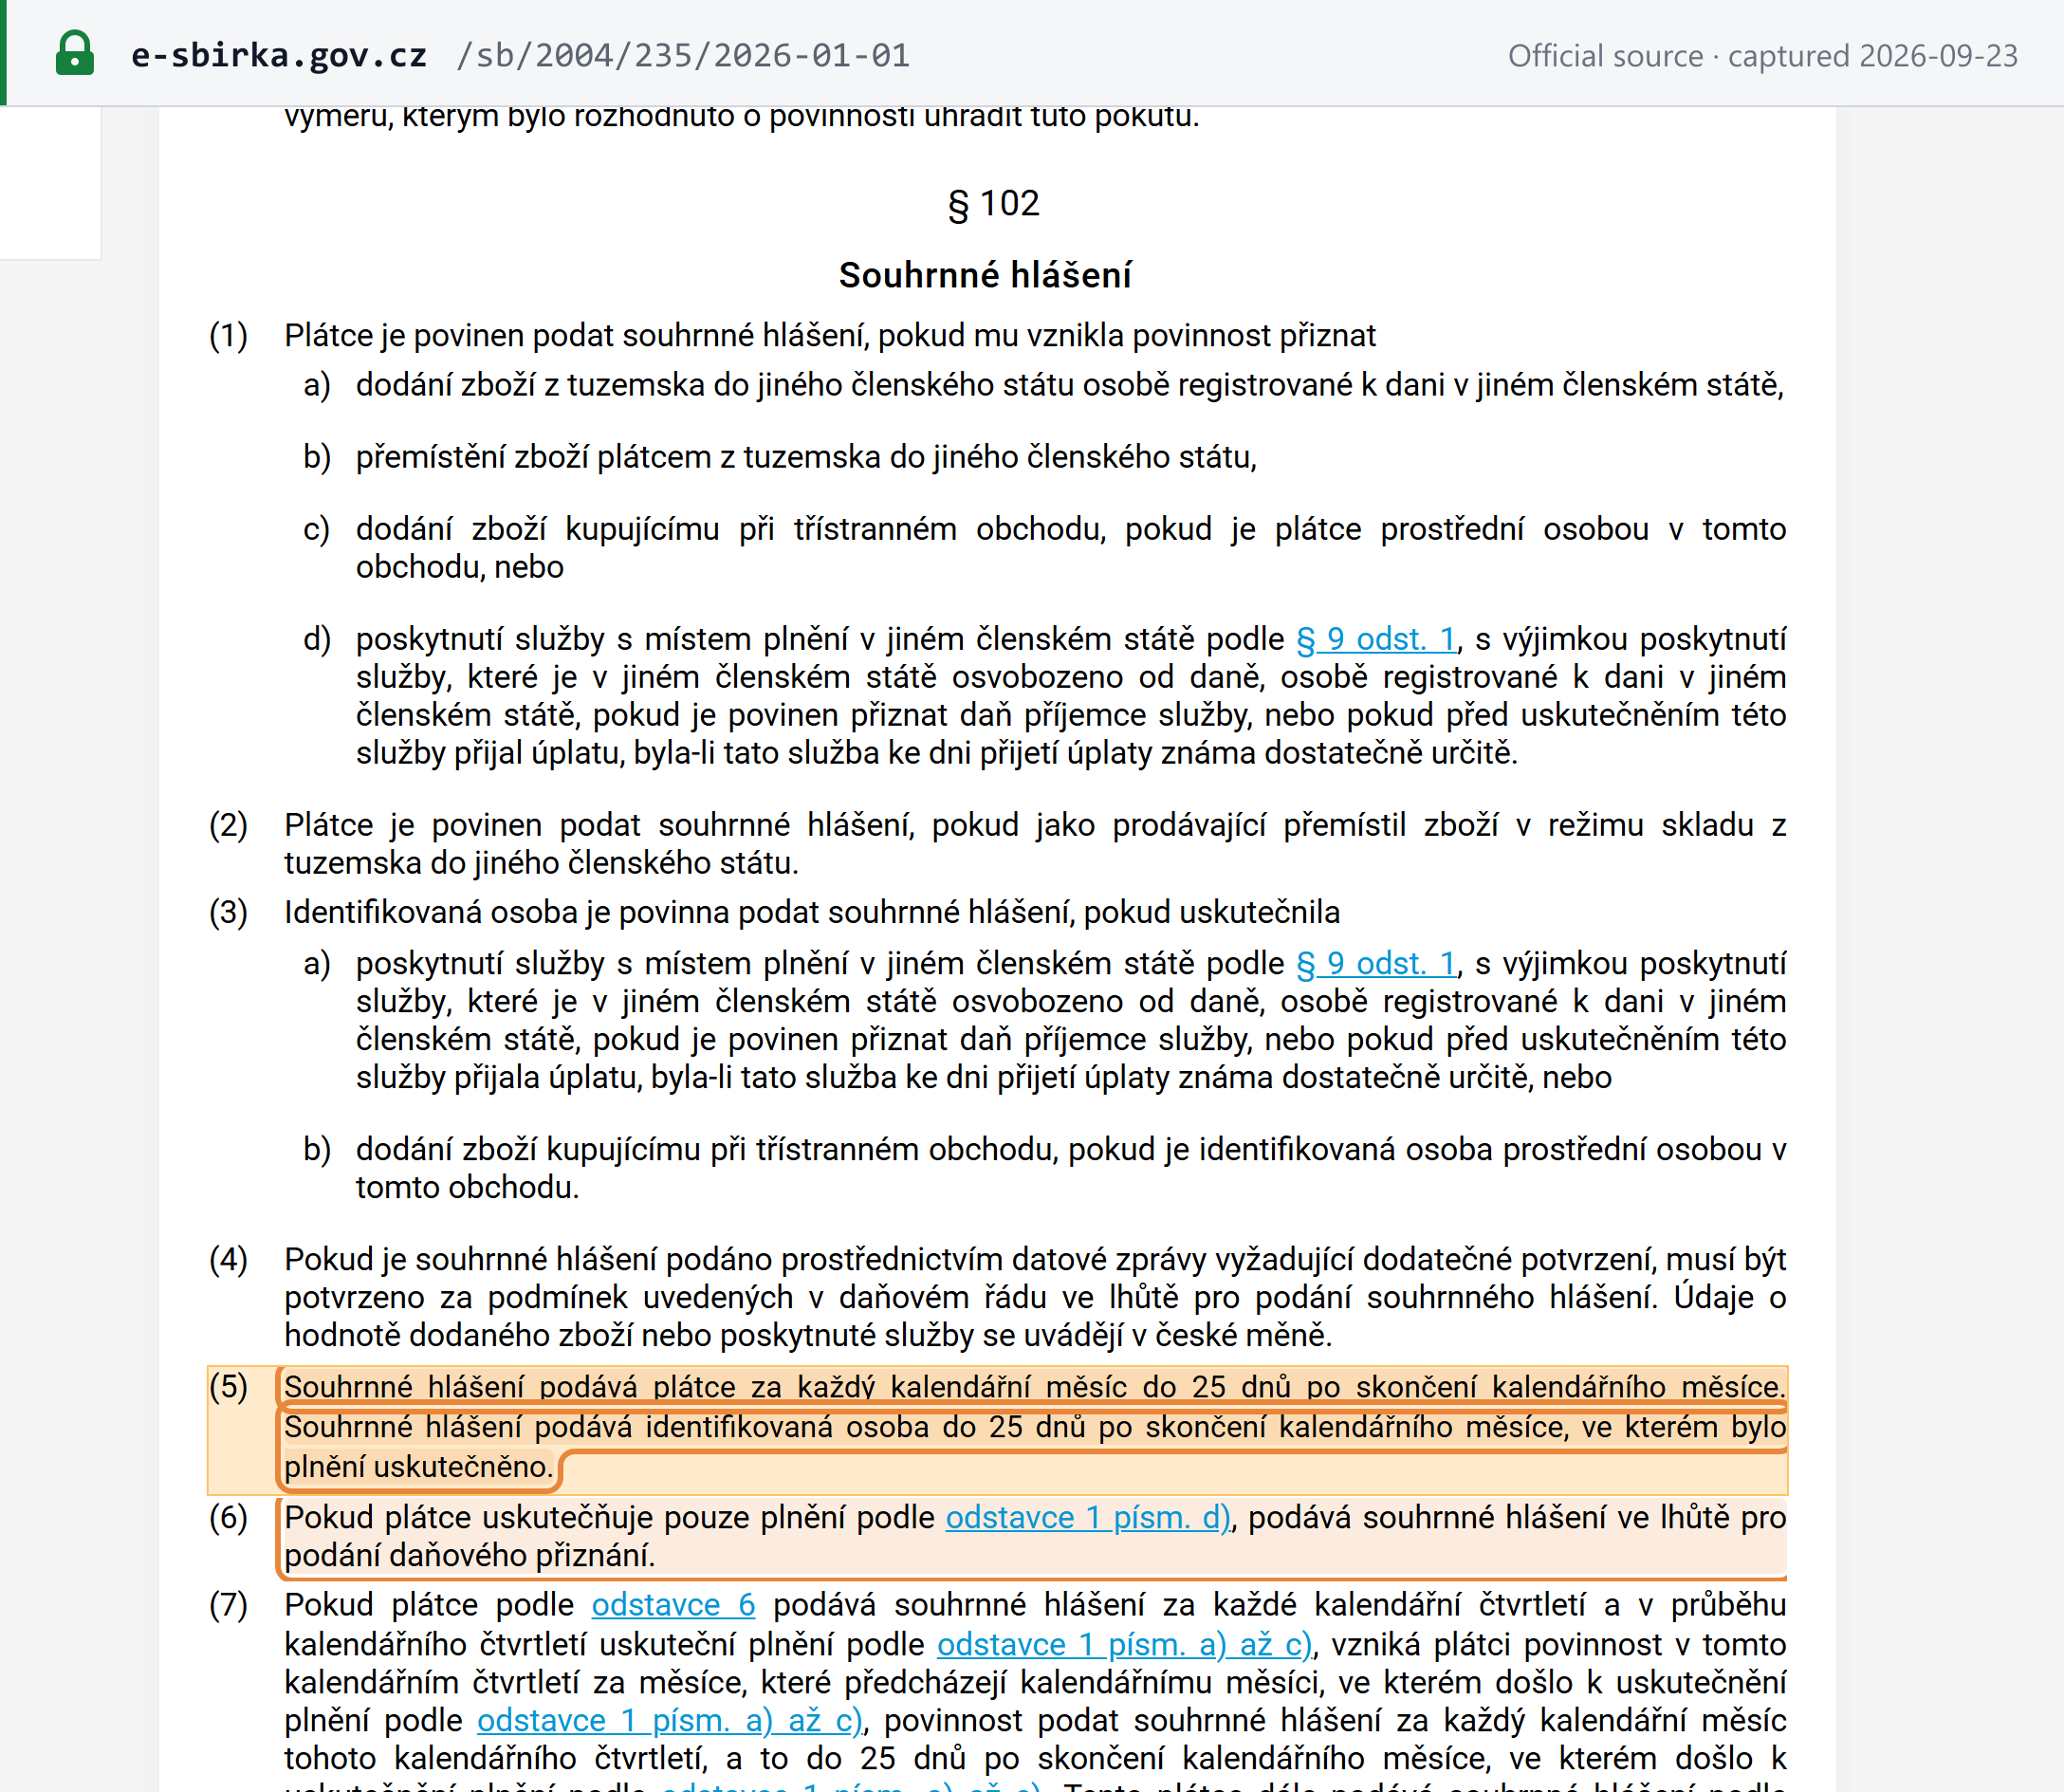
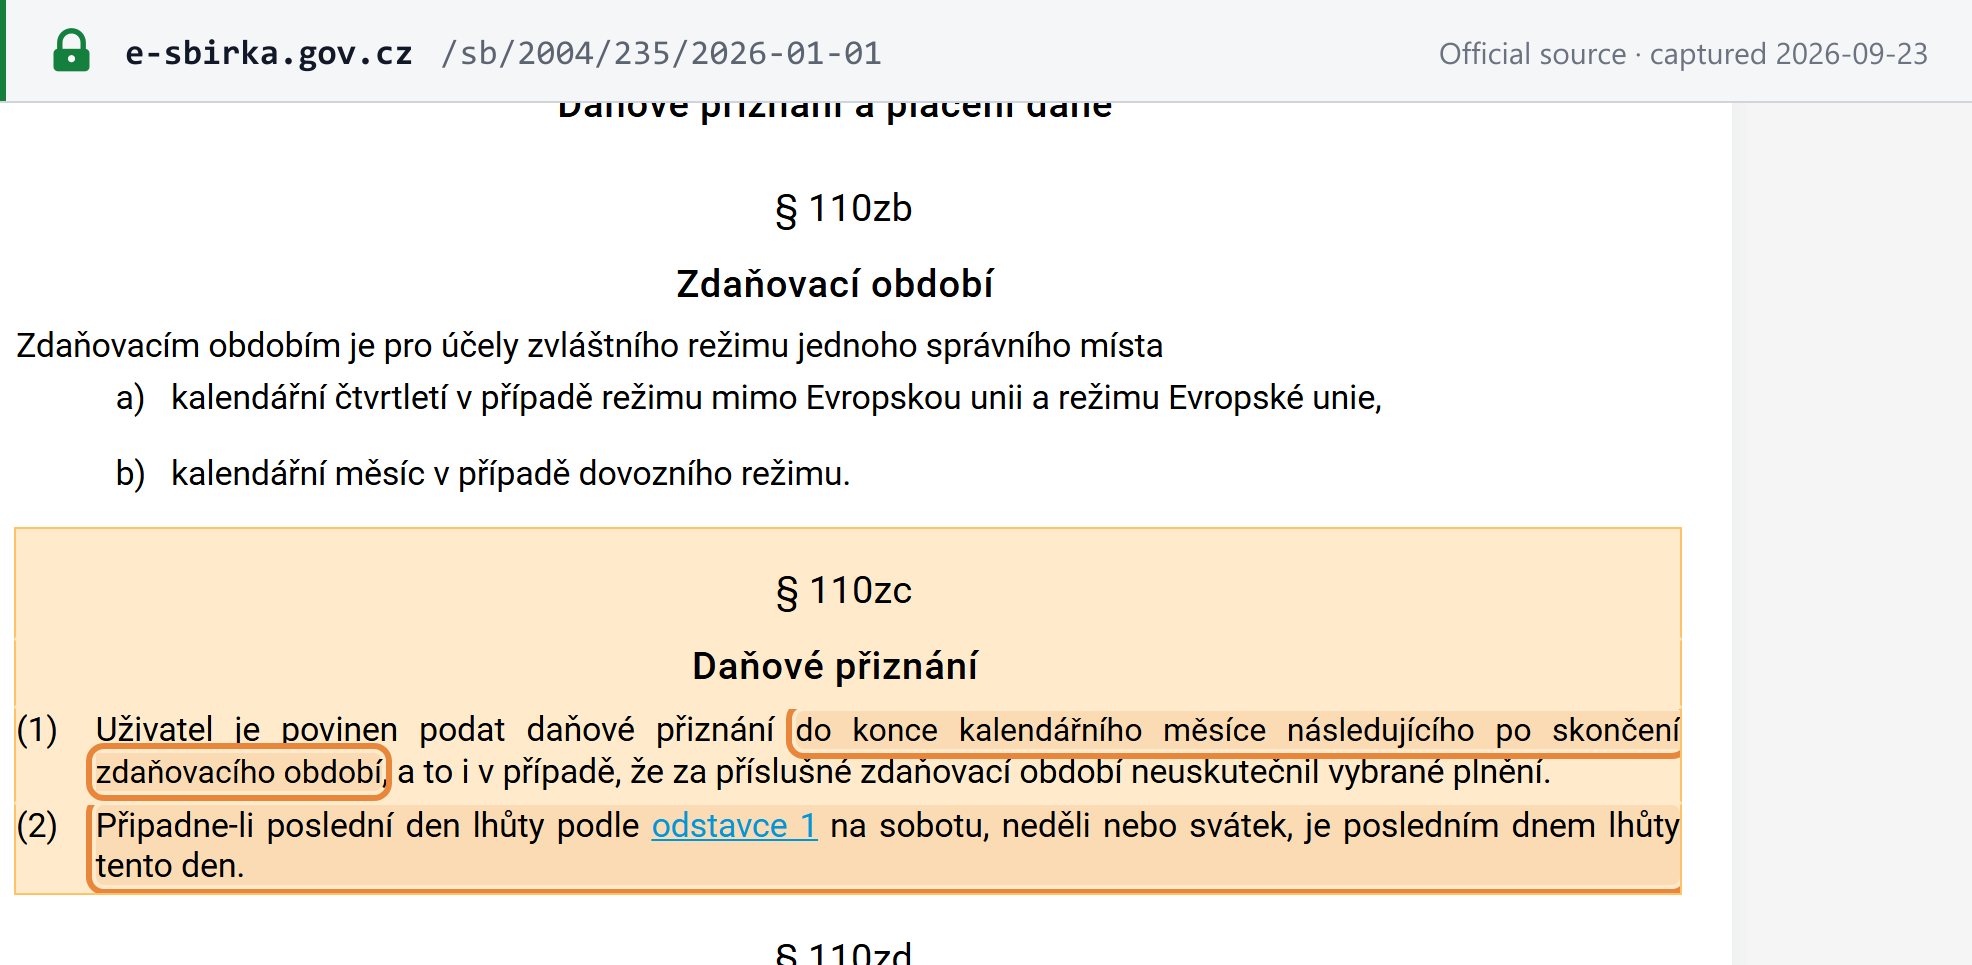
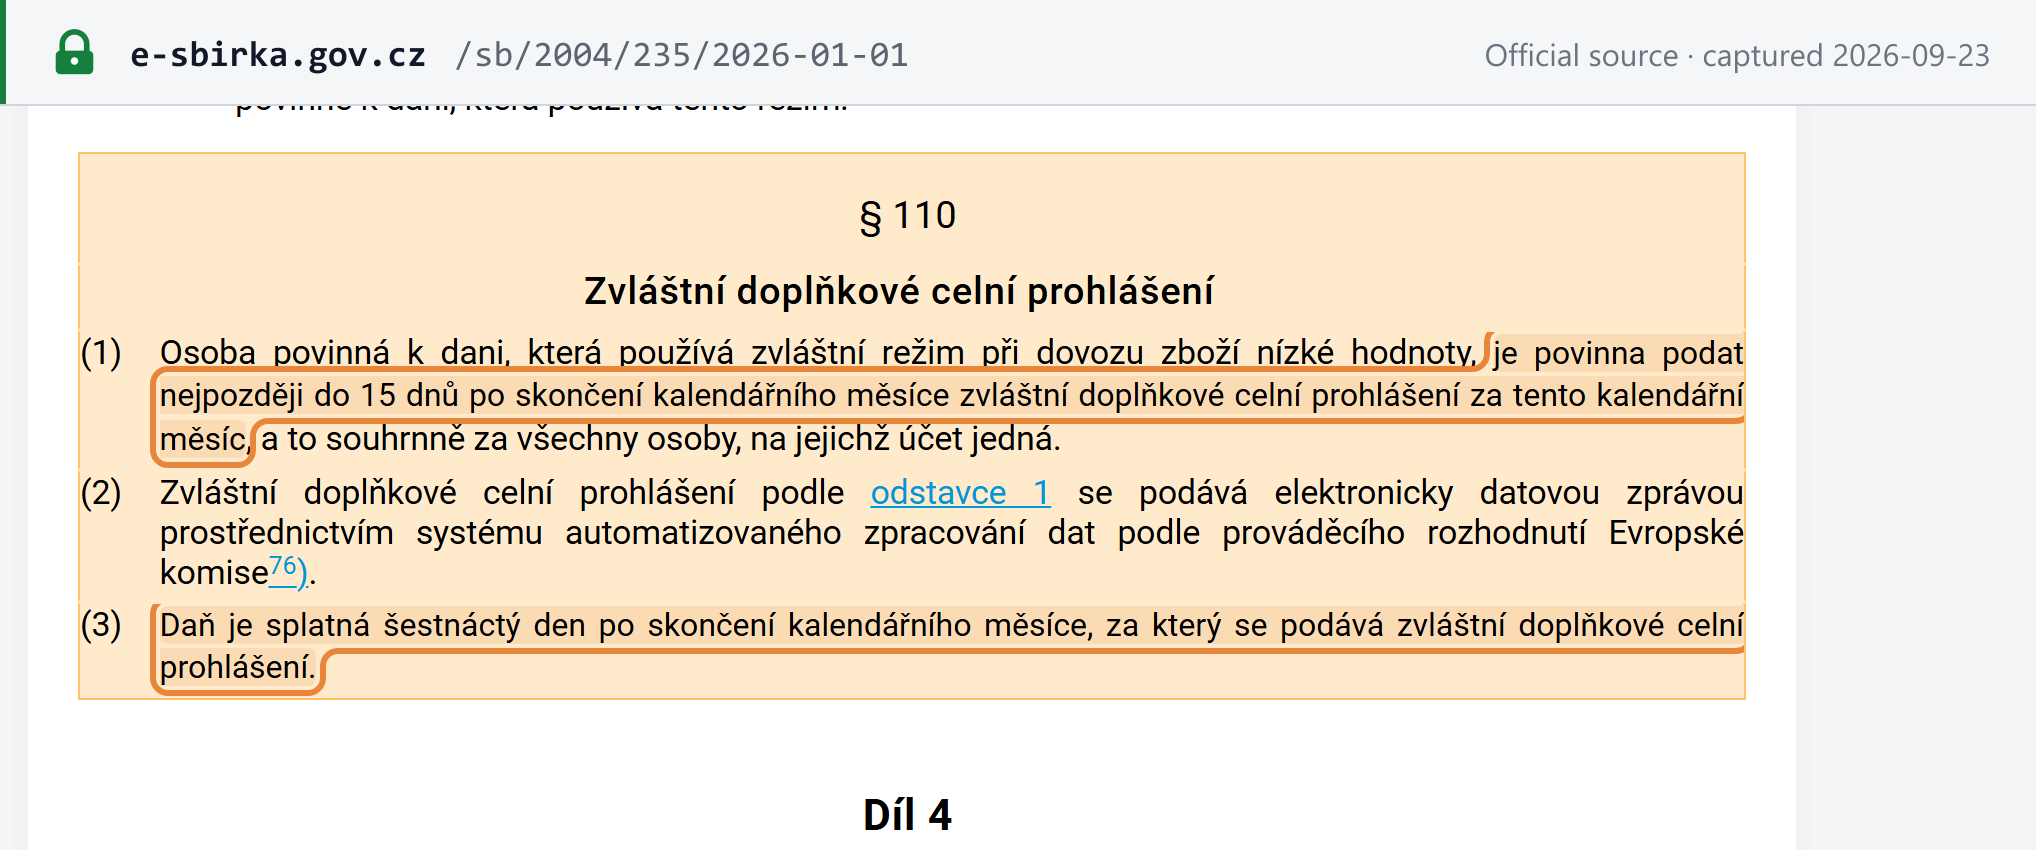
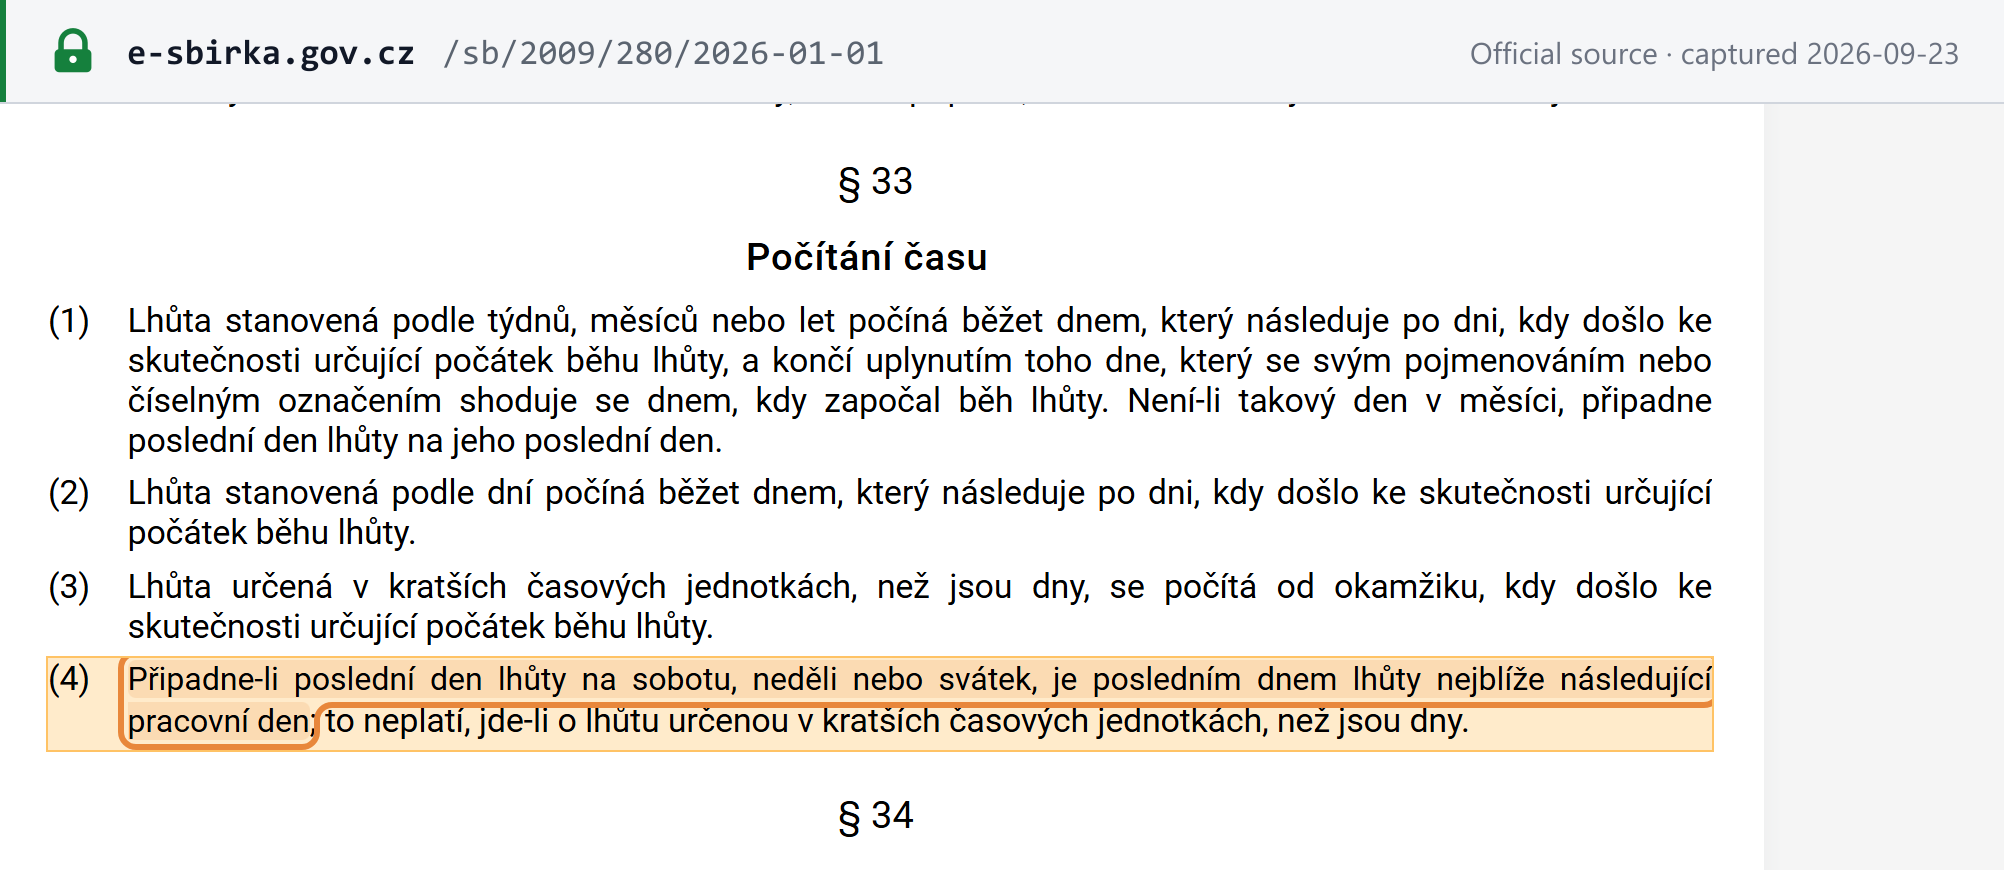
- The return and the tax are both due by the 25th of the month after the month ends, and the deadline cannot be extended. If the 25th is a Saturday, Sunday or public holiday you have until the next working day — which is why the November 2026 return is due on Monday 28 December. File it even for a month with nothing to declare. The only filing route is electronic: a return sent in any other form is treated as not filed at all. A payer with no seat or establishment in Czechia is the exception to the nil-return duty and files only for months with something to report.
- Source
- Zákon č. 280/2009 Sb., daňový řád — § 136 odst. 4 (lhůta pro daňové přiznání) a § 135 odst. 3 (splatnost) e-Sbírka — Sbírka zákonů České republiky
See the source text
“Je-li zdaňovací období kratší než 1 rok, podává se daňové přiznání do 25 dnů po uplynutí zdaňovacího období. Tuto lhůtu nelze prodloužit.”
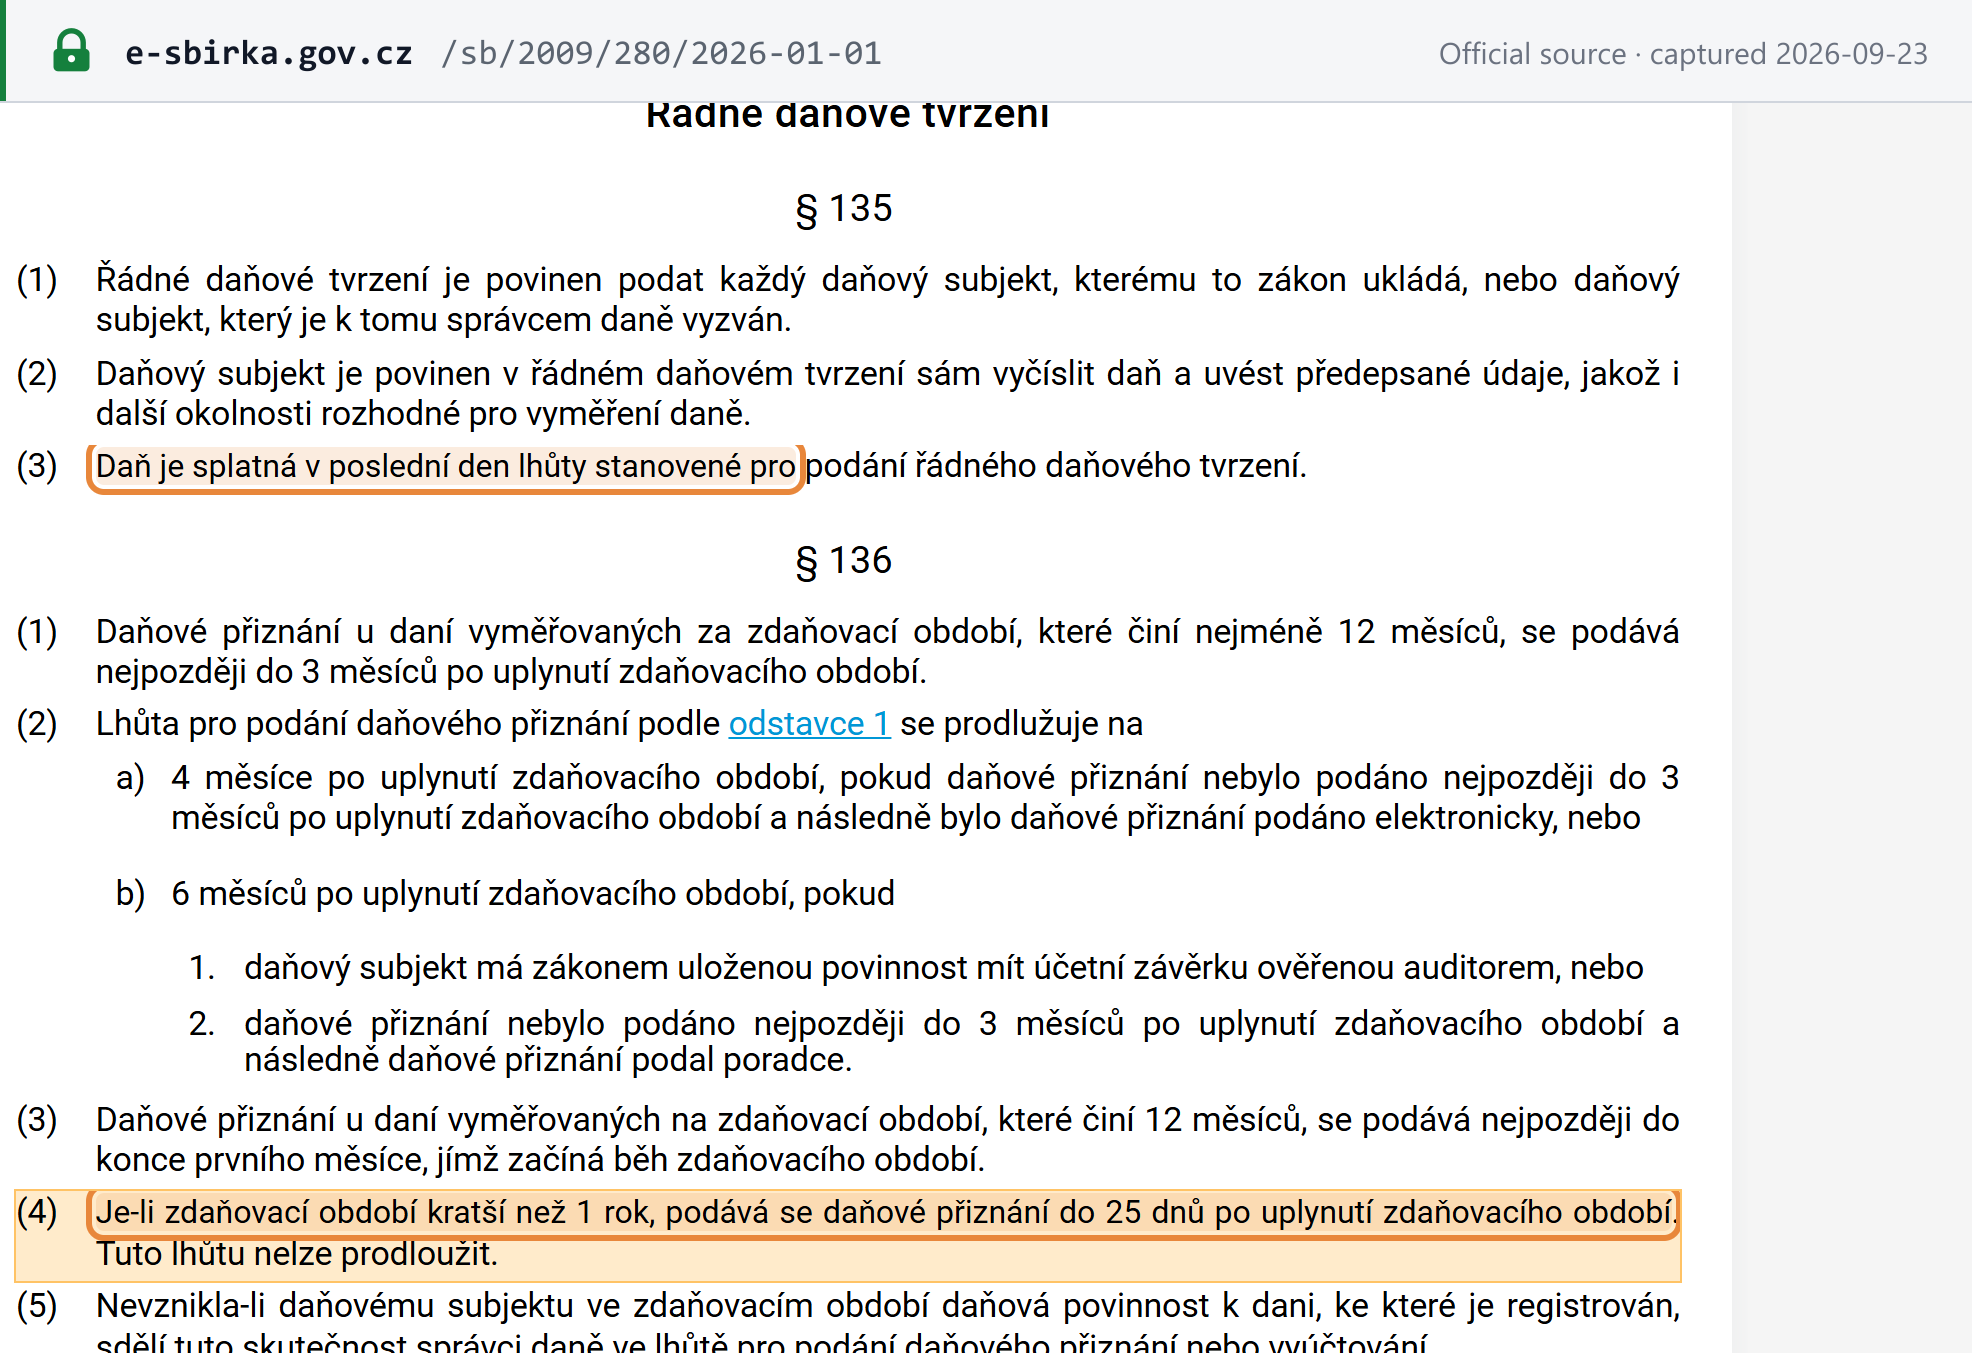 Open full size Captured from e-Sbírka — Sbírka zákonů České republiky on 2026-09-23