Form 10 — monthly VAT and Table Tax return (نموذج رقم ١٠)
Value Added Tax (VAT) and Table Tax · Monthly · return filing
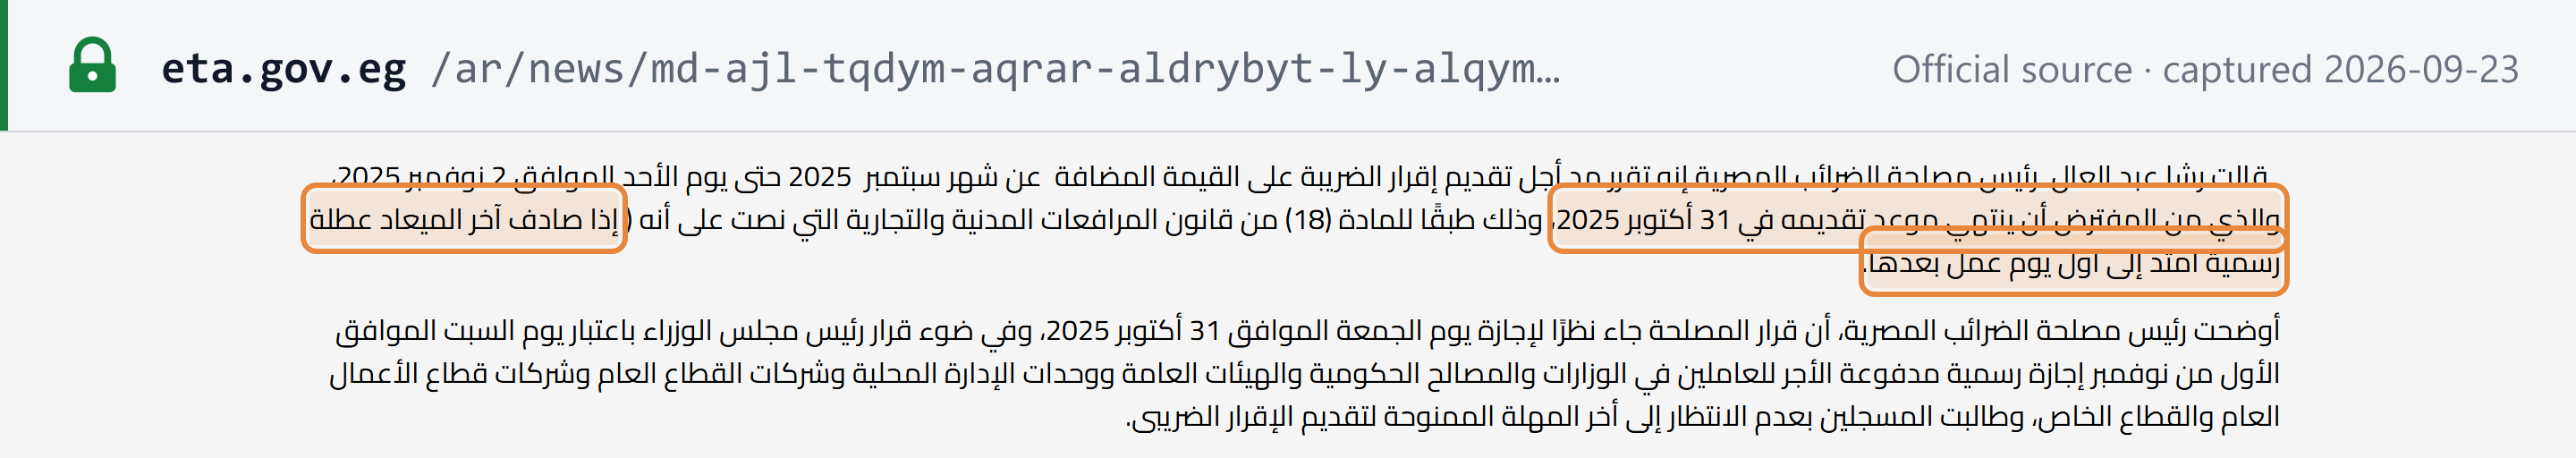
last day of the month after the month ends Verified 2026-09-23- Who files
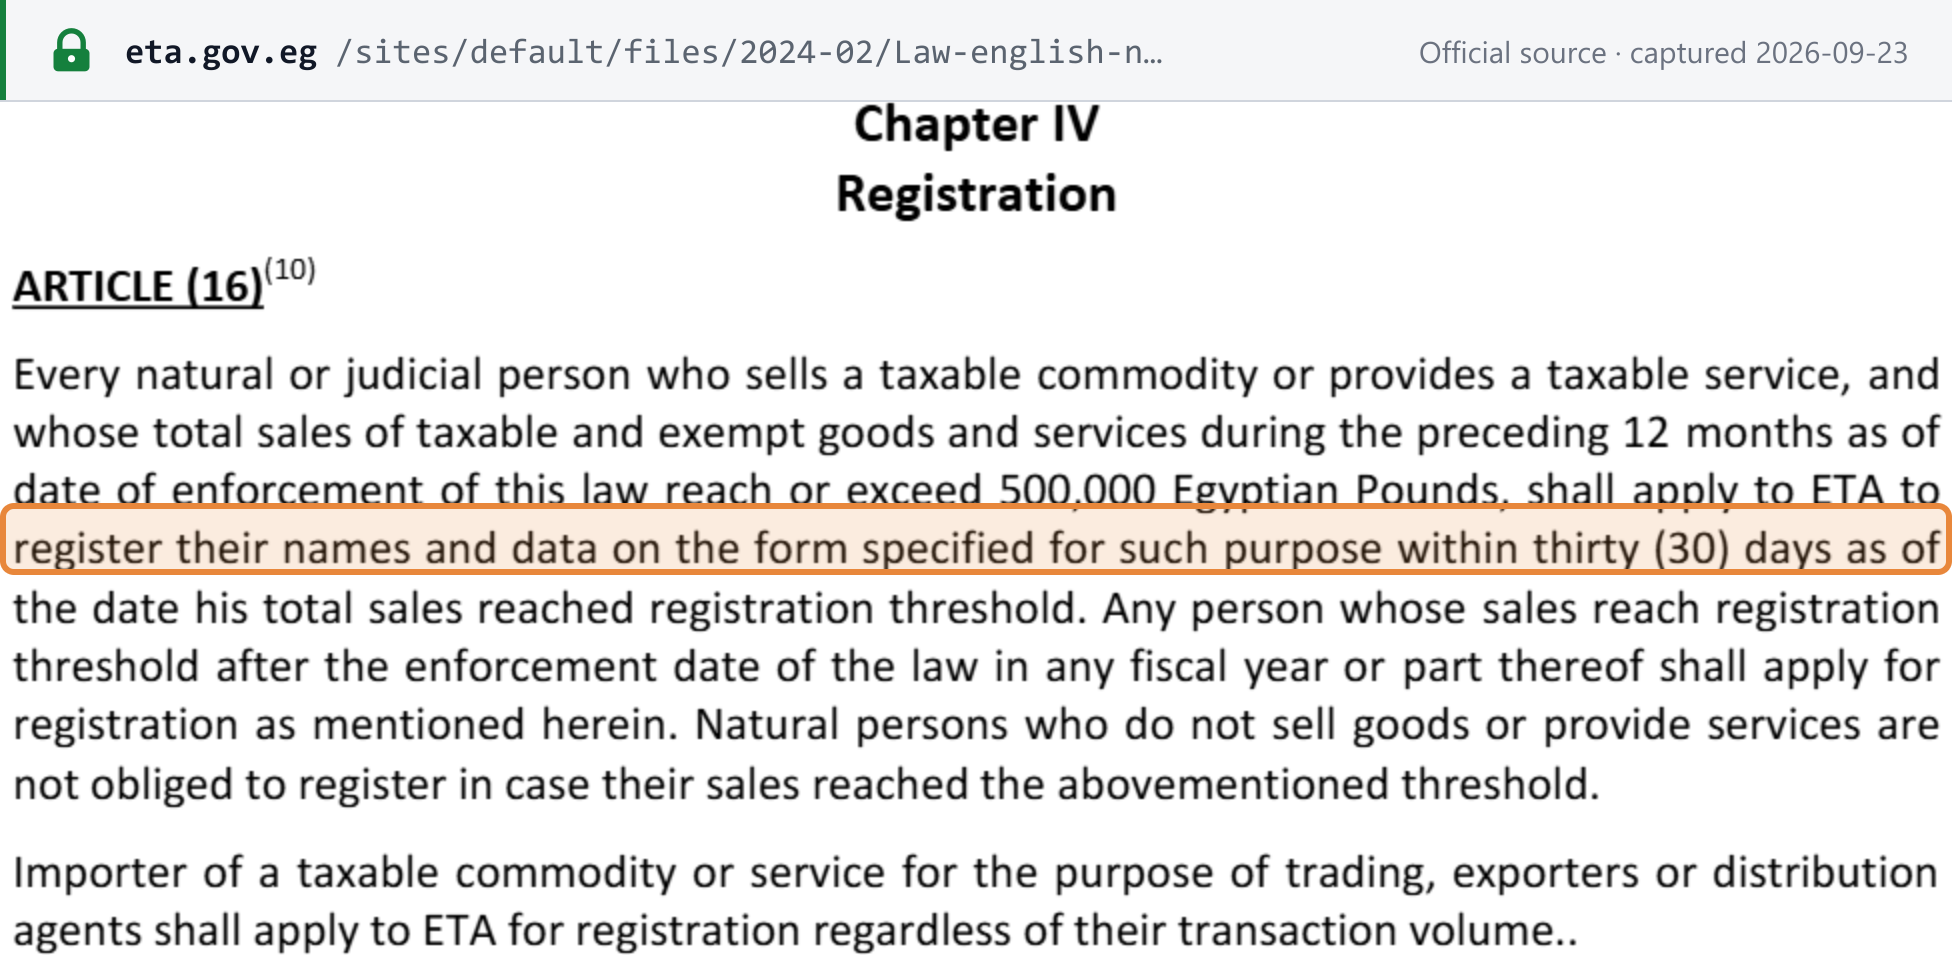
- Every VAT registrant — the compulsory registration threshold is EGP 500,000 of taxable and exempt sales in 12 months; importers, exporters, distribution agents and Table-Tax suppliers register whatever their turnover
- Notes
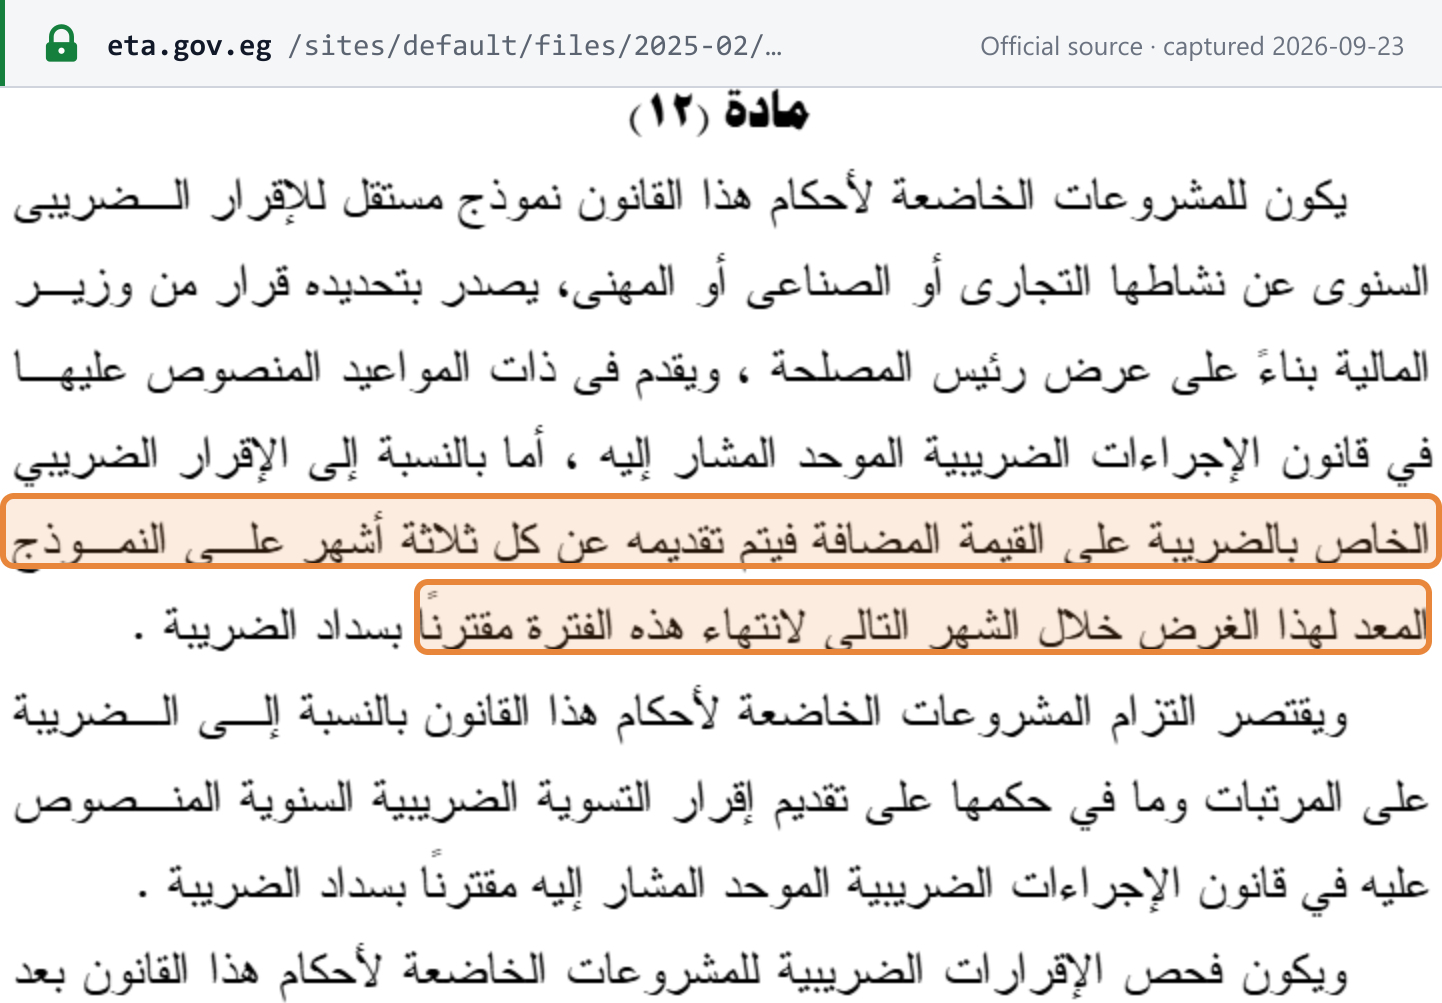
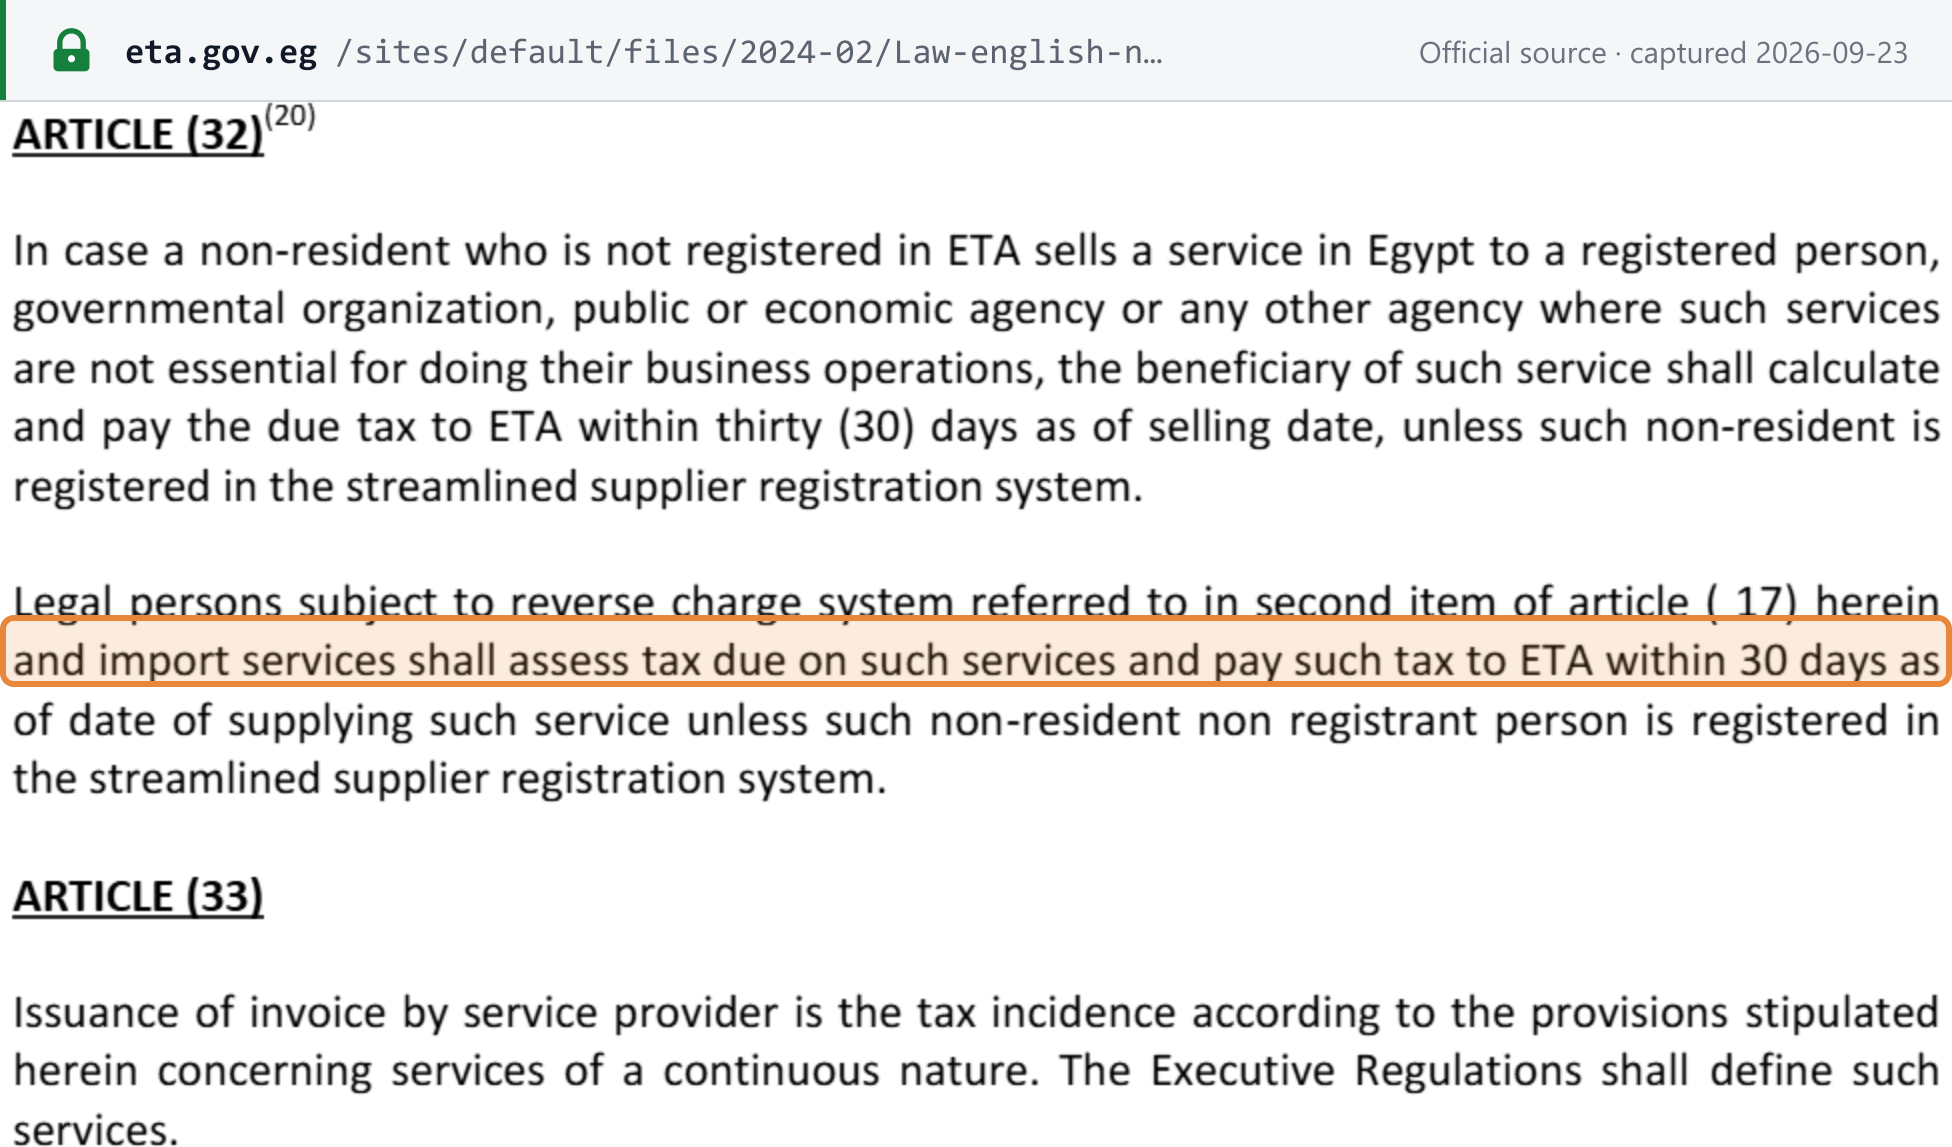
- The tax period is the calendar month, and its return is due by the last day of the following month — the May return by 30 June. File every month, even with no sales, and pay the tax shown on the return the same day you file it. Any late filing is an offence under Article 69 of the Unified Tax Procedures Law (fine EGP 3,000 to 50,000 on top of the tax); more than 60 days late is a heavier offence under Article 70 (EGP 5,000 to 200,000). Non-resident suppliers under the simplified registration scheme file their own monthly return, Form 10/1, by the same date. ETA can let exporters, importers and service providers who trade once or twice a year file only for the month of the transaction.
- Source
- إقرار الضريبة على القيمة المضافة يقدم شهريًا على نموذج رقم(10) Egyptian Tax Authority
See the source text
“والتي تنتهي في آخر يوم من الشهر الميلادي الذي يقدم عنه الإقرار ، مع العلم بأن الإقرار يقدم شهريًا ، ومهلة تقديم إقرار الضريبة على القيمة المضافة خلال الشهر التالي من تاريخ انتهاء الفترة الضريبية”
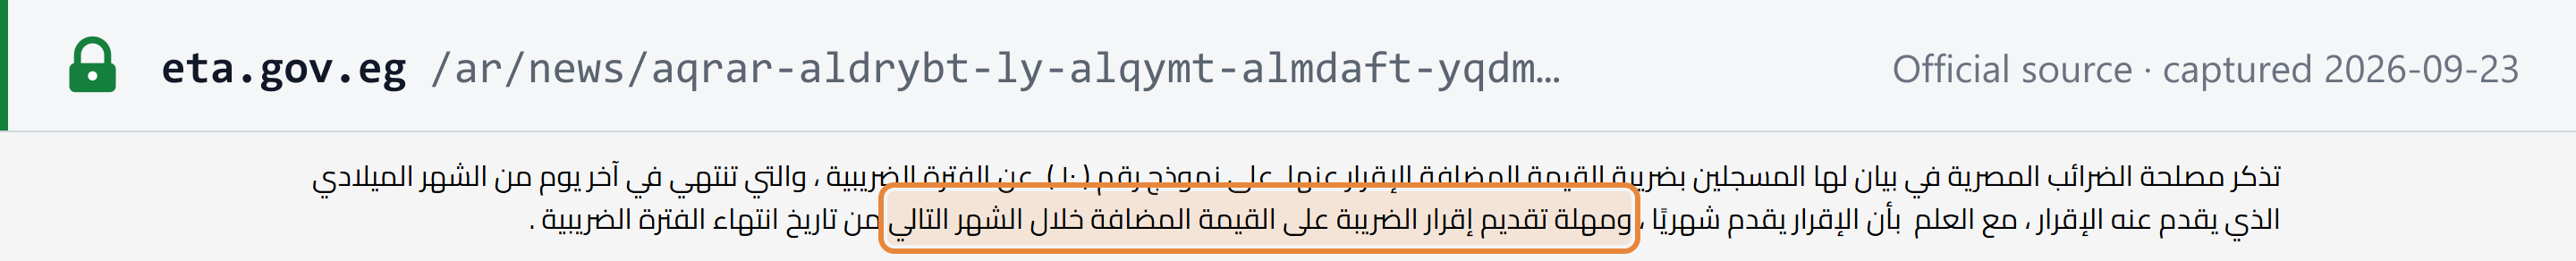 Open full size Captured from Egyptian Tax Authority on 2026-09-23