Estonia compliance calendar

10 recurring Käibemaks (VAT), Aktsiis (excise duty) and Pakendiaktsiis (packaging excise) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Estonia rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing Report / listing Law change takes effect

Dates already include the weekend and public-holiday shift where Estonia applies one — 4 of 10 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Käibedeklaratsioon (KMD) with the KMD INF annex — monthly VAT return

Käibemaks (VAT) · Monthly · return filing

20th of the month after the month ends Verified 2026-10-13
Who files
Every VAT-registered taxable person in Estonia (registration is compulsory once Estonian taxable supplies exceed EUR 40,000 in a calendar year), and limited taxable persons
Notes
File the KMD in e-MTA and pay the VAT by the 20th of the month after each calendar month; a weekend or holiday 20th moves to the next working day, so the November 2026 return is due Monday 21 December. A return is owed every month, even with no sales, and six consecutive missing returns can cost you your VAT registration. The KMD INF annex lists invoices where the month's total with one partner reaches EUR 1,000 before VAT. From 2027 the annex and the EU sales data become part of the return itself, with data-based filing planned from April 2027 — the due date stays the 20th.
Source
Käibemaksuseadus (KMS) — § 27(1) and (2); payment § 38(1) Riigi Teataja (Riigikogu)
See the source text
“Maksustamisperiood on kalendrikuu. Käibedeklaratsioon ja selle lisa (edaspidi koos käibedeklaratsioon) esitatakse maksuhaldurile maksustamisperioodile järgneva kuu 20. kuupäevaks.”
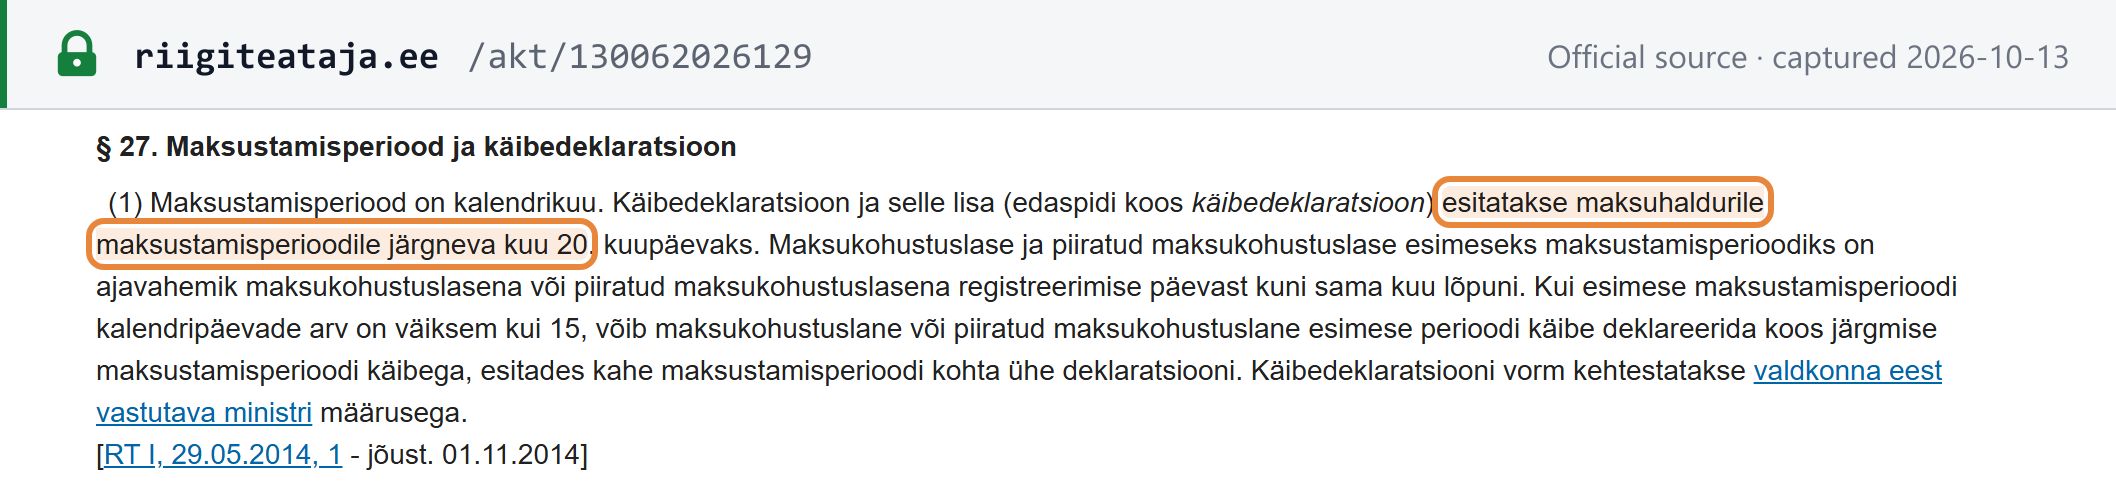
Screenshot of Riigi Teataja (Riigikogu) showing the Käibedeklaratsioon (KMD) with the KMD INF annex — monthly VAT return deadline Open full size Captured from Riigi Teataja (Riigikogu) on 2026-10-13
Ühendusesisese käibe aruanne (VD) — report on intra-Community supply

Käibemaks (VAT) · Monthly · report / listing

20th of the month after the month ends Verified 2026-10-13
Who files
VAT-registered businesses that in the month made intra-EU supplies of goods, resold goods as the intermediary in a triangular transaction, moved call-off stock, or supplied B2B services taxable in another member state under the general rule
Notes
The VD is filed only for months in which you made EU supplies, on the same 20th-of-the-following-month date as the VAT return, moved to the next working day when the 20th is a weekend or holiday. There is no quarterly option. Section 28 of the VAT Act is repealed from 1 January 2027 by the amending act published in RT I, 03.12.2024, 2, and the same information is reported on the VAT return from then on. The repealing act has no transitional rule for the December 2026 report, due 20 January 2027, and the Tax and Customs Board has not said whether it is still owed — if in doubt, file it.
Source
Käibemaksuseadus (KMS) — § 28(1) and (2); repeal by RT I, 03.12.2024, 2 § 1 point 22 and § 3(2) Riigi Teataja (Riigikogu)
See the source text
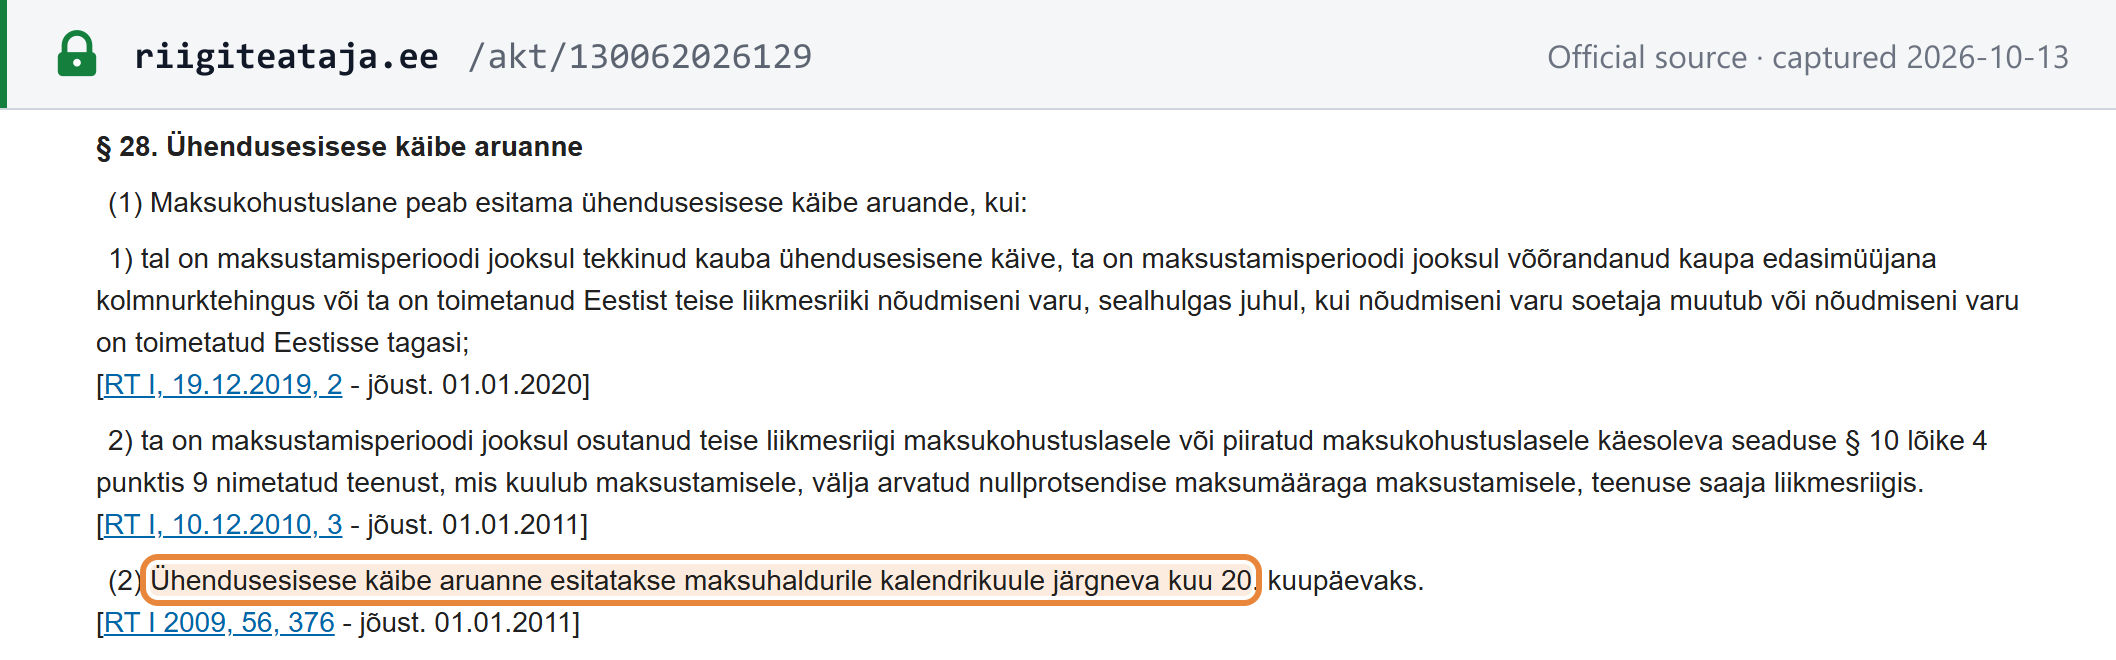
“Ühendusesisese käibe aruanne esitatakse maksuhaldurile kalendrikuule järgneva kuu 20. kuupäevaks.”
Screenshot of Riigi Teataja (Riigikogu) showing the Ühendusesisese käibe aruanne (VD) — report on intra-Community supply deadline Open full size Captured from Riigi Teataja (Riigikogu) on 2026-10-13
OSS VAT return — Union and non-Union schemes

Käibemaks (VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-13
Who files
Businesses using Estonia as their member state of identification for the Union OSS (intra-EU distance sales of goods and B2C services by EU businesses) or the non-Union OSS (B2C services by non-EU businesses)
Notes
OSS returns are filed in e-MTA once a quarter, by the last day of the month after it ends — 30 April, 31 July, 31 October and 31 January — and the VAT is paid by the same day. A return is due for every quarter you are in the scheme, even with no sales. This is an EU-wide deadline that does not move for weekends or holidays: the third quarter of 2026 is due on Saturday 31 October, so file by the Friday.
Source
Maksu- ja Tolliamet — Special schemes: e-commerce and services (OSS VAT return); Käibemaksuseadus § 43(10) Maksu- ja Tolliamet
See the source text
“The tax period of the OSS special scheme is quarterly and the OSS VAT return is submitted by the last day of the month following the quarter.”
Screenshot of Maksu- ja Tolliamet showing the OSS VAT return — Union and non-Union schemes deadline Open full size Captured from Maksu- ja Tolliamet on 2026-10-13

IOSS VAT return — import scheme

Käibemaks (VAT) — Import One Stop Shop · Monthly · return filing

last day of the month after the month ends Verified 2026-10-13
Who files
Businesses or their intermediaries using Estonia as the member state of identification for the Import OSS (B2C distance sales of imported goods in consignments worth up to EUR 150)
Notes
IOSS returns are monthly: the return and the payment are due by the last day of the following month, whether you file yourself or through an intermediary. The date is set EU-wide and stays put when it lands on a weekend — the January 2027 return is due on Sunday 28 February.
Source
Maksu- ja Tolliamet — Special schemes: e-commerce and services (IOSS VAT return); Käibemaksuseadus § 43¹(11) Maksu- ja Tolliamet
See the source text
“The tax period of the IOSS special scheme is a calendar month and the IOSS VAT return is submitted by the last day of the month following each month.”
Screenshot of Maksu- ja Tolliamet showing the IOSS VAT return — import scheme deadline Open full size Captured from Maksu- ja Tolliamet on 2026-10-13

EU cross-border SME scheme — quarterly turnover report

Käibemaks (VAT) — EU SME scheme · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-13
Who files
Estonia-established businesses registered in the EU cross-border SME scheme, using the VAT exemption in other member states
Notes
Small businesses using the EU-wide exemption report each quarter, through the Tax and Customs Board's portal, their turnover in Estonia and in each other member state, by the end of the following month. A quarter with no sales is still reported, as zero. Plan for the last calendar day: 31 October 2026 is a Saturday and 31 January 2027 a Sunday.
Source
Käibemaksuseadus (KMS) — § 19¹(8) Riigi Teataja (Riigikogu)
See the source text
“Erikorda rakendav isik esitab maksuhalduri veebilehel elektroonilise portaali kaudu iga kvartali kohta kvartalile järgneva kuu lõpuks järgmise teabe:”
Screenshot of Riigi Teataja (Riigikogu) showing the EU cross-border SME scheme — quarterly turnover report deadline Open full size Captured from Riigi Teataja (Riigikogu) on 2026-10-13
VAT registration — application within three working days

Käibemaks (VAT) · One-off · registration

within 3 business days of the day the registration obligation arises (taxable supplies in Estonia exceeding EUR 40,000 in the calendar year, or the first taxable supply for a business without an Estonian establishment) Verified 2026-10-13
Who files
Businesses whose Estonian taxable supplies exceed EUR 40,000 in a calendar year; non-established foreign businesses from their first Estonian taxable supply not reverse-charged; EU distance sellers above the EU-wide EUR 10,000 threshold
Notes
Apply within three working days of the day your taxable supplies in Estonia for the year pass EUR 40,000 — or, for a foreign business with no Estonian establishment, of its first taxable supply here. The Tax and Customs Board registers you as from the day the obligation arose, so VAT returns are owed from that month even if the registration decision comes later.
Source
Käibemaksuseadus (KMS) — § 20(1); thresholds § 19(1), (3) and (4) Riigi Teataja (Riigikogu)
See the source text
“Registreerimiskohustuse tekkimise päevast alates kolme tööpäeva jooksul on isik kohustatud esitama maksuhaldurile avalduse enda maksukohustuslasena registreerimiseks.”
Screenshot of Riigi Teataja (Riigikogu) showing the VAT registration — application within three working days deadline Open full size Captured from Riigi Teataja (Riigikogu) on 2026-10-13
Piiratud maksukohustuslasena registreerimine — registration as a limited taxable person

Käibemaks (VAT) · One-off · registration

within 3 business days of the day the limited-taxable-person registration obligation arises (intra-EU acquisitions of goods exceeding EUR 10,000 in the calendar year, or the first reverse-charge service received from a foreign business) Verified 2026-10-14
Who files
Persons in Estonia not registered for VAT — for example non-business legal persons and businesses below the EUR 40,000 threshold — whose intra-EU acquisitions of goods exceed EUR 10,000 in the calendar year, or who receive services from a foreign business not registered in Estonia on which they must account for the VAT
Notes
Organisations and small businesses that are not on the VAT register still have to register as limited taxable persons once their purchases of goods from other EU countries pass EUR 10,000 in a calendar year, or when they buy services from a foreign business and must pay the Estonian VAT on them themselves. The application is due within three working days of that day.
Source
Käibemaksuseadus (KMS) — § 21(3); triggers § 21(1), (2) and (2¹) Riigi Teataja (Riigikogu)
See the source text
“Piiratud maksukohustuslasena registreerimise kohustuse tekkimise päevast arvates kolme tööpäeva jooksul on isik kohustatud esitama maksuhaldurile avalduse enda piiratud maksukohustuslasena registreerimiseks.”
Screenshot of Riigi Teataja (Riigikogu) showing the Piiratud maksukohustuslasena registreerimine — registration as a limited taxable person deadline Open full size Captured from Riigi Teataja (Riigikogu) on 2026-10-13
EU SME scheme — notice of exceeding the EUR 100,000 Union threshold

Käibemaks (VAT) — EU SME scheme · One-off · registration

within 15 business days of EU-wide turnover exceeding EUR 100,000 in the current calendar year Verified 2026-10-13
Who files
Estonia-established businesses in the EU cross-border SME scheme whose EU-wide turnover in the calendar year passes EUR 100,000
Notes
A business that passes EUR 100,000 of EU-wide turnover in the year must tell the Tax and Customs Board through its portal within 15 working days, and report its turnover from the start of the current quarter.
Source
Käibemaksuseadus (KMS) — § 19¹(9) Riigi Teataja (Riigikogu)
See the source text
“teatab erikorda rakendav isik sellest maksuhalduri veebilehel elektroonilise portaali kaudu 15 tööpäeva jooksul alates käibe piirmäära ületamise päevast”
Screenshot of Riigi Teataja (Riigikogu) showing the EU SME scheme — notice of exceeding the EUR 100,000 Union threshold deadline Open full size Captured from Riigi Teataja (Riigikogu) on 2026-10-13
Aktsiisideklaratsioon — monthly excise return (alcohol, tobacco, fuel, natural gas, electricity)

Aktsiis (excise duty) · Monthly · return filing

20th of the month after the month ends Verified 2026-10-13
Who files
Excise warehouse keepers, registered consignees and tax representatives, and payers of excise on solid-fuel heat production, natural gas and electricity
Notes
Warehouse keepers, registered consignees and the other regular excise payers declare and pay each calendar month's excise by the 20th of the next month — the same day as the VAT return — moved to the next working day when the 20th is not one. Certified consignees, distance sellers and some occasional payers work on a shorter clock instead: declaration and payment within five days of the duty arising. The excise-stock movement report is also due on the 20th.
Source
Alkoholi-, tubaka-, kütuse- ja elektriaktsiisi seadus (ATKEAS) — § 25(1)–(3) Riigi Teataja (Riigikogu)
See the source text
“Aktsiisilaopidaja ja registreeritud kaubasaaja on kohustatud esitama Maksu- ja Tolliametile aktsiisideklaratsiooni ja maksma aktsiisi hiljemalt maksustamisperioodile järgneva kalendrikuu 20. päeval.”
Screenshot of Riigi Teataja (Riigikogu) showing the Aktsiisideklaratsioon — monthly excise return (alcohol, tobacco, fuel, natural gas, electricity) deadline Open full size Captured from Riigi Teataja (Riigikogu) on 2026-10-13
Pakendiaktsiisi deklaratsioon — packaging excise return

Pakendiaktsiis (packaging excise) · Quarterly · return filing

15th of the month after the quarter ends Verified 2026-10-13
Who files
Persons liable to packaging excise on packaged goods placed on the Estonian market, other than those who have transferred their packaging obligations to a recovery organisation
Notes
Packaging excise is declared and paid quarterly, by the 15th of the month after the quarter, moving to the next working day when the 15th is not one — 15 January 2028 is a Saturday, so that return is due Monday 17 January. Businesses that have handed their packaging obligations to a recovery organisation declare once a year instead, by 15 January.
Source
Pakendiaktsiisi seadus (PakAS) — § 7(2) and (3) Riigi Teataja (Riigikogu)
See the source text
“aktsiisideklaratsioon esitatakse Maksu- ja Tolliametile maksustamise perioodile järgneva kuu 15. päevaks.”
Screenshot of Riigi Teataja (Riigikogu) showing the Pakendiaktsiisi deklaratsioon — packaging excise return deadline Open full size Captured from Riigi Teataja (Riigikogu) on 2026-10-13
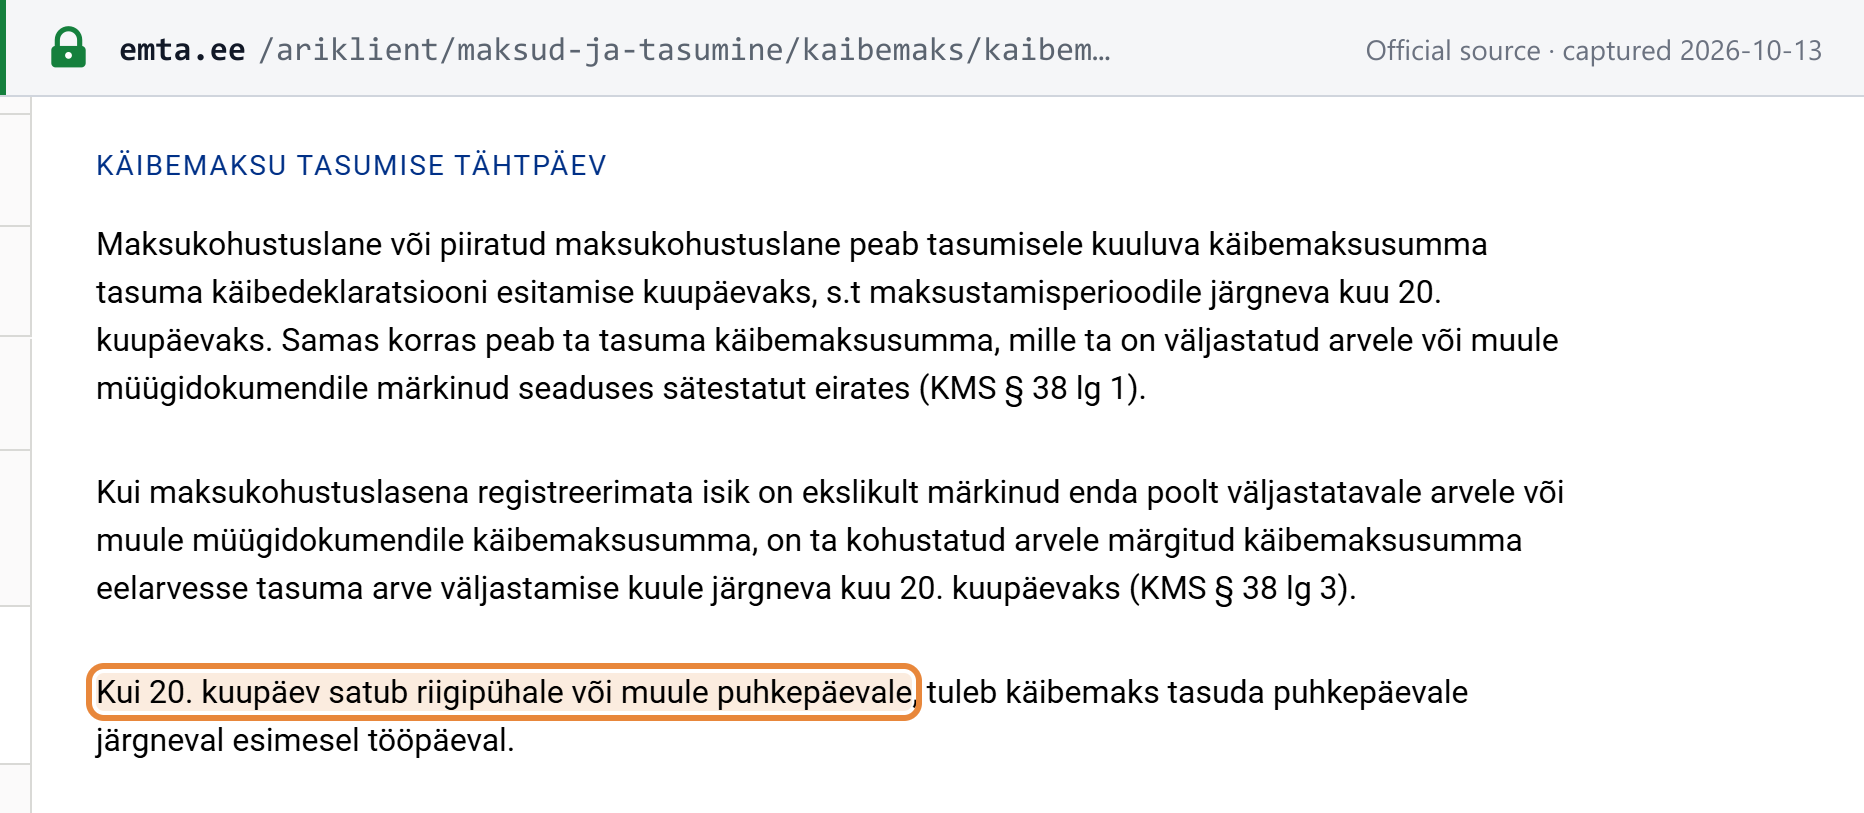
Estonian VAT runs on calendar months: the return (KMD) and the payment are both due on the 20th of the following month, for every registered business, including months with nothing to declare. When the 20th falls on a weekend or a public holiday, the deadline moves to the next working day — the July 2027 return is due Monday 23 August, because 20 August is Restoration of Independence Day. The separate EU sales report (VD) is abolished from 2027, when its data move into the VAT return itself. OSS, IOSS and EU small-business scheme reports are due at the end of the following month and do not move for weekends or holidays. Monthly excise returns share the 20th; packaging excise is quarterly, on the 15th. Gambling tax, payroll taxes and income tax have their own returns and are outside this calendar, which covers indirect taxes only.

“Kui 20. kuupäev satub riigipühale või muule puhkepäevale, tuleb käibemaks tasuda puhkepäevale järgneval esimesel tööpäeval.”
Screenshot of the official source stating the rule that governs Estonia's deadlines
Maksu- ja Tolliamet — Käibemaksu tasumine ja laekumine (Käibemaksu tasumise tähtpäev) — Maksu- ja Tolliamet, captured 2026-10-13

What this calendar does not list

  • Not applicable Annual or reconciliation return — Estonia has no annual VAT return. The VAT Act (KMS § 27) fixes only the monthly return and the special-scheme returns; year-end corrections of partly deductible input VAT are made at the end of each calendar year and reported in a monthly return (KMS § 32(4²) and (6)). Checked against the consolidated text in force 01.10.2026–31.12.2026 on 2026-10-13.
  • Not applicable E-invoicing / e-reporting cycle — Estonia has no e-invoicing or e-reporting mandate that fixes a submission cycle: since 1 July 2025 a business buyer may demand an e-invoice (Accounting Act § 7¹(7)), which is triggered per invoice. The data-based VAT return the Tax and Customs Board introduces from 2027 is the same monthly return, not a separate cadence; the Board points to EU mandatory e-invoicing and near-real-time reporting from 1 July 2030 (VAT in the Digital Age), which Estonia has not yet legislated. Checked 2026-10-13.

New Estonia rules taking effect

Confirmed changes from the weekly scan — each links to its full record with the official source.

About this calendar

Which Estonia tax deadlines does this calendar cover?

10 recurring indirect-tax obligations — Käibemaks (VAT), Aktsiis (excise duty) and Pakendiaktsiis (packaging excise) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-14). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.