Iceland compliance calendar

13 recurring Virðisaukaskattur (VAT), Gistináttaskattur (accommodation tax), Skattur af heitu vatni (environmental and resource tax) and Áfengisgjald (alcohol excise) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Iceland rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing Law change takes effect

Dates already include the weekend and public-holiday shift where Iceland applies one — 8 of 13 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Virðisaukaskattsskýrsla — two-monthly VAT return and payment

Virðisaukaskattur (VAT) · Every 2 months · return filing

5th of the 2nd month after the two-month period ends Verified 2026-10-08
Who files
Every VAT-registered business on the general settlement periods (Jan–Feb, Mar–Apr, May–Jun, Jul–Aug, Sep–Oct, Nov–Dec) — the default for anyone registered above the ISK 2,000,000 twelve-month threshold
Notes
The return and the money are due on the same day, one month and five days after the period closes — January–February on 5 April. There is no later payment date: the payment must have arrived by then, not merely been sent. A return is owed for every period even when nothing was sold; if one is missing Skatturinn estimates the turnover and charges a fee when the real return replaces the estimate. Because 5 April 2026 was Easter Sunday and 6 April Easter Monday, that return was due on 7 April.
Source
Skatturinn — Uppgjör og skil (virðisaukaskattur) Skatturinn
See the source text
“Gjalddagi virðisaukaskatts er einum mánuði og fimm dögum eftir lok hvers almenns uppgjörstímabils. Til dæmis er gjalddagi vegna janúar og febrúar 5. apríl. Ef gjalddaga virðisaukaskatts ber upp á helgidag eða almennan frídag færist hann á næsta virka dag þar á eftir.”
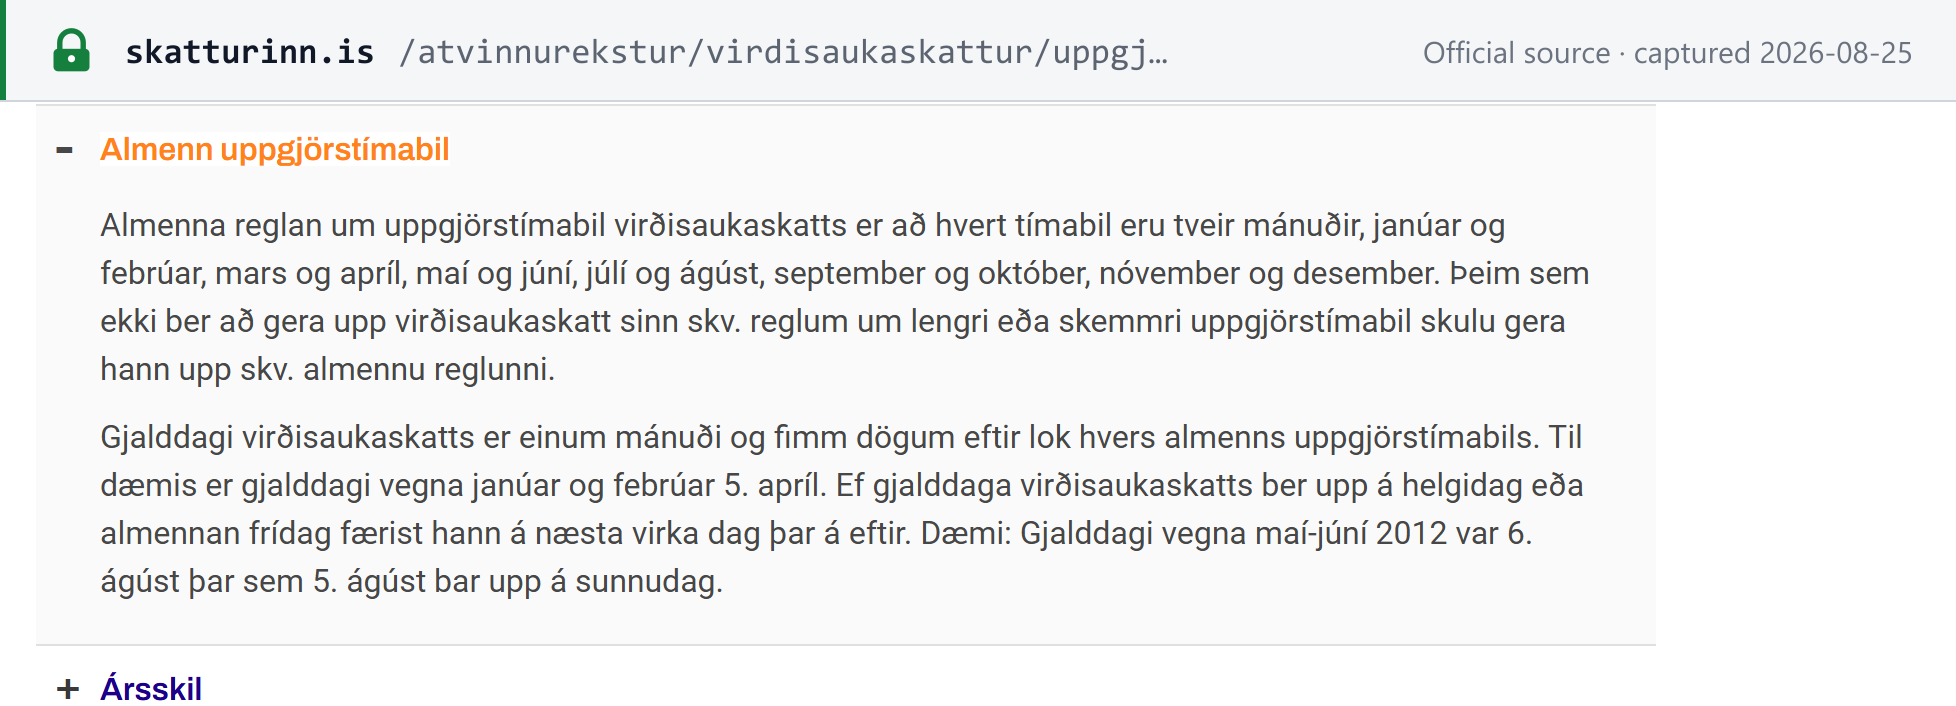
Screenshot of Skatturinn showing the Virðisaukaskattsskýrsla — two-monthly VAT return and payment deadline Open full size Captured from Skatturinn on 2026-08-25
Virðisaukaskattur, ársskil — annual VAT return and payment

Virðisaukaskattur (VAT) · Annually · return filing

5th February each year Verified 2026-10-08
Who files
Businesses registered for the whole previous year with taxable sales under ISK 4,000,000 in a calendar year that applied to Skatturinn before 15 February to use the calendar year as their period; not farmers, monthly filers or agents of foreign businesses
Notes
A small business can settle VAT once a year: the whole calendar year is returned and paid by 5 February of the next year (7 February in 2028, when the 5th is a Saturday). The catch is the ISK 4,000,000 ceiling — once sales in the year reach it, the year to date has to be settled on the due date of the two-month period in which the ceiling was crossed, and two-monthly filing applies from then on. A business that stops trading settles on the next two-monthly due date rather than waiting for February.
Source
Reglugerð nr. 667/1995 um framtal og skil á virðisaukaskatti — 8. gr. 2. mgr. (with 3. gr.) Ísland.is
See the source text
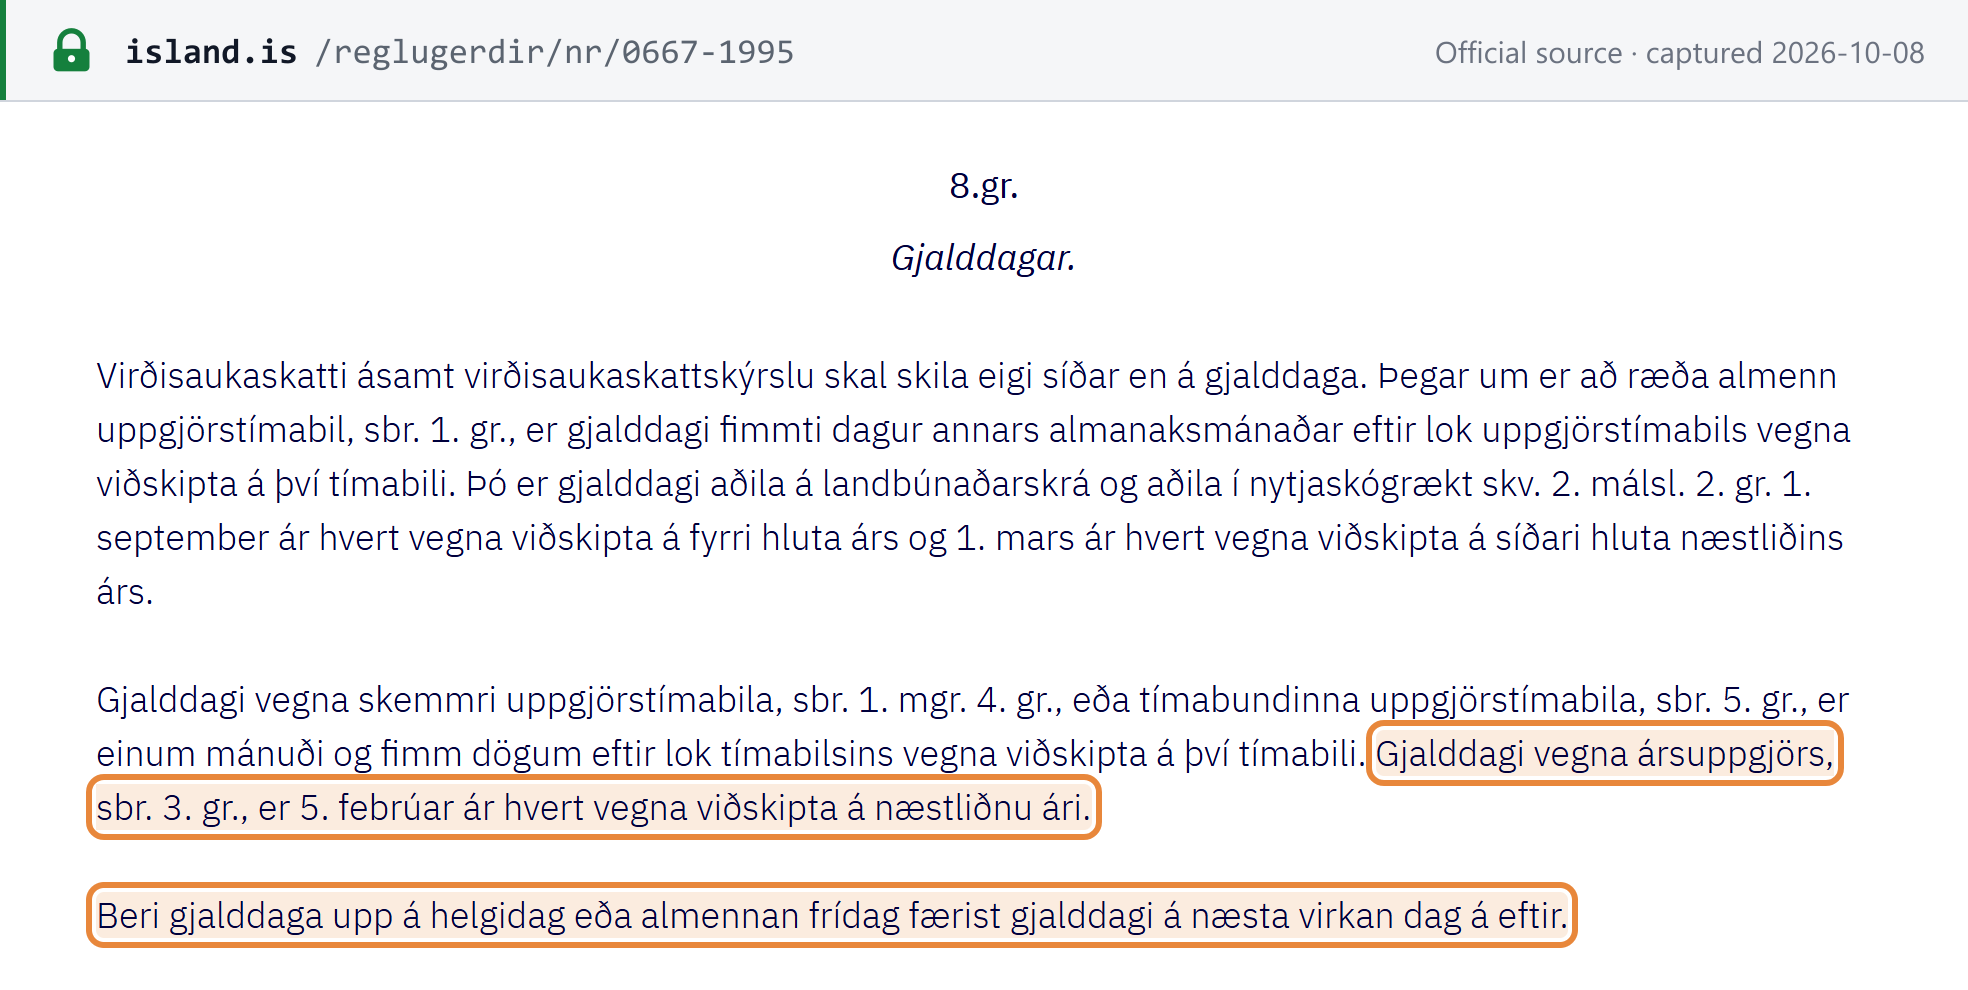
“Gjalddagi vegna skemmri uppgjörstímabila, sbr. 1. mgr. 4. gr., eða tímabundinna uppgjörstímabila, sbr. 5. gr., er einum mánuði og fimm dögum eftir lok tímabilsins vegna viðskipta á því tímabili. Gjalddagi vegna ársuppgjörs, sbr. 3. gr., er 5. febrúar ár hvert vegna viðskipta á næstliðnu ári.”
Screenshot of Ísland.is showing the Virðisaukaskattur, ársskil — annual VAT return and payment deadline Open full size Captured from Ísland.is on 2026-10-08

Virðisaukaskattur, bændaskil — six-monthly VAT for agriculture

Virðisaukaskattur (VAT) · Bi-annually · return filing

1st of the 3rd month after the half-year ends Verified 2026-10-08
Who files
Persons on the agricultural register (landbúnaðarskrá), and commercial forestry with sales under ISK 4,000,000, settling January–June and July–December
Notes
Farmers settle twice a year: January–June by 1 September and July–December by 1 March. Both dates move to the next working day when they land on a weekend — the second half of 2025 was due on Monday 2 March 2026. Farmers may choose ordinary two-monthly periods instead, and can ask for an extra interim settlement when a large refund is owed. Accommodation tax on farm stays follows the same six-monthly dates.
Source
Reglugerð nr. 667/1995 um framtal og skil á virðisaukaskatti — 8. gr. 1. mgr. (with 2. gr.) Ísland.is
See the source text
“Þó er gjalddagi aðila á landbúnaðarskrá og aðila í nytjaskógrækt skv. 2. málsl. 2. gr. 1. september ár hvert vegna viðskipta á fyrri hluta árs og 1. mars ár hvert vegna viðskipta á síðari hluta næstliðins árs.”
Screenshot of Ísland.is showing the Virðisaukaskattur, bændaskil — six-monthly VAT for agriculture deadline Open full size Captured from Ísland.is on 2026-10-08

Virðisaukaskattur, eins mánaðar skil — monthly VAT by permission

Virðisaukaskattur (VAT) · Monthly · return filing

5th of the 2nd month after the month ends Verified 2026-10-08
Who files
Businesses Skatturinn has allowed to use calendar-month periods because their input tax habitually exceeds output tax — typically exporters, or sellers at 11% buying mostly at 24%
Notes
Monthly periods exist so that businesses in a steady refund position get their money sooner. Each month is due one month and five days after it ends — January on 5 March. The request has to reach Skatturinn at least a month before the change, and once granted the monthly period binds for at least two years. Do not confuse this with the special monthly regime, due 15 days after each month, which Skatturinn imposes rather than grants.
Source
Reglugerð nr. 667/1995 um framtal og skil á virðisaukaskatti — 8. gr. 2. mgr. (with 4. gr.) Ísland.is
See the source text
“Gjalddagi vegna skemmri uppgjörstímabila, sbr. 1. mgr. 4. gr., eða tímabundinna uppgjörstímabila, sbr. 5. gr., er einum mánuði og fimm dögum eftir lok tímabilsins vegna viðskipta á því tímabili.”
Screenshot of Ísland.is showing the Virðisaukaskattur, eins mánaðar skil — monthly VAT by permission deadline Open full size Captured from Ísland.is on 2026-10-08

Virðisaukaskattur, sérstök mánaðarskil — special monthly VAT (15 days)

Virðisaukaskattur (VAT) · Monthly · return filing

15th of the month after the month ends Verified 2026-10-08
Who files
Businesses put back on the VAT register after being struck off, and new registrations where the owner, director or a board member was bankrupt within the previous five years — for at least two years
Notes
This regime is imposed, not chosen. A business re-registered after being struck off — for repeated estimated returns, arrears or missing records — or one connected to a recent bankruptcy must settle every calendar month, with the return and payment due just 15 days after the month ends (January on 15 February). It lasts at least two years before the ordinary periods apply again. April 2027 is due on Tuesday 18 May, because 15 May is a Saturday and Whit Monday follows.
Source
Reglugerð nr. 667/1995 um framtal og skil á virðisaukaskatti — 4. gr. a Ísland.is
See the source text
“skal gjalddagi vera 15 dögum eftir að uppgjörstímabili lýkur.”
Screenshot of Ísland.is showing the Virðisaukaskattur, sérstök mánaðarskil — special monthly VAT (15 days) deadline Open full size Captured from Ísland.is on 2026-10-08

VOES declaration — VAT on electronic services by foreign businesses

Virðisaukaskattur (VAT) — VOES simplified registration · Every 2 months · return filing

5th of the 2nd month after the two-month period ends Verified 2026-10-08
Who files
Foreign businesses with no Icelandic establishment selling electronic services, telecoms, subscriptions, broadcasting or VAT-able tourist services to consumers, once those sales exceed ISK 2,000,000 in any twelve-month period
Notes
Non-resident digital sellers declare and pay on the same two-month grid as domestic businesses, by the 5th of the second month after each period. The tax is declared in krónur at the VAT foreign-currency rate on the due date, and no input tax can be deducted through this scheme. A foreign seller of hotel stays or tours to consumers falls under VOES too, not just software and streaming.
Source
Skatturinn — Value Added Tax (English), VOES Skatturinn
See the source text
“The deadline for the submission of declarations and payments is one month and five days after the end of the two month period. When the date falls on a weekend or an Icelandic holiday the due date is the following working day.”
Screenshot of Skatturinn showing the VOES declaration — VAT on electronic services by foreign businesses deadline Open full size Captured from Skatturinn on 2026-10-08

Gistináttaskattur — accommodation tax return and payment

Gistináttaskattur (accommodation tax) · Every 2 months · return filing

5th of the 2nd month after the two-month period ends Verified 2026-10-08
Who files
VAT-registered operators of hotels, guesthouses, campsites and camper pitches, and domestic cruise ships, charging ISK 800 per unit per night (ISK 400 for campsite pitches)
Notes
Accommodation tax rides alongside the VAT return: same two-month periods, same due date, and filing it electronically creates the payment claim in your online bank. Operators who settle VAT annually or as farmers settle accommodation tax on those same dates instead — Skatturinn's own calendar lists a farm-stay settlement on 1 September and an annual one on 5 February.
Source
Skatturinn — Gistináttaskattur Skatturinn
See the source text
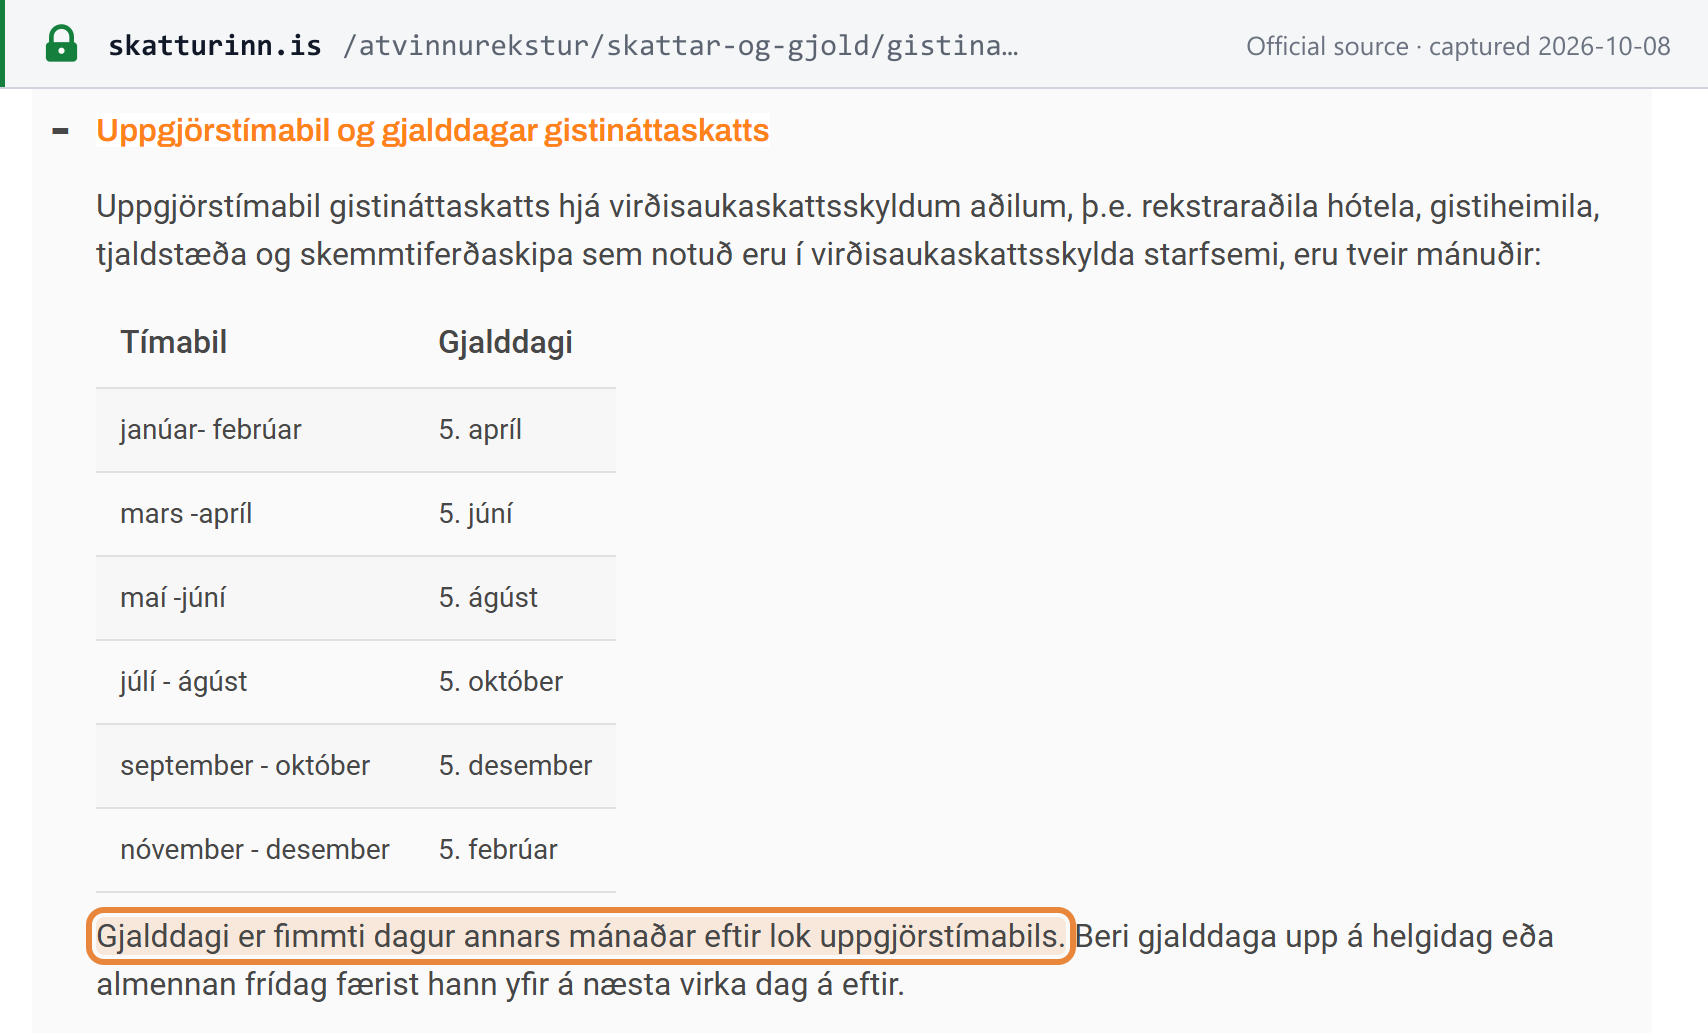
“Gjalddagi er fimmti dagur annars mánaðar eftir lok uppgjörstímabils. Beri gjalddaga upp á helgidag eða almennan frídag færist hann yfir á næsta virka dag á eftir.”
Screenshot of Skatturinn showing the Gistináttaskattur — accommodation tax return and payment deadline Open full size Captured from Skatturinn on 2026-10-08

Skattur af heitu vatni — hot-water tax

Skattur af heitu vatni (environmental and resource tax) · Every 2 months · return filing

5th of the 2nd month after the two-month period ends Verified 2026-10-08
Who files
Sellers of hot water to end users with sales of ISK 500,000 or more a year — in practice geothermal and district-heating utilities
Notes
Heat utilities pay this on the value of the hot water they sell, reporting sales on form RSK 10.51, for the same two-month periods as VAT and on the same day — the 5th of the second month after each period, later if that day is a weekend or holiday.
Source
Skatturinn — Umhverfis- og auðlindaskattar Skatturinn
See the source text
“Uppgjörstímabil skatts af heitu vatni er tveir mánuðir, janúar og febrúar, mars og apríl, maí og júní, júlí og ágúst, september og október, nóvember og desember. Gjalddagi er fimmti dagur annars mánaðar eftir lok uppgjörstímabils.”
Screenshot of Skatturinn showing the Skattur af heitu vatni — hot-water tax deadline Open full size Captured from Skatturinn on 2026-10-08

Áfengisgjald — alcohol duty, monthly settlement

Áfengisgjald (alcohol excise) · Monthly · return filing

25 published dates, 5 Jan 2026 to 4 Jan 2028 Verified 2026-10-08
Who files
Domestic producers of alcoholic beverages, and importers granted payment deferral on alcohol duty, settling each calendar month
Notes
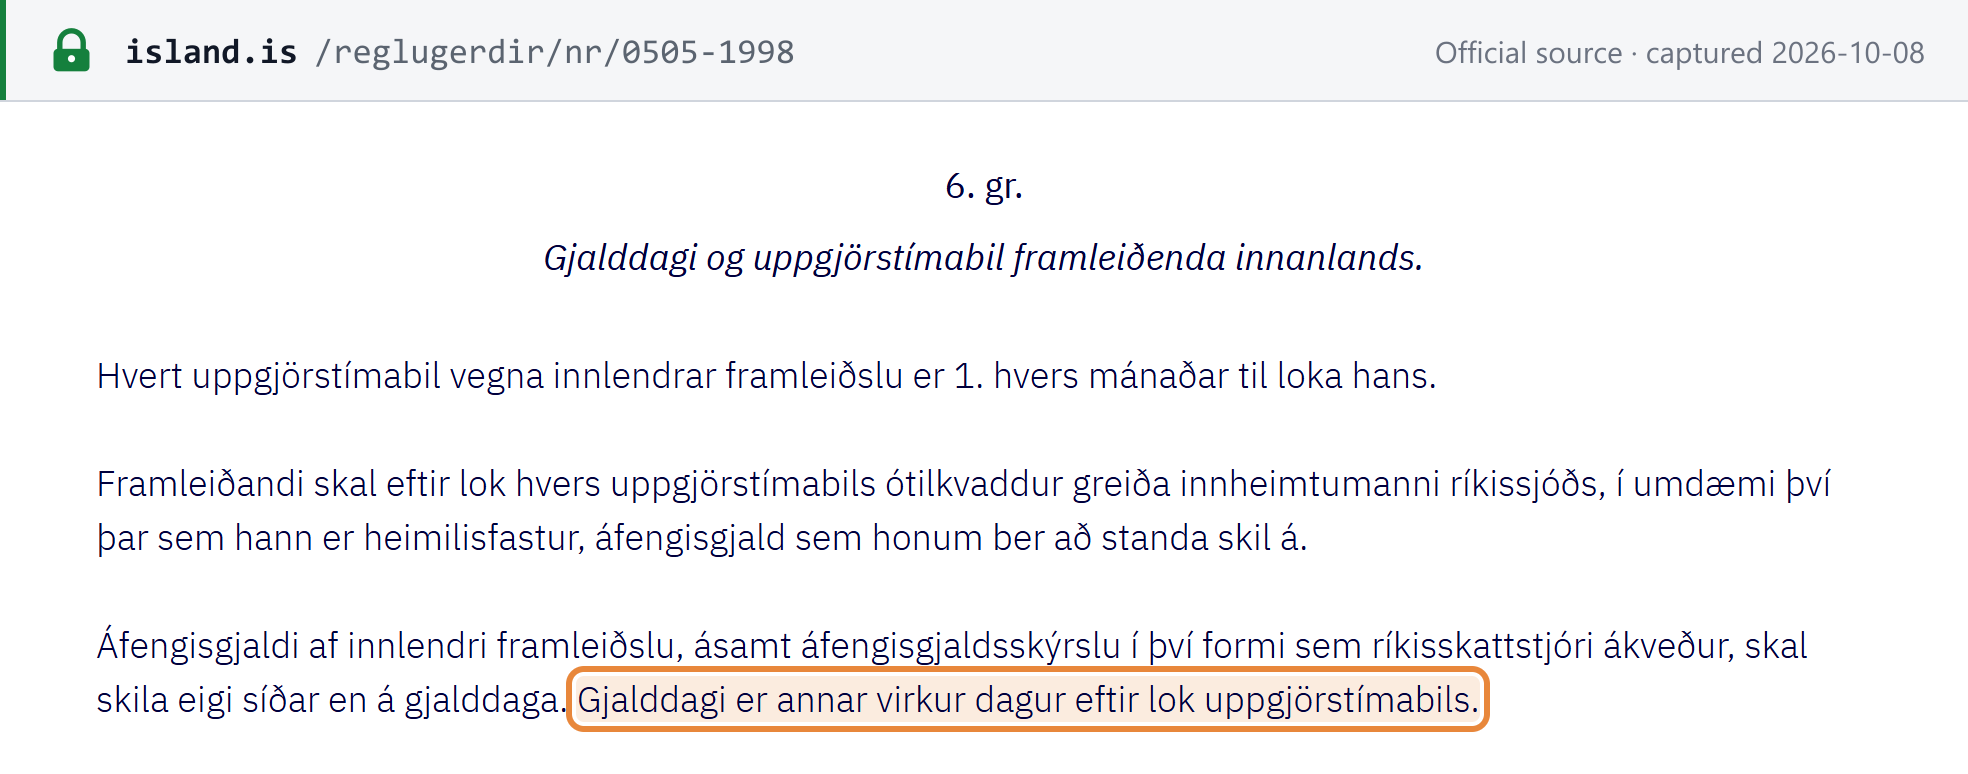
Alcohol duty is due fast: on the second working day after the month ends. Domestic producers file their return and pay by then, and importers granted deferral pay on the same day. These dates are worked out from that rule and Iceland's public holidays rather than copied from Skatturinn's calendar, which prints 4 November for the October 2026 duty when the regulation gives Tuesday 3 November. Tobacco duty is collected and settled by the state monopoly ÁTVR, so no private business files a tobacco return.
Source
Reglugerð nr. 505/1998 um áfengisgjald — 6. gr. Ísland.is
See the source text
“Áfengisgjaldi af innlendri framleiðslu, ásamt áfengisgjaldsskýrslu í því formi sem ríkisskattstjóri ákveður, skal skila eigi síðar en á gjalddaga. Gjalddagi er annar virkur dagur eftir lok uppgjörstímabils.”
Screenshot of Ísland.is showing the Áfengisgjald — alcohol duty, monthly settlement deadline Open full size Captured from Ísland.is on 2026-10-08

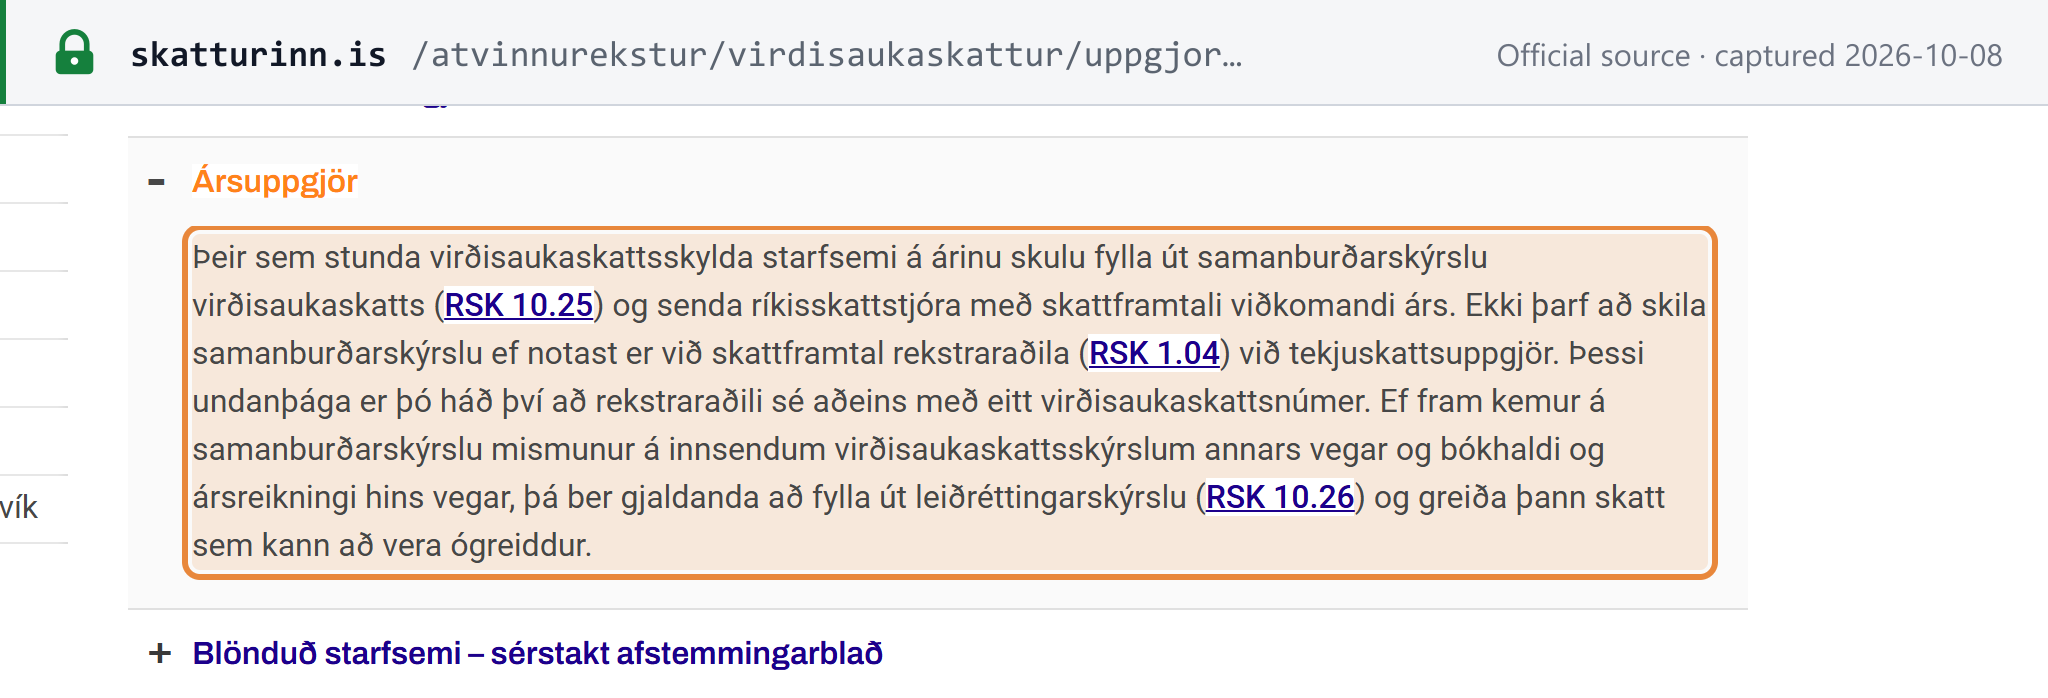
Samanburðarskýrsla virðisaukaskatts (RSK 10.25) — annual VAT comparison statement

Virðisaukaskattur (VAT) · Annually · report / listing

no later than the day of filing that year's income-tax return (skattframtal) Verified 2026-10-08
Who files
Everyone with VAT-liable activity during the year, except operators filing on RSK 1.04 with a single VAT number
Notes
Iceland's year-end VAT check: the comparison statement reconciles the year's VAT returns against the accounts and goes in with the income-tax return, so its deadline is whatever Skatturinn sets for that return each year. If it shows a difference, a correction statement (RSK 10.26) follows and the difference is paid; businesses that apportion input tax between taxable and exempt activity also file RSK 10.27 no later than the tax return.
Source
Skatturinn — Uppgjör og skil (virðisaukaskattur), Ársuppgjör Skatturinn
See the source text
“Þeir sem stunda virðisaukaskattsskylda starfsemi á árinu skulu fylla út samanburðarskýrslu virðisaukaskatts (RSK 10.25) og senda ríkisskattstjóra með skattframtali viðkomandi árs.”
Screenshot of Skatturinn showing the Samanburðarskýrsla virðisaukaskatts (RSK 10.25) — annual VAT comparison statement deadline Open full size Captured from Skatturinn on 2026-10-08

Tilkynning á virðisaukaskattsskrá (RSK 5.02) — VAT registration

Virðisaukaskattur (VAT) · One-off · registration

at least 8 days before the start of VAT-liable activity Verified 2026-10-08
Who files
Anyone starting VAT-liable activity expected to exceed ISK 2,000,000 of taxable sales in a twelve-month period
Notes
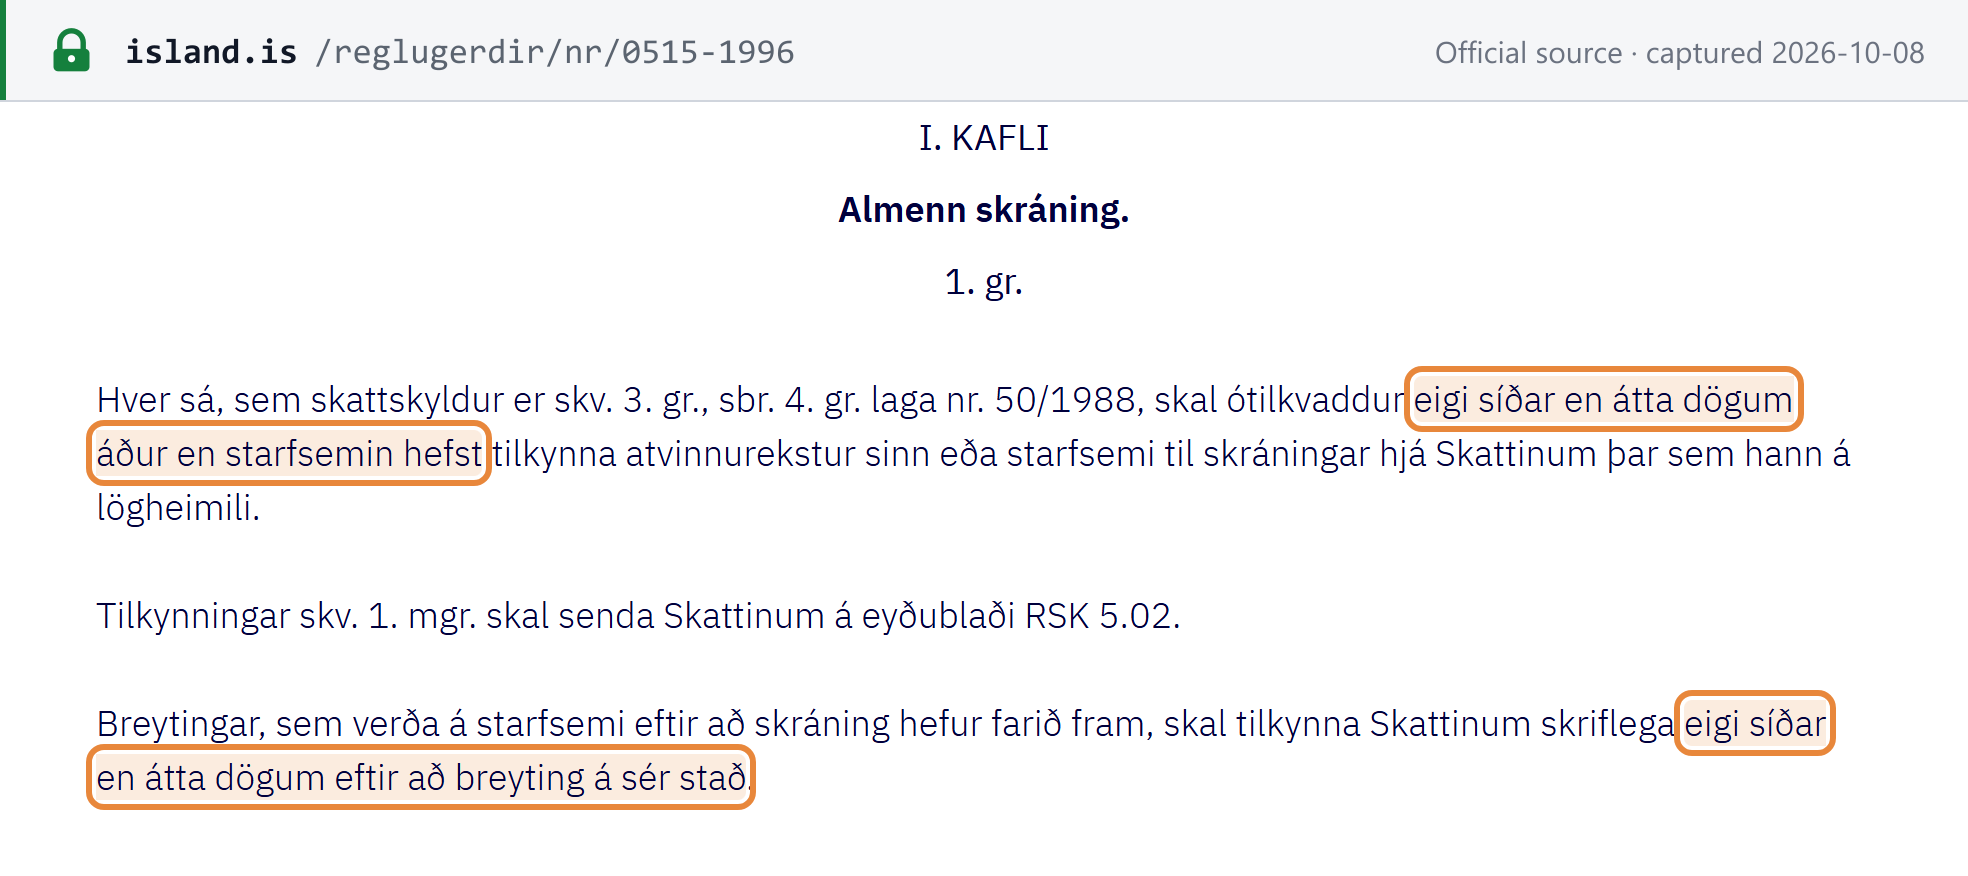
Registration runs ahead of trading, not behind it: notify Skatturinn at least eight days before the activity starts. There is no grace period after crossing the threshold — a business that never notifies is registered by Skatturinn itself.
Source
Reglugerð nr. 515/1996 um skráningu virðisaukaskattsskyldra aðila — 1. gr. Ísland.is
See the source text
“skal ótilkvaddur eigi síðar en átta dögum áður en starfsemin hefst tilkynna atvinnurekstur sinn eða starfsemi til skráningar hjá Skattinum þar sem hann á lögheimili.”
Screenshot of Ísland.is showing the Tilkynning á virðisaukaskattsskrá (RSK 5.02) — VAT registration deadline Open full size Captured from Ísland.is on 2026-10-08

Tilkynning um breytingar — notifying changes to a VAT registration

Virðisaukaskattur (VAT) · One-off · registration

within 8 days of a change in the registered activity Verified 2026-10-08
Who files
Every VAT-registered business whose registered activity changes — a new type of activity, new premises, or a sale or takeover of the business
Notes
Once registered, changes to what the business does or where it does it must be reported in writing within eight days of happening.
Source
Reglugerð nr. 515/1996 um skráningu virðisaukaskattsskyldra aðila — 1. gr. 3. mgr. Ísland.is
See the source text
“Breytingar, sem verða á starfsemi eftir að skráning hefur farið fram, skal tilkynna Skattinum skriflega eigi síðar en átta dögum eftir að breyting á sér stað.”
Screenshot of Ísland.is showing the Tilkynning um breytingar — notifying changes to a VAT registration deadline Open full size Captured from Ísland.is on 2026-10-08

Afskráning (RSK 5.04) — notifying that VAT-liable activity has ceased

Virðisaukaskattur (VAT) · One-off · registration

within 8 days of ceasing VAT-liable activity Verified 2026-10-08
Who files
Every VAT-registered business that stops its VAT-liable activity or no longer meets the registration conditions
Notes
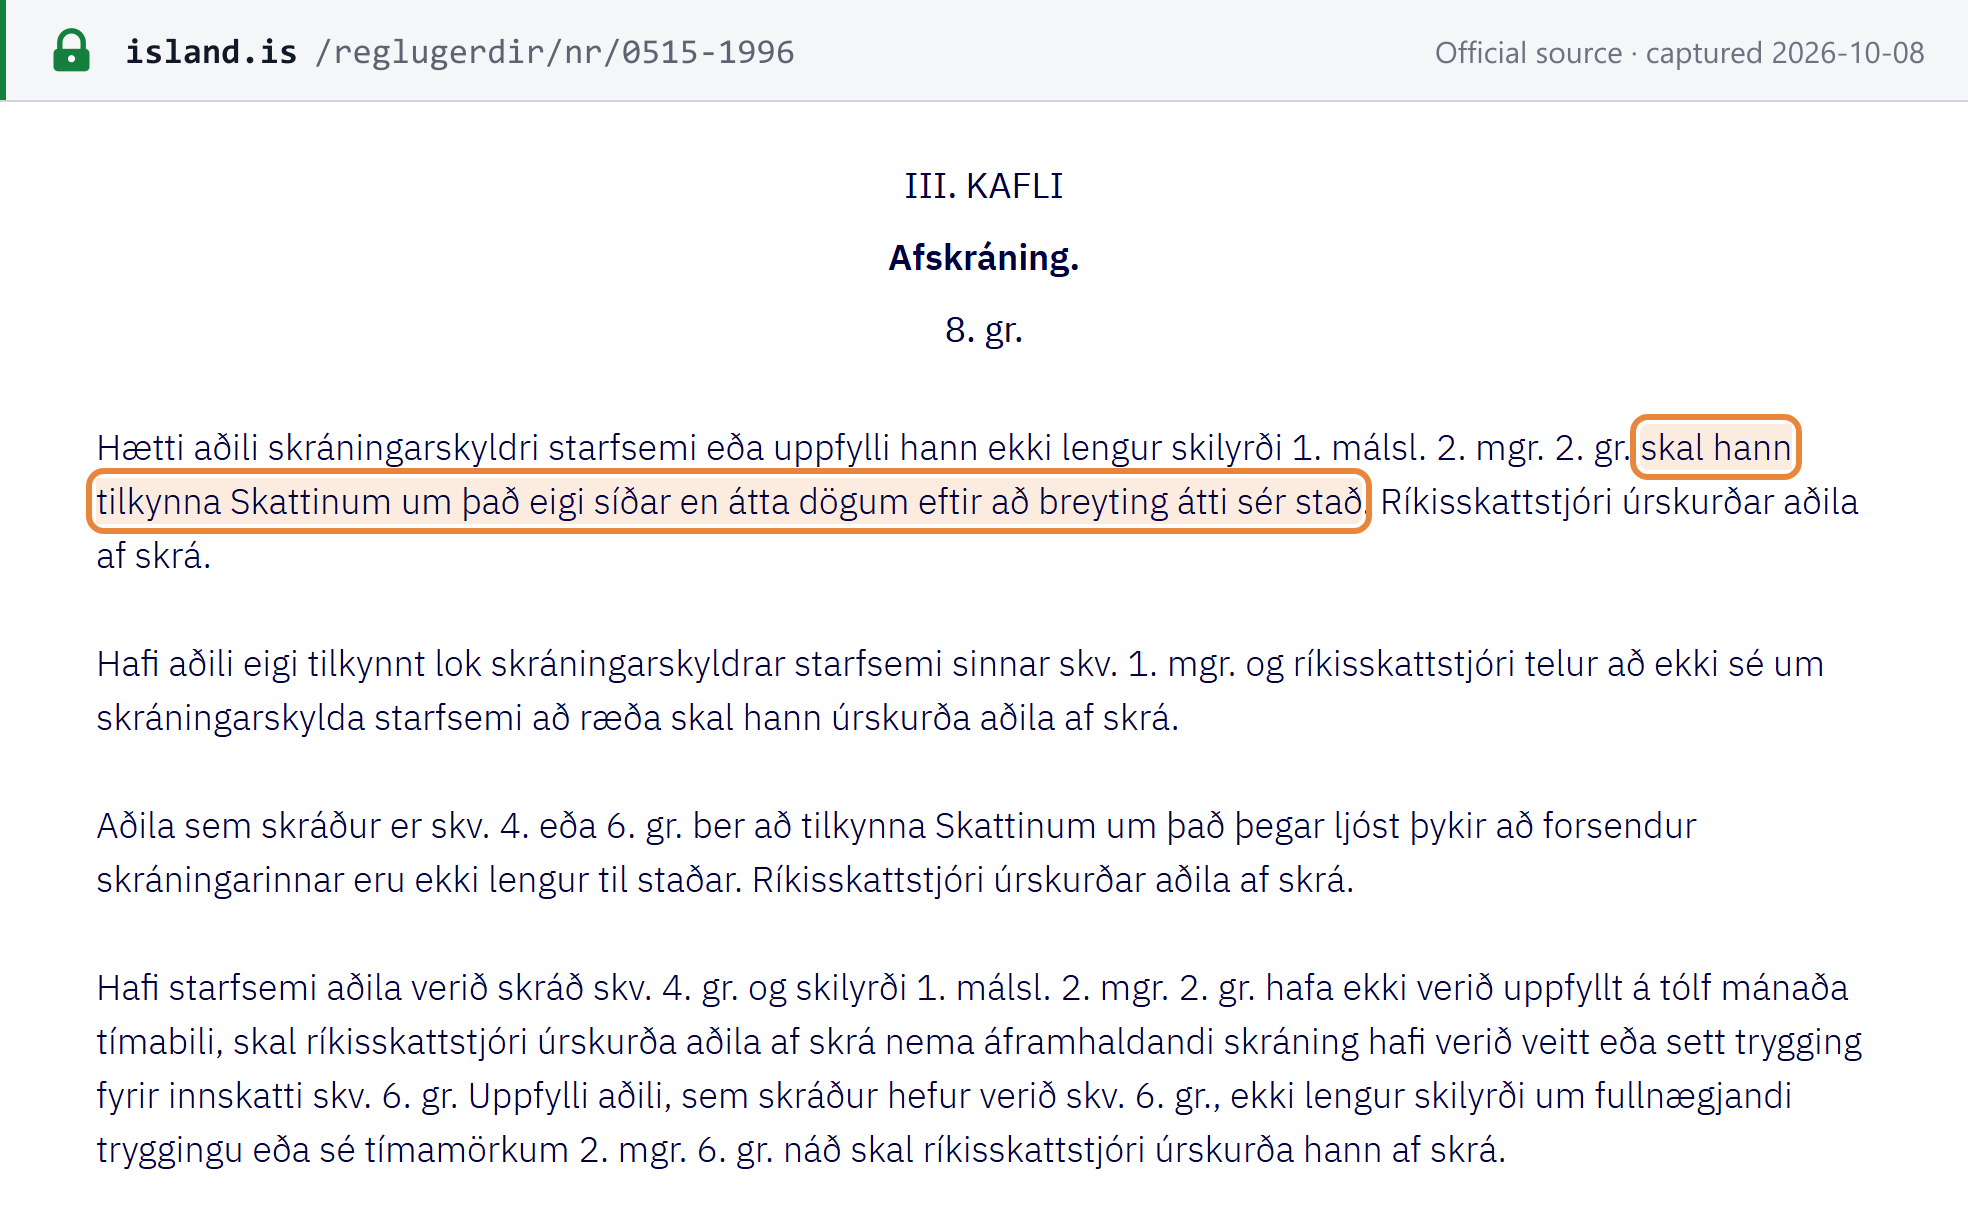
Tell Skatturinn within eight days of stopping. Stock and business assets still held at that point count as taxable sales in the final period, and that final VAT return is still owed. Skatturinn's Icelandic registration page asks for the form eight days before the activity ends, so giving notice in advance is the safe course.
Source
Reglugerð nr. 515/1996 um skráningu virðisaukaskattsskyldra aðila — 8. gr. Ísland.is
See the source text
“Hætti aðili skráningarskyldri starfsemi eða uppfylli hann ekki lengur skilyrði 1. málsl. 2. mgr. 2. gr. skal hann tilkynna Skattinum um það eigi síðar en átta dögum eftir að breyting átti sér stað.”
Screenshot of Ísland.is showing the Afskráning (RSK 5.04) — notifying that VAT-liable activity has ceased deadline Open full size Captured from Ísland.is on 2026-10-08

Iceland is outside the EU VAT area, so there is no EC Sales List, Intrastat or SAF-T. Most VAT-registered businesses settle in two-month periods, with the return and the payment due together on the 5th of the second month after the period ends; smaller filers, farmers, exporters and businesses under special supervision have their own periods. Every VAT due date that falls on a weekend or public holiday moves to the next working day. The recycling fee, drink-container deposit, commercial vehicle excise, customs payment deferral and the cruise-ship levy are not on this calendar yet. Payroll withholding, income tax and the financial-activities tax are outside it.

“Beri gjalddaga upp á helgidag eða almennan frídag færist gjalddagi á næsta virkan dag á eftir.”
Screenshot of the official source stating the rule that governs Iceland's deadlines
Reglugerð nr. 667/1995 um framtal og skil á virðisaukaskatti — 8. gr. (Gjalddagar) — Ísland.is, captured 2026-10-08

What this calendar does not list

  • Not applicable Recapitulative listing — Iceland is not in the EU VAT area and has no recapitulative statement, Intrastat return, SAF-T file or domestic sales/purchases listing. Skatturinn's VAT returns page lists every VAT form (the periodic return, RSK 10.25, 10.26 and 10.27) and no listing, and its published tax calendars for 2020-2026 carry no listing deadline (checked 2026-10-08).
  • Not applicable E-invoicing / e-reporting cycle — Reglugerð 44/2019 only obliges public buyers to receive and process EN 16931 e-invoices (state bodies from 18 April 2019, municipalities from 18 April 2020). It fixes no submission or reporting cadence for suppliers, there is no clearance or reporting platform, and no B2B e-invoicing mandate has been enacted (checked 2026-10-08).
  • Not yet covered Separate payment deadline — Import VAT and duties paid under customs payment deferral ("Greiðslufrestur í tolli, 2 mánuðir") fall due on the 15th after each two-month period per Skatturinn's published calendar (e.g. 15 January, 16 March, 15 May 2026), but the only regulation found stating the rule (reg. 640/1989) is repealed and the current instrument (customs Act / reg. 390/1999) was not fetched; althingi.is is Cloudflare-walled. Not rendered until the current instrument is confirmed (checked 2026-10-08).
  • Not yet covered Periodic return — Several published indirect levy cycles are not yet modelled: úrvinnslugjald (recycling fee on domestic production and imports, two-month periods, due the 28th of the second month after the period, form RSK 10.81), skilagjald (single-use drink-container deposit for domestic producers, two-month periods, due the 28th), vörugjöld af ökutækjum for commercial vehicle importers (monthly, 15th per Skatturinn's calendar) and the cruise-ship innviðagjald (Skatturinn states both 7 and 15 days after departure). Identified by verification on 2026-10-08; each needs its instrument fetched before rows ship.

About this calendar

Which Iceland tax deadlines does this calendar cover?

13 recurring indirect-tax obligations — Virðisaukaskattur (VAT), Gistináttaskattur (accommodation tax), Skattur af heitu vatni (environmental and resource tax) and Áfengisgjald (alcohol excise) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-08). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.