Indonesia compliance calendar

8 recurring PPN PMSE (VAT on cross-border electronic commerce) and PPN (VAT) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Indonesia rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
26
27
28
29
30
31
1
2
3
4
5
6
Payment Other Return filing Law change takes effect

Dates already include the weekend and public-holiday shift where Indonesia applies one — 5 of 8 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

SPT Masa PPN (monthly VAT return, including PPnBM)

PPN (VAT) and PPnBM (luxury-goods sales tax) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-21
Who files
Every business confirmed as a VAT-registered business (Pengusaha Kena Pajak, PKP); registration is compulsory once turnover exceeds IDR 4,800,000,000 in a book year.
Notes
One monthly return carries everything a registered business owes for the month: VAT and luxury-goods sales tax on its supplies, VAT on services and intangibles it used from abroad, and VAT on building on its own account. It is due by the last day of the following month. A return is still required for a month with nothing to declare. The VAT must already be paid when the return goes in. A business that misses three consecutive monthly returns, or six in a calendar year, can have its access to create tax invoices deactivated. When the last day falls on a weekend, national holiday or collective leave day, the return may be filed on the next working day.
Source
Undang-Undang Nomor 8 Tahun 1983 tentang Pajak Pertambahan Nilai, as amended by Undang-Undang Nomor 42 Tahun 2009, Pasal 15A ayat (2) Direktorat Jenderal Pajak (pajak.go.id)
See the source text
“Surat Pemberitahuan Masa Pajak Pertambahan Nilai disampaikan paling lama akhir bulan berikutnya setelah berakhirnya Masa Pajak.”
Screenshot of Direktorat Jenderal Pajak (pajak.go.id) showing the SPT Masa PPN (monthly VAT return, including PPnBM) deadline Open full size Captured from Direktorat Jenderal Pajak (pajak.go.id) on 2026-10-21

Payment of PPN and PPnBM for the tax period

PPN (VAT) and PPnBM (luxury-goods sales tax) · Monthly · payment

last day of the month after the month ends Verified 2026-10-21
Who files
Every VAT-registered business (PKP) with VAT or luxury-goods sales tax owing for the month.
Notes
VAT owed for the month is paid by the last day of the following month, and it has to be paid before the monthly return is submitted, so in practice the payment comes first even though the two share a date. Most withholding taxes are paid by the 15th, but ordinary VAT is not. The exception is VAT on services and intangibles used from abroad and on self-construction, which has its own earlier date. If the last day is a Saturday, Sunday, national holiday or collective leave day, payment may be made on the next working day. Paying late attracts interest from the due date.
Source
Peraturan Menteri Keuangan Nomor 81 Tahun 2024, Pasal 94 ayat (3) huruf e Direktorat Jenderal Pajak (pajak.go.id)
See the source text
“Pajak Pertambahan Nilai atau Pajak Pertambahan Nilai dan Pajak Penjualan atas Barang Mewah yang terutang dalam satu Masa Pajak wajib disetor paling lambat akhir bulan berikutnya setelah Masa Pajak berakhir dan sebelum Surat Pemberitahuan Masa Pajak Pertambahan Nilai disampaikan”
Screenshot of Direktorat Jenderal Pajak (pajak.go.id) showing the Payment of PPN and PPnBM for the tax period deadline Open full size Captured from Direktorat Jenderal Pajak (pajak.go.id) on 2026-10-21

SPT Masa PPN bagi Pemungut PPN dan Pihak Lain (return and payment by appointed VAT collectors)

PPN (VAT) and PPnBM (luxury-goods sales tax) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-21
Who files
Government treasurers, bodies and agencies appointed by the Minister of Finance to collect VAT from their suppliers (Pemungut PPN), and parties in Indonesia appointed to collect VAT on transactions they take part in or facilitate (domestic Pihak Lain).
Notes
A state body or other party appointed to collect VAT from its suppliers pays the tax it withheld into the treasury by the end of the following month, then reports it by that same day. A collector that is itself VAT-registered reports the collected tax inside its own monthly return and must file even in a month with no collections. A collector that is not registered files a separate collector's return and need not file for a month in which it collected nothing. A deadline that lands on a non-working day moves to the next working day.
Source
Peraturan Menteri Keuangan Nomor 81 Tahun 2024, Pasal 94 ayat (3) huruf f and Pasal 171 ayat (14)-(15) Direktorat Jenderal Pajak (pajak.go.id)
See the source text
“Pajak Pertambahan Nilai atau Pajak Pertambahan Nilai dan Pajak Penjualan atas Barang Mewah yang dipungut oleh Pemungut Pajak Pertambahan Nilai dan Pihak Lain wajib disetor paling lambat akhir bulan berikutnya setelah Masa Pajak berakhir dan sebelum Surat Pemberitahuan Masa Pajak Pertambahan Nilai disampaikan.”
Screenshot of Direktorat Jenderal Pajak (pajak.go.id) showing the SPT Masa PPN bagi Pemungut PPN dan Pihak Lain (return and payment by appointed VAT collectors) deadline Open full size Captured from Direktorat Jenderal Pajak (pajak.go.id) on 2026-10-21

SPT Masa PPN PMSE (monthly payment and return by foreign digital-services VAT collectors)

PPN PMSE (VAT on cross-border electronic commerce) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-21
Who files
Foreign sellers, service providers and platforms appointed by DJP as VAT collectors on digital supplies to Indonesia (PMSE Pihak Lain); appointment follows thresholds of IDR 600 million a year or IDR 50 million a month in transaction value, or 12,000 users a year or 1,000 a month.
Notes
Foreign digital sellers and platforms appointed to collect Indonesian VAT pay and report every month, not every quarter. Each month's VAT must reach the collecting bank by the last day of the following month, before the return is filed, and the return is due that same day, even when nothing was collected. Payment may be made in rupiah or US dollars, and the return may be in Indonesian or English. Only Indonesian public holidays and collective leave days, plus weekends, move the date to the next working day; holidays in the collector's own country do not. The duties begin at the start of the month after the appointment decision.
Source
Peraturan Direktur Jenderal Pajak Nomor PER-12/PJ/2025, Pasal 12 and Pasal 13 Direktorat Jenderal Pajak (pajak.go.id)
See the source text
“Pihak Lain sebagaimana dimaksud dalam Pasal 2 ayat (2) wajib melaporkan Pajak Pertambahan Nilai yang telah dipungut sebagaimana dimaksud dalam Pasal 9 ayat (1) dan yang telah disetor sebagaimana dimaksud dalam Pasal 12 ayat (1), paling lambat akhir bulan berikutnya setelah Masa Pajak berakhir, dengan menggunakan Surat Pemberitahuan Masa Pajak Pertambahan Nilai.”
Screenshot of Direktorat Jenderal Pajak (pajak.go.id) showing the SPT Masa PPN PMSE (monthly payment and return by foreign digital-services VAT collectors) deadline Open full size Captured from Direktorat Jenderal Pajak (pajak.go.id) on 2026-10-21

Payment of PPN on imported intangibles and services, and on self-construction (KMS)

PPN (VAT) · Monthly · payment

15th of the month after the month ends Verified 2026-10-21
Who files
Any business or individual using intangible goods or services from outside Indonesia on which no appointed collector has charged VAT, and anyone building on their own account (kegiatan membangun sendiri, KMS), whether or not VAT-registered.
Notes
Two kinds of VAT are due two weeks earlier than the rest: VAT you self-assess on services or intangibles bought from abroad without Indonesian VAT, and VAT on a building you construct for yourself. Both are paid by the 15th of the following month. A registered business still declares them in its month-end return, so leaving them to be paid alongside its other VAT means paying them late. For someone who is not registered, the validated payment itself counts as the report. A 15th that falls on a weekend, national holiday or collective leave day moves to the next working day.
Source
Peraturan Menteri Keuangan Nomor 81 Tahun 2024, Pasal 94 ayat (2) huruf i and j Direktorat Jenderal Pajak (pajak.go.id)
See the source text
“Pembayaran dan penyetoran sebagaimana dimaksud pada ayat (1) wajib dilakukan paling lambat tanggal 15 (lima belas) bulan berikutnya setelah Masa Pajak berakhir meliputi:”
Screenshot of Direktorat Jenderal Pajak (pajak.go.id) showing the Payment of PPN on imported intangibles and services, and on self-construction (KMS) deadline Open full size Captured from Direktorat Jenderal Pajak (pajak.go.id) on 2026-10-21

e-Faktur upload and DJP approval

PPN (VAT) and PPnBM (luxury-goods sales tax) · Monthly · other

20th of the month after the month ends Verified 2026-10-21
Who files
Every VAT-registered business (PKP) issuing electronic tax invoices (e-Faktur) through DJP's e-Faktur module in Coretax.
Notes
Every e-Faktur has to be uploaded to the tax authority and approved by the 20th of the month after the month it was made. One that is not approved is not a tax invoice at all, and the buyer cannot claim its VAT. The deadline has been the 20th since 22 May 2025; guidance that still says the 15th is out of date. Unlike payments and returns, this deadline has no stated weekend or holiday extension, so when the 20th falls on a non-working day, upload by the last working day before it. Separately, a tax invoice is made when the supply happens, and one made more than three months late is void.
Source
Peraturan Direktur Jenderal Pajak Nomor PER-11/PJ/2025, Pasal 44 ayat (1) Direktorat Jenderal Pajak (pajak.go.id)
See the source text
“e-Faktur sebagaimana dimaksud dalam Pasal 40 ayat (2) wajib diunggah (di-upload) ke Direktorat Jenderal Pajak menggunakan modul e-Faktur sebagaimana dimaksud dalam Pasal 40 ayat (3) dan memperoleh persetujuan dari Direktorat Jenderal Pajak, paling lambat tanggal 20 (dua puluh) bulan berikutnya setelah tanggal pembuatan e-Faktur.”
Screenshot of Direktorat Jenderal Pajak (pajak.go.id) showing the e-Faktur upload and DJP approval deadline Open full size Captured from Direktorat Jenderal Pajak (pajak.go.id) on 2026-10-21
Report the business for confirmation as a PKP (VAT registration)

PPN (VAT) · One-off · registration

within 1 month of the end of the month in which cumulative gross turnover for the book year first exceeds IDR 4,800,000,000 Verified 2026-10-21
Who files
Any business whose gross turnover or gross receipts from taxable supplies, counted cumulatively up to a month in the book year, exceed IDR 4,800,000,000.
Notes
Once a business's taxable turnover for the book year passes IDR 4.8 billion, it must apply to be confirmed as a VAT-registered business by the end of the following month. Turnover is counted cumulatively from the start of the book year, so the trigger is the month the running total crosses the line. Registering late does not postpone the tax: the tax office can register a business on its own initiative and assess VAT from the month the threshold was crossed. Businesses below the threshold may register voluntarily.
Source
Peraturan Menteri Keuangan Nomor 197/PMK.03/2013, Pasal 4 Direktorat Jenderal Pajak (pajak.go.id)
See the source text
“dilakukan paling lama akhir bulan berikutnya setelah bulan saat jumlah peredaran bruto dan/ atau penerimaan brutonya melebihi Rp4.800.000.000,00 (empat miliar delapan ratus juta rupiah).”
Screenshot of Direktorat Jenderal Pajak (pajak.go.id) showing the Report the business for confirmation as a PKP (VAT registration) deadline Open full size Captured from Direktorat Jenderal Pajak (pajak.go.id) on 2026-10-21

SPP-TDLN: deposit of VAT collected by appointed payment issuers

PPN (VAT) on cross-border digital transactions · One-off · payment

within 7 days of the date the SPP-TDLN operator confirms the transaction Verified 2026-10-21
Who files
Banks and non-bank payment issuers appointed as Pihak Lain under PMK 49/2026 to collect VAT (11/111 of the price) on cross-border digital purchases on which no appointed foreign collector has charged VAT.
Notes
Since 25 September 2026, VAT on cross-border digital purchases that no foreign collector has taxed can be collected at the point of payment by appointed banks and other payment issuers. An issuer deposits the VAT it collects within 7 calendar days of the date the system operator confirms the transaction, and its data submission and deposit count as its monthly VAT return or part of it. This duty falls on the payment issuers only: foreign merchants whose sales are taxed this way have no filing of their own under it.
Source
Peraturan Menteri Keuangan Nomor 49 Tahun 2026, Pasal 12 ayat (1) Direktorat Jenderal Pajak (pajak.go.id)
See the source text
“Pihak Lain wajib menyetorkan Pajak Pertambahan Nilai yang dipungut melalui Penyelenggara SPP-TDLN paling lama 7 (tujuh) hari terhitung sejak tanggal Penyelenggara SPP-TDLN memberikan konfirmasi sebagaimana dimaksud dalam Pasal 6.”
Captured from Direktorat Jenderal Pajak (pajak.go.id) on 2026-10-21

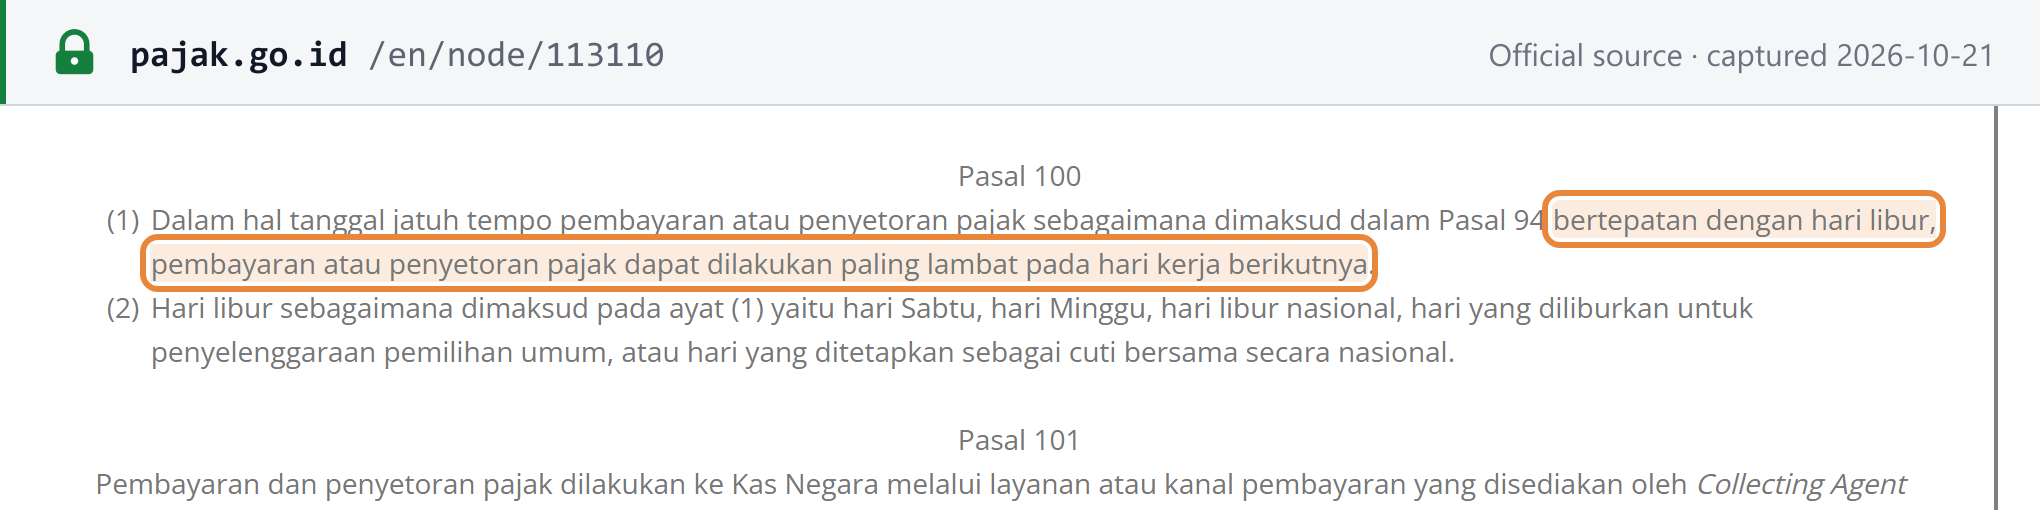
This calendar covers PPN (VAT) and PPnBM (sales tax on luxury goods): the monthly return and payment, the separate collector regimes, the e-Faktur upload deadline and registration. Income-tax withholding, income-tax instalments, stamp duty and carbon tax sit in the same regulation with different dates (mostly the 15th for payment and the 20th for filing) and are outside this calendar. Three things to know. Ordinary VAT is paid and reported by the last day of the following month, but VAT on imported services and on self-construction is paid by the 15th. Payment and return deadlines move to the next working day when they fall on a Saturday, Sunday, national holiday or national collective leave day (cuti bersama); the e-Faktur upload deadline has no such extension. And there is no annual VAT return: every VAT return in Indonesia is monthly. VAT on imports is paid with customs duty at clearance and is not shown here.

“Dalam hal tanggal jatuh tempo pembayaran atau penyetoran pajak sebagaimana dimaksud dalam Pasal 94 bertepatan dengan hari libur, pembayaran atau penyetoran pajak dapat dilakukan paling lambat pada hari kerja berikutnya.”
Screenshot of the official source stating the rule that governs Indonesia's deadlines
Peraturan Menteri Keuangan Nomor 81 Tahun 2024, Pasal 100 — Direktorat Jenderal Pajak (pajak.go.id), captured 2026-10-21

What this calendar does not list

  • Not applicable Annual or reconciliation return — Indonesia has no annual or reconciliation VAT return. PMK 81/2024 art. 162(1) lists every kind of tax return: the annual returns (SPT Tahunan) are for income tax and carbon tax only, and every VAT return is a monthly return (SPT Masa PPN) in one of four variants, for VAT-registered businesses, collectors and foreign digital-services collectors alike (checked 2026-10-21).
  • Not applicable Recapitulative listing — Indonesia has no separate recapitulative or listing return with its own deadline. The lists of exports, domestic output tax, input tax and VAT collected by others are schedules filed with the monthly VAT return (PER-11/PJ/2025 art. 72(1)), and PMK 81/2024 art. 165(1) makes the return and its schedules one inseparable document. Invoice-level data reaches the tax authority through e-Faktur approval, shown here as its own deadline (checked 2026-10-21).

About this calendar

Which Indonesia tax deadlines does this calendar cover?

8 recurring indirect-tax obligations — PPN PMSE (VAT on cross-border electronic commerce) and PPN (VAT) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-21). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.