Liechtenstein compliance calendar

9 recurring Mehrwertsteuer obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Liechtenstein rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing

No obligation here shifts for a weekend or public holiday. Where that is Liechtenstein's own rule the date stands as shown; where a shift exists but is not modelled, the obligation's notes say so. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

MWST-Abrechnung — quarterly VAT return and payment

Mehrwertsteuer (MWST / VAT) · Quarterly · return filing

29th of the 2nd month after the quarter ends — but the 30th in May Verified 2026-10-14
Who files
Every VAT-registered business by default (effective method, and public bodies and associations on flat tax rates), unless it uses the net tax rate method or has been authorised to file monthly or annually; registration threshold CHF 100,000 of worldwide turnover a year
Notes
File the return and pay the VAT by 30 May, 29 August, 29 November and the last day of February. The fourth quarter of 2026 is shown on Sunday 28 February 2027, so file and pay by Friday 26 February; the fourth quarter of 2027 falls on Tuesday 29 February 2028, Shrove Tuesday and a local deadline holiday, so act by Monday 28 February. Businesses without a seat in Liechtenstein must appoint a tax representative based there to handle their filings.
Source
Steuerverwaltung — Newsletter 2/2025 (16 January 2025) (rule: MWSTG Art. 58 Abs. 1, Art. 76 Abs. 1; period: Art. 35 Abs. 1) Steuerverwaltung des Fürstentums Liechtenstein (Internet Archive copy)
See the source text
“Dies bedeutet unter anderem, dass die MWST-Abrechnung für das 4. Quartal 2024 und das 2. Semester 2024 grundsätzlich innert 60 Tagen nach Ende der Abrechnungsperiode und somit bis Ende Februar 2025 im Portal erfasst sein müssten.”
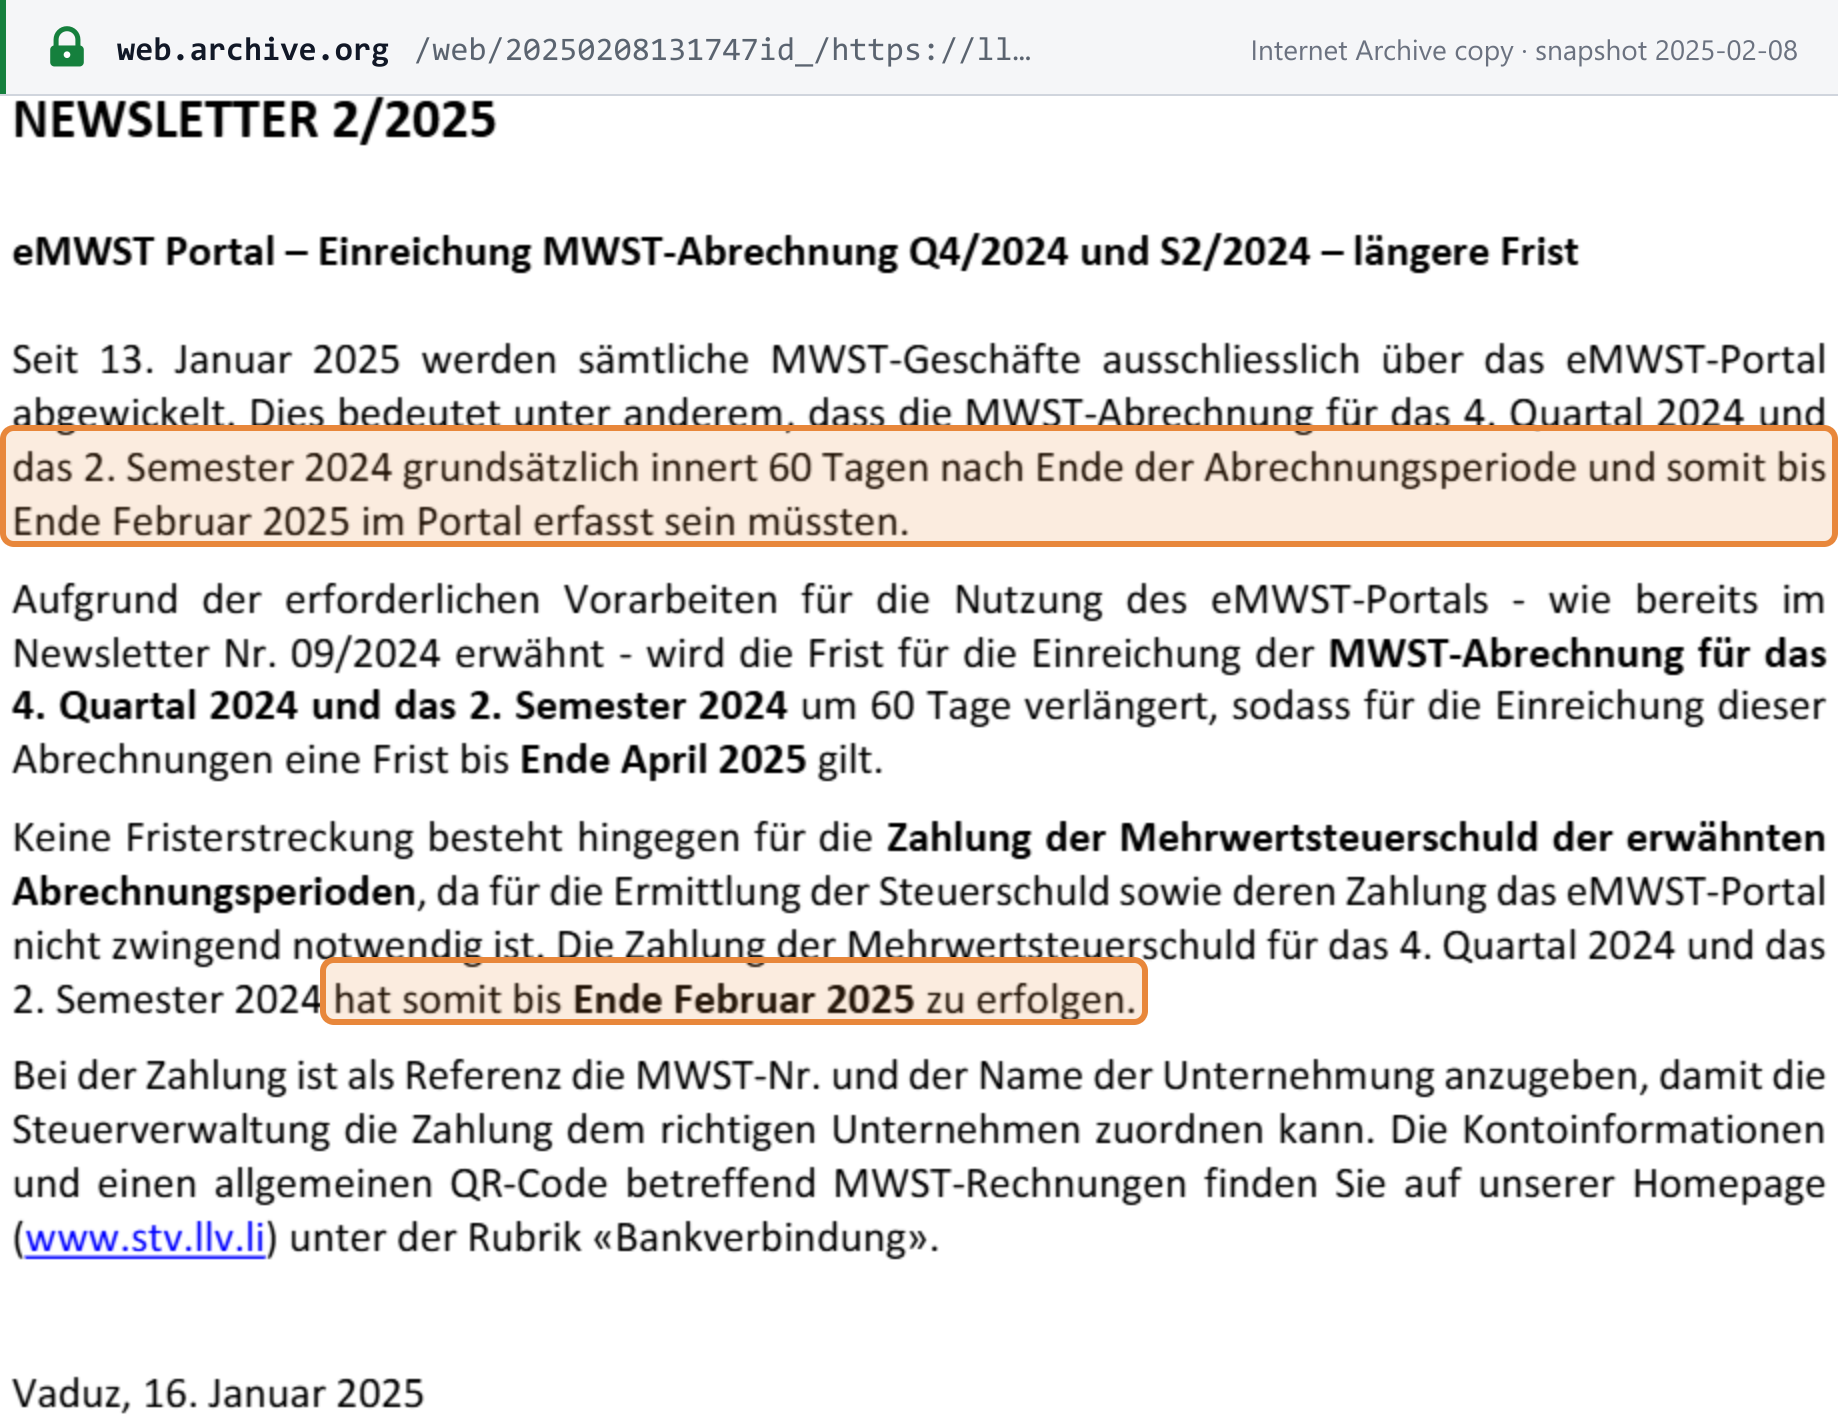
Screenshot of Steuerverwaltung des Fürstentums Liechtenstein (Internet Archive copy) showing the MWST-Abrechnung — quarterly VAT return and payment deadline Open full size Captured from Steuerverwaltung des Fürstentums Liechtenstein (Internet Archive copy) on 2026-10-14
MWST-Abrechnung — half-yearly return and payment (net tax rate method)

Mehrwertsteuer (MWST / VAT) · Bi-annually · return filing

29th of the 2nd month after the half-year ends Verified 2026-10-14
Who files
Businesses authorised to use the net tax rate (Saldosteuersatz) method: taxable turnover of no more than CHF 5,024,000 a year and no more than CHF 108,000 of tax a year at their net tax rate
Notes
Businesses on a net tax rate report twice a year, with return and payment due by 29 August for January to June and by the last day of February for July to December. The tax office has confirmed that payment for the second half is due by the end of February even when filing is extended. The first half of 2027 falls due on a Sunday, so file by Friday 27 August 2027; the second half of 2027 lands on Shrove Tuesday, 29 February 2028, a holiday for deadlines, so pay by Monday the 28th. New registrants must opt in within 60 days of receiving their VAT number and stay on the method for at least one tax year.
Source
Steuerverwaltung — Newsletter 2/2025 (16 January 2025) (rule: MWSTG Art. 35 Abs. 1, Art. 58 Abs. 1, Art. 76 Abs. 1; thresholds: Art. 37 Abs. 1) Steuerverwaltung des Fürstentums Liechtenstein (Internet Archive copy)
See the source text
“Die Zahlung der Mehrwertsteuerschuld für das 4. Quartal 2024 und das 2. Semester 2024 hat somit bis Ende Februar 2025 zu erfolgen.”
Screenshot of Steuerverwaltung des Fürstentums Liechtenstein (Internet Archive copy) showing the MWST-Abrechnung — half-yearly return and payment (net tax rate method) deadline Open full size Captured from Steuerverwaltung des Fürstentums Liechtenstein (Internet Archive copy) on 2026-10-14
MWST-Abrechnung — monthly return and payment (on request)

Mehrwertsteuer (MWST / VAT) · Monthly · return filing

29th of the 2nd month after the month ends — but the 31st in March, and the 30th in May, July, October and December Verified 2026-10-14
Who files
Businesses that regularly reclaim more input VAT than they owe and have applied to the Steuerverwaltung to report monthly
Notes
Monthly reporting is something you apply for, typically to get refunds faster. Each month is due about two months later rather than in the following month: August 2026 by 30 October, September 2026 by 29 November, and December by the last day of February. Where the date is a weekend or public holiday, as with Saturday 30 October 2027 or Shrove Tuesday 29 February 2028, treat the working day before as the last safe day.
Source
Mehrwertsteuergesetz (MWSTG) — Art. 35 Abs. 1a Bst. a (deadline: Art. 58 Abs. 1, Art. 76 Abs. 1) LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein
See the source text
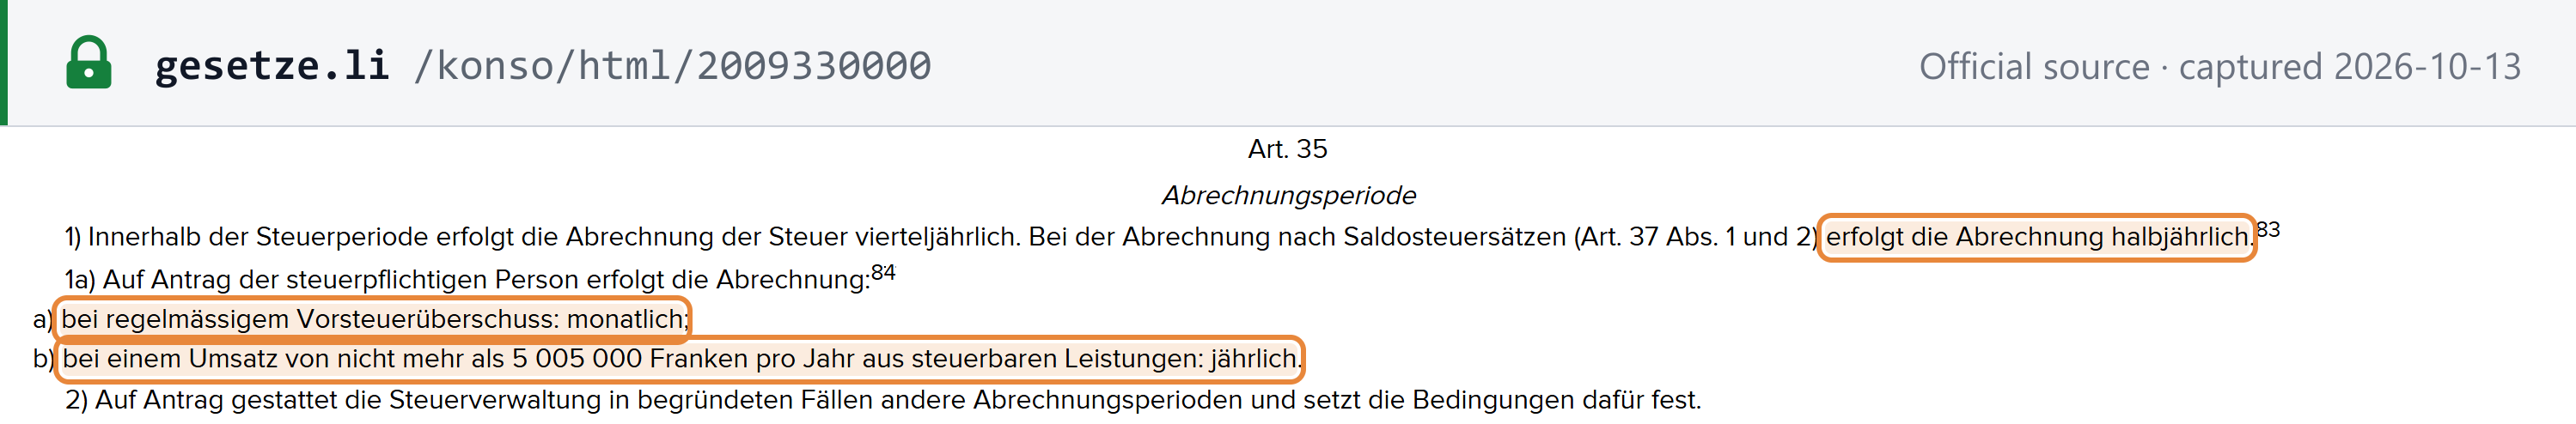
“bei regelmässigem Vorsteuerüberschuss: monatlich;”
Screenshot of LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein showing the MWST-Abrechnung — monthly return and payment (on request) deadline Open full size Captured from LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein on 2026-10-13

Jährliche Abrechnung — annual VAT return and balancing payment (on request)

Mehrwertsteuer (MWST / VAT) · Annually · return filing

29th of the 2nd month after the year ends Verified 2026-10-14
Who files
Businesses with taxable turnover of no more than CHF 5,005,000 a year that have applied to report annually (available since 1 January 2025)
Notes
Smaller businesses can report once a year. The annual return and any balance are due by the end of February: 26 February 2027 is the safe date for 2026, as the 28th is a Sunday, and Monday 28 February 2028 for 2027, since the 29th is Shrove Tuesday. During the year the tax office invoices instalments based on the previous year's tax: three quarters of it in equal parts, due 150, 240 and 330 days into the year (around the end of May, August and November), or one half after 240 days for net-tax-rate users. Late instalments attract interest without a reminder. Apply within 60 days of the start of the year.
Source
Mehrwertsteuergesetz (MWSTG) — Art. 35 Abs. 1a Bst. b, Art. 35a (deadline: Art. 58 Abs. 1, Art. 76 Abs. 1 und 7; instalments: Art. 76a) LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein
See the source text
“bei einem Umsatz von nicht mehr als 5 005 000 Franken pro Jahr aus steuerbaren Leistungen: jährlich.”
Screenshot of LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein showing the Jährliche Abrechnung — annual VAT return and balancing payment (on request) deadline Open full size Captured from LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein on 2026-10-13

Finalisierung — correction of errors found in the annual accounts

Mehrwertsteuer (MWST / VAT) · Annually · return filing

29th August each year Verified 2026-10-13
Who files
Monthly, quarterly and half-yearly filers whose business year is the calendar year and who find errors in their VAT returns while preparing the annual accounts
Notes
Errors you find while closing the year's accounts must be corrected no later than the return for the period containing the 180th day after the business year ends. For a calendar year that is the June, second-quarter or first-half return, so the correction is due by 29 August, filed separately from the ordinary return. The law requires it only when there are errors to correct. With a business year ending on another date the deadline moves accordingly, and annual filers correct in the following year's annual return.
Source
Mehrwertsteuergesetz (MWSTG) — Art. 59 Abs. 1 (separate filing: MWSTV Art. 124) LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein
See the source text
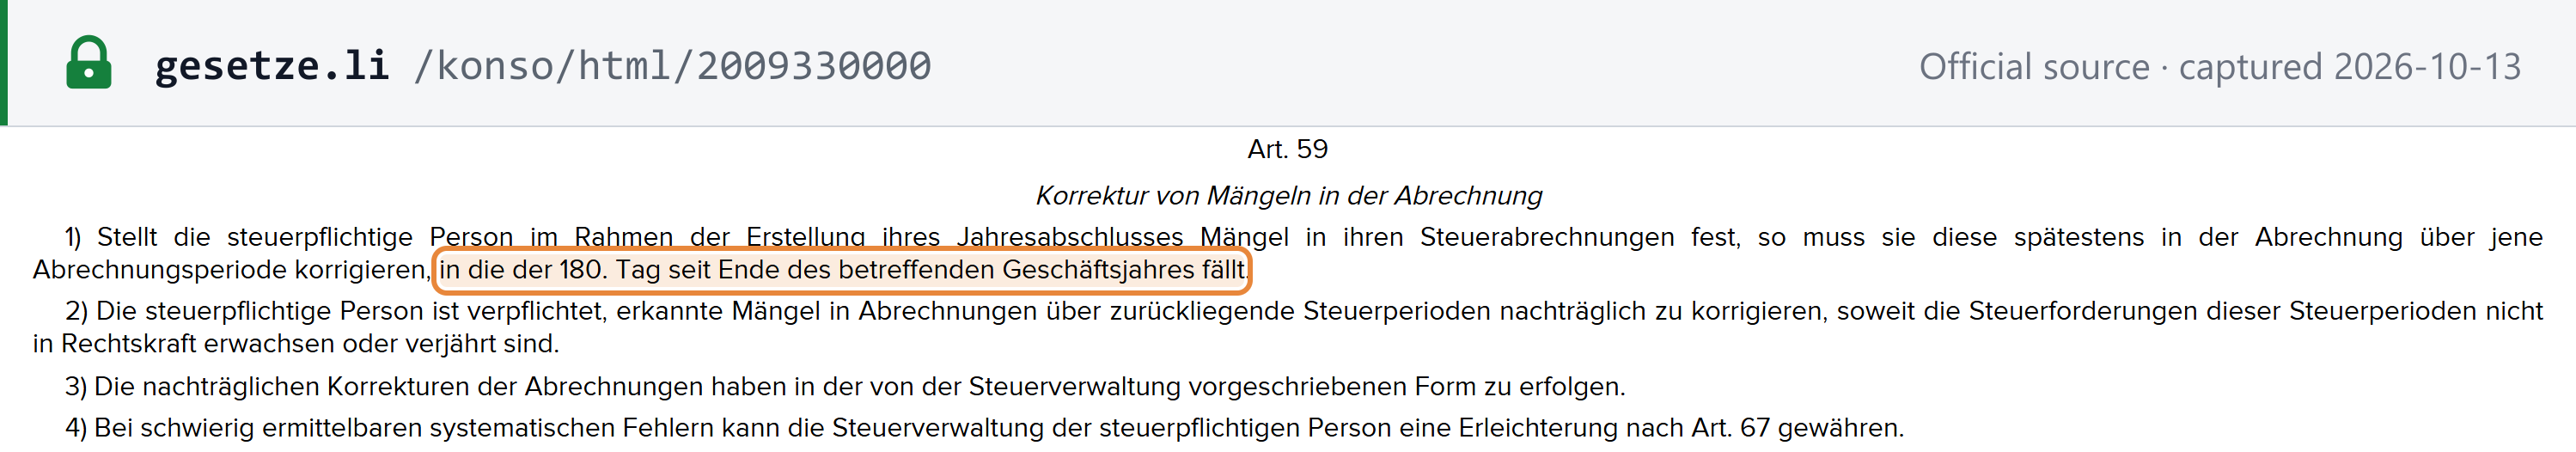
“Stellt die steuerpflichtige Person im Rahmen der Erstellung ihres Jahresabschlusses Mängel in ihren Steuerabrechnungen fest, so muss sie diese spätestens in der Abrechnung über jene Abrechnungsperiode korrigieren, in die der 180. Tag seit Ende des betreffenden Geschäftsjahres fällt.”
Screenshot of LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein showing the Finalisierung — correction of errors found in the annual accounts deadline Open full size Captured from LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein on 2026-10-13

Bezugsteuer — annual registration and declaration for reverse-charge-only liability

Mehrwertsteuer — Bezugsteuer (reverse charge) · Annually · return filing

29th of the 2nd month after the year ends Verified 2026-10-14
Who files
Persons not otherwise registered for VAT who buy more than CHF 10,000 a calendar year of services from foreign suppliers subject to reverse charge — typically holding companies, foundations, banks and insurers
Notes
A business or foundation that is not registered for VAT but buys more than CHF 10,000 of services from abroad in a year owes VAT on them itself. It must register and declare those services within 60 days of the year end, and pay the tax by the same day; the calendar shows the last day of February to stay on the safe side. For 2027 that is 29 February 2028, Shrove Tuesday and a local holiday, so file by Monday 28 February.
Source
Mehrwertsteuergesetz (MWSTG) — Art. 53 Abs. 3 (period: Art. 47 Abs. 2; threshold: Art. 45 Abs. 2 Bst. b) LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein
See the source text
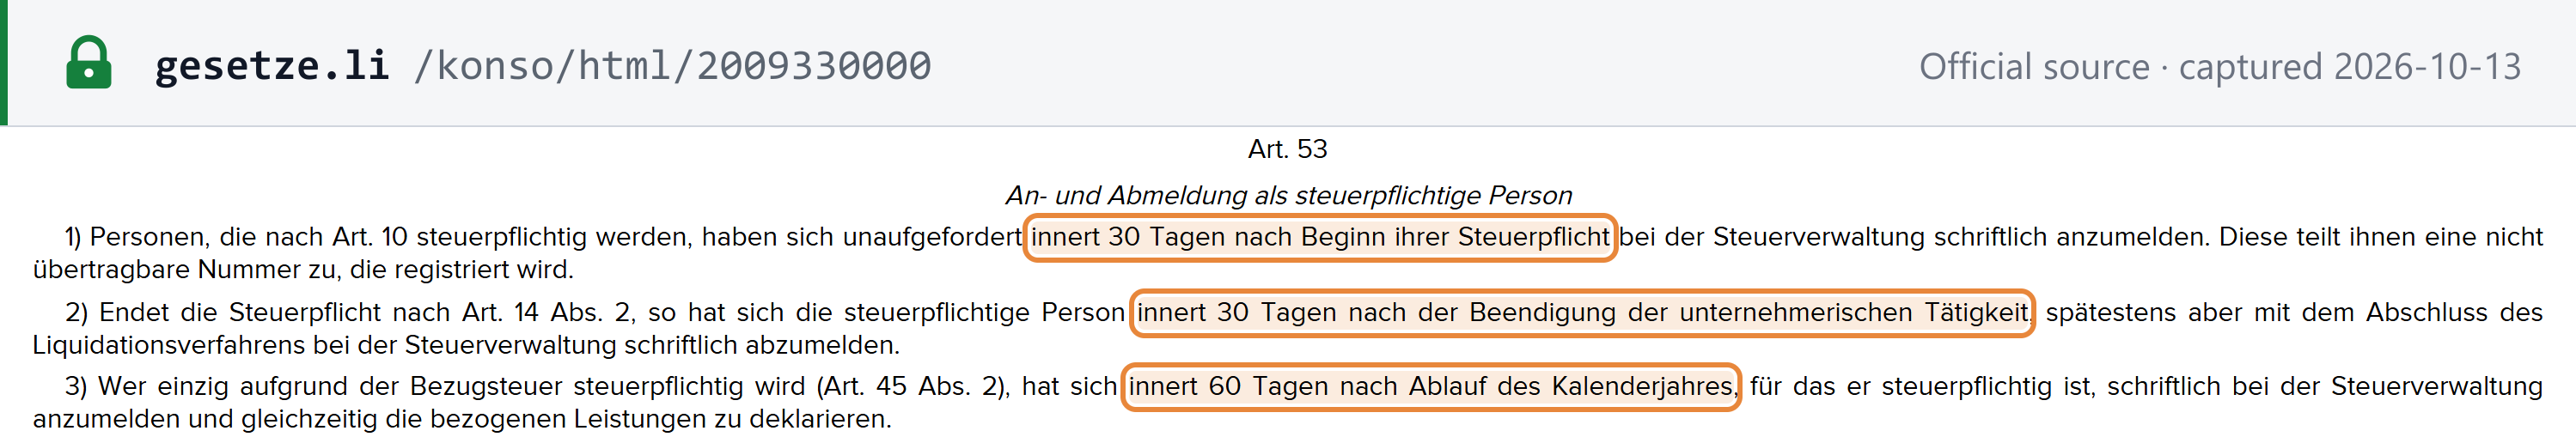
“Wer einzig aufgrund der Bezugsteuer steuerpflichtig wird (Art. 45 Abs. 2), hat sich innert 60 Tagen nach Ablauf des Kalenderjahres, für das er steuerpflichtig ist, schriftlich bei der Steuerverwaltung anzumelden und gleichzeitig die bezogenen Leistungen zu deklarieren.”
Screenshot of LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein showing the Bezugsteuer — annual registration and declaration for reverse-charge-only liability deadline Open full size Captured from LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein on 2026-10-13

Anmeldung — VAT registration

Mehrwertsteuer (MWST / VAT) · One-off · registration

within 30 days of the start of VAT liability Verified 2026-10-14
Who files
Businesses becoming liable to VAT because worldwide turnover reaches CHF 100,000 a year (CHF 250,000 for non-profit sports and cultural associations and charities); the same threshold applies to foreign businesses supplying in Liechtenstein, except foreign providers of telecommunications or electronic services to non-registered customers, who are not exempt
Notes
Register with the Steuerverwaltung, without being asked, within 30 days of becoming liable. Since January 2025 registration and returns go through the eMWST portal, which needs an eID.li login. The exemption for small businesses ends once last year's turnover reached the limit, or as soon as it is clear that a new or expanded business will exceed it within 12 months. Online platforms register in the same way; there is no one-stop-shop scheme.
Source
Mehrwertsteuergesetz (MWSTG) — Art. 10 Abs. 2 (deadline: Art. 53 Abs. 1; start of liability: Art. 14) LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein
See the source text
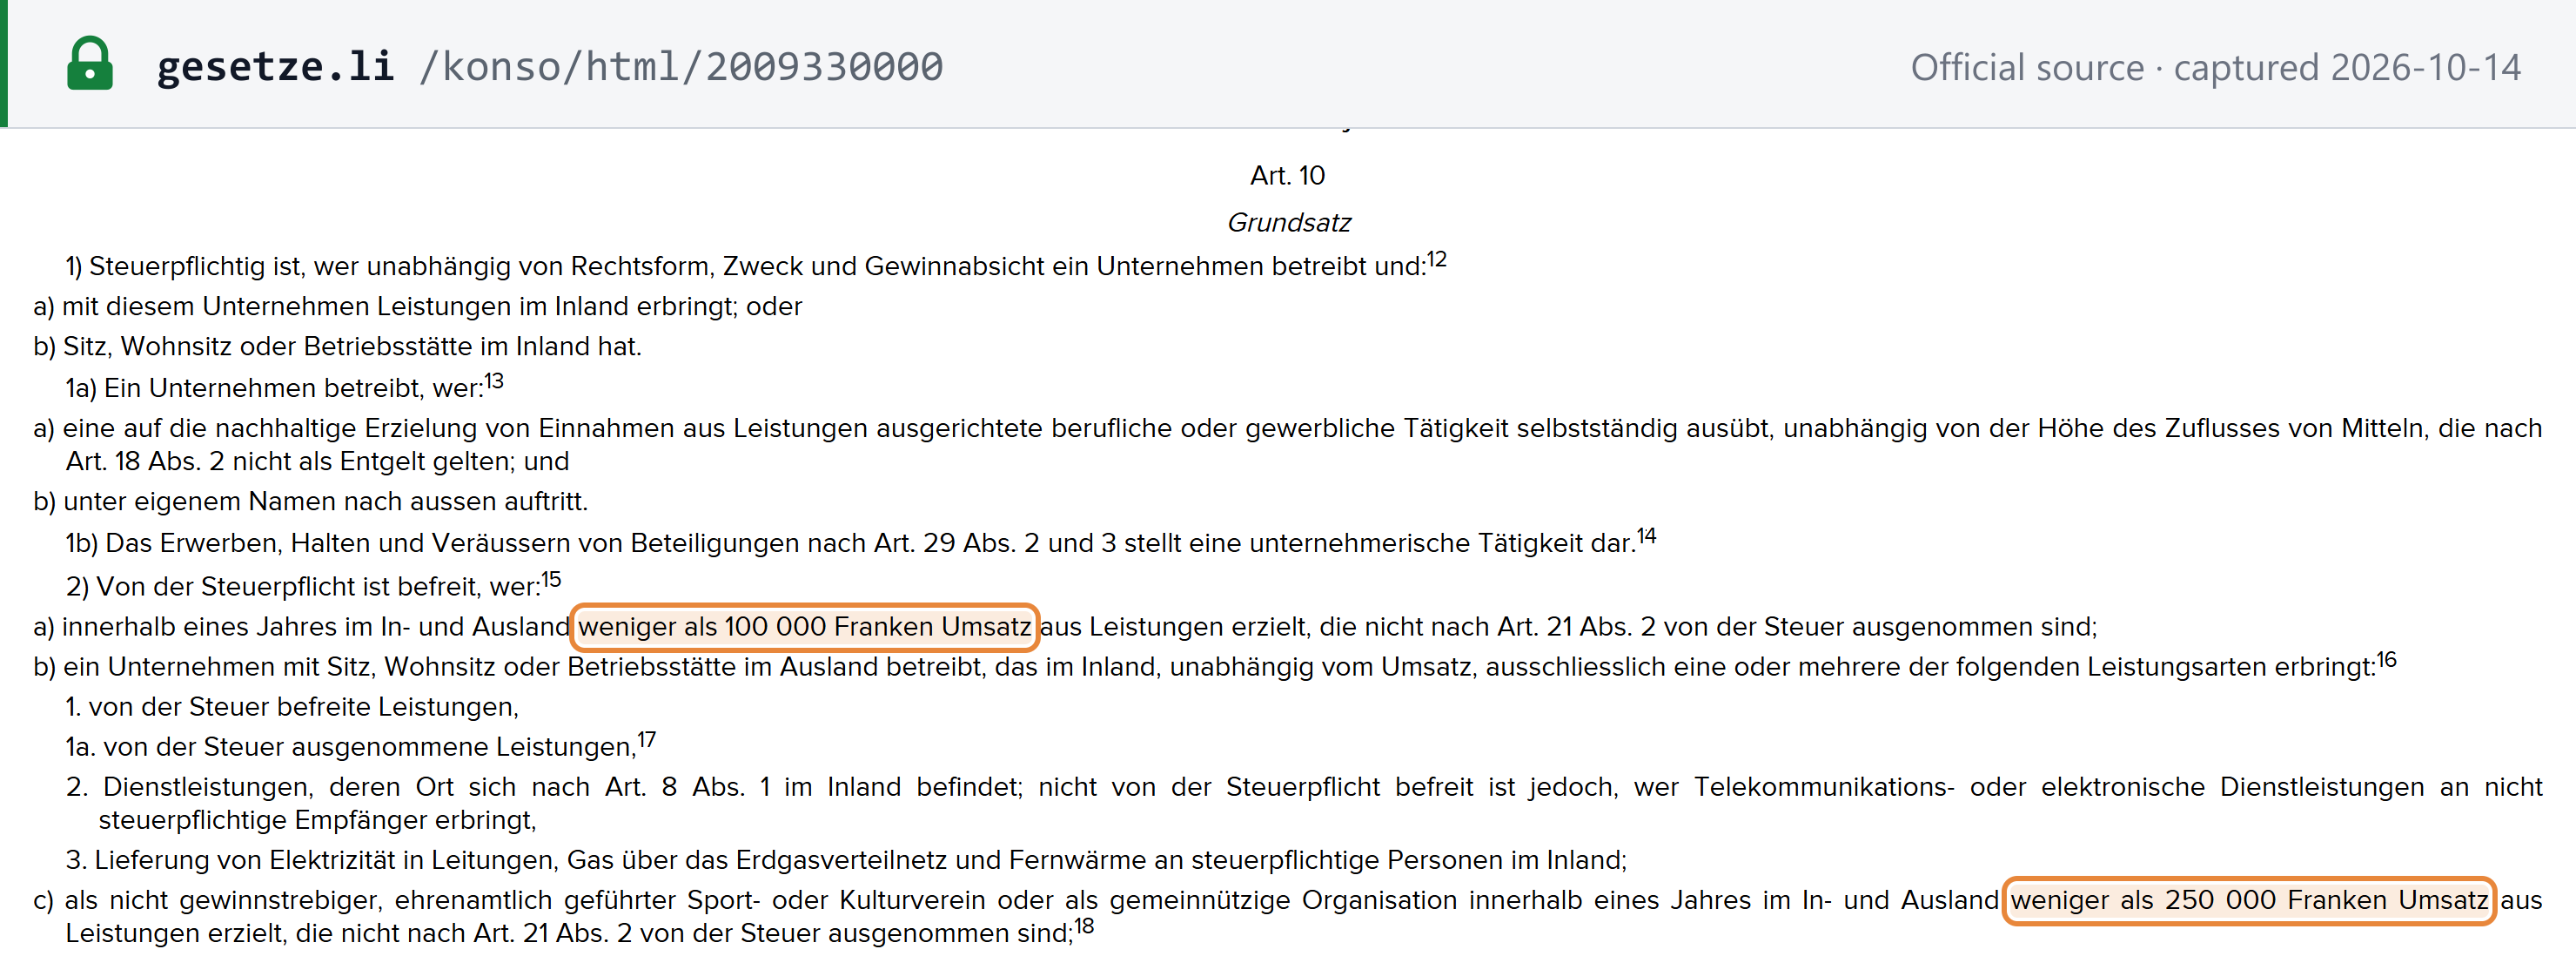
“innerhalb eines Jahres im In- und Ausland weniger als 100 000 Franken Umsatz aus Leistungen erzielt, die nicht nach Art. 21 Abs. 2 von der Steuer ausgenommen sind;”
Screenshot of LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein showing the Anmeldung — VAT registration deadline Open full size Captured from LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein on 2026-10-14

Abmeldung — VAT deregistration

Mehrwertsteuer (MWST / VAT) · One-off · registration

within 30 days of the end of business activity Verified 2026-10-14
Who files
Registered businesses whose liability ends because they cease business activity or are liquidated; and businesses whose turnover falls below the CHF 100,000 (or CHF 250,000) threshold and is expected to stay below it, which must deregister, at the earliest with effect from the end of that tax period (staying registered counts as opting to remain liable)
Notes
Deregister within 30 days of ending your business activity, and in any case no later than the close of a liquidation. A business that stays trading but drops below the registration threshold, and expects to stay below it, must also deregister; that takes effect at the end of the tax year at the earliest. Deregistering does not end your filing duties: a final return is still due for the last period.
Source
Mehrwertsteuergesetz (MWSTG) — Art. 53 Abs. 2 (end of liability: Art. 14 Abs. 2; turnover below threshold: Art. 14 Abs. 5) LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein
See the source text
“Endet die Steuerpflicht nach Art. 14 Abs. 2, so hat sich die steuerpflichtige Person innert 30 Tagen nach der Beendigung der unternehmerischen Tätigkeit, spätestens aber mit dem Abschluss des Liquidationsverfahrens bei der Steuerverwaltung schriftlich abzumelden.”
Screenshot of LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein showing the Abmeldung — VAT deregistration deadline Open full size Captured from LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein on 2026-10-13

Final VAT return on end of liability

Mehrwertsteuer (MWST / VAT) · One-off · return filing

within 60 days of the end of VAT liability Verified 2026-10-14
Who files
Every business whose VAT liability ends
Notes
When your liability ends, the usual 60 days for the last return run from the day it ended rather than from the end of the quarter, so the final return can fall due earlier than the calendar suggests. Pay any VAT on it by the same date to be safe.
Source
Mehrwertsteuergesetz (MWSTG) — Art. 58 Abs. 2 (payment: Art. 76 Abs. 1) LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein
See the source text
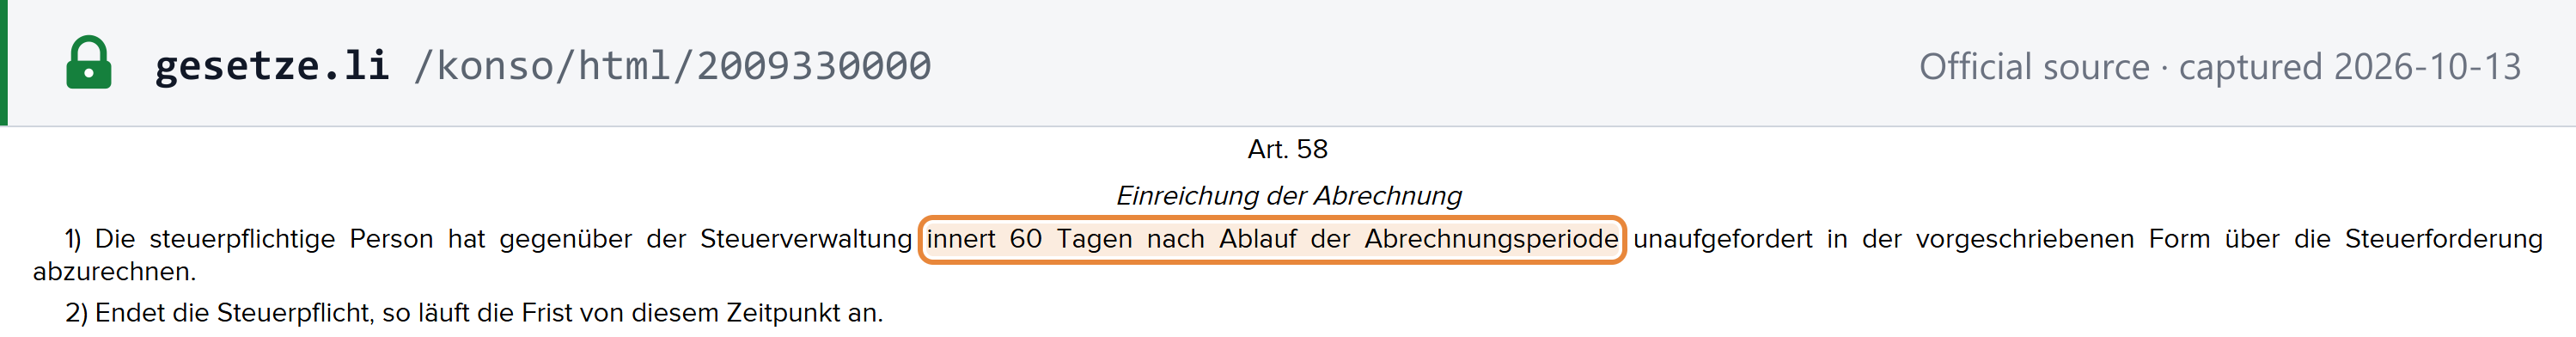
“Endet die Steuerpflicht, so läuft die Frist von diesem Zeitpunkt an.”
Screenshot of LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein showing the Final VAT return on end of liability deadline Open full size Captured from LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein on 2026-10-13

Liechtenstein has its own VAT law, closely modelled on Switzerland's under a 1994 treaty that makes the two countries one VAT area. It is in the EEA but outside the EU VAT area, so there is no EC Sales List, no OSS and no IOSS; foreign sellers register and file the ordinary return. The law gives 60 days after the period ends for both the return and the payment. The tax office describes the same deadline as the end of the second month after the period, which is a day or two later for most quarters but earlier for periods ending in December. The calendar shows whichever comes first: 30 May, 29 August and 29 November, and the last day of February for the final quarter. Most businesses file quarterly; net-tax-rate users file half-yearly, and others can ask to file monthly or once a year. Liechtenstein procedural law may carry a deadline that ends on a Saturday, Sunday or holiday over to the next working day, but the tax office has not been found to say so for VAT. When a date shown here is not a working day, file and pay by the working day before it to be safe. Liechtenstein has more such holidays than its neighbours, including 2 January, Candlemas, Shrove Tuesday and 24 and 31 December. Import VAT and the excise duties on mineral oil, tobacco, beer and spirits are Swiss federal taxes collected by the Swiss authorities under the customs treaty, and follow the Swiss calendar rather than this one.

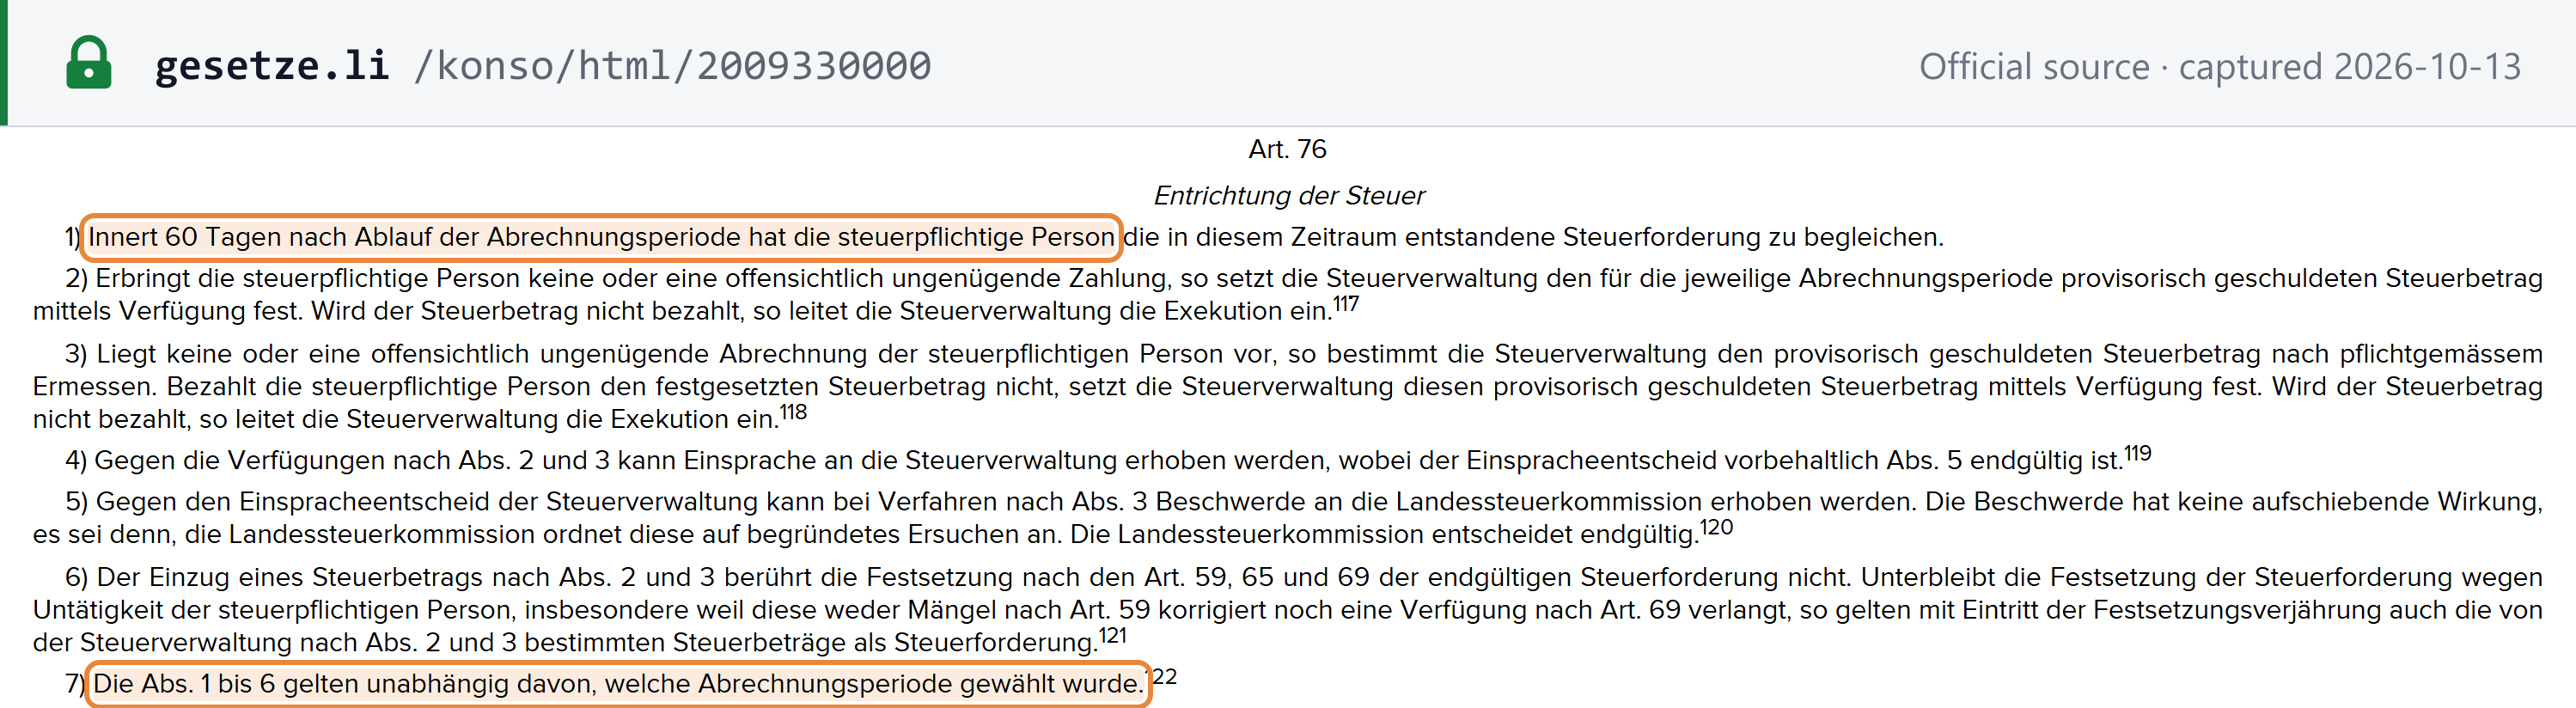
“Innert 60 Tagen nach Ablauf der Abrechnungsperiode hat die steuerpflichtige Person die in diesem Zeitraum entstandene Steuerforderung zu begleichen.”
Screenshot of the official source stating the rule that governs Liechtenstein's deadlines
Mehrwertsteuergesetz (MWSTG) — Art. 76 Abs. 1 und 7 — LILEX — Rechtsdienst der Regierung des Fürstentums Liechtenstein, captured 2026-10-13

What this calendar does not list

  • Not applicable Recapitulative listing — Liechtenstein is outside the EU VAT area, so there is no recapitulative statement or EC Sales List. Its VAT Act and VAT Ordinance (checked 13 October 2026) contain no listing duty of their own: the only notification procedure, for transfers of a business, is reported on the ordinary VAT return.
  • Not applicable E-invoicing / e-reporting cycle — There is no e-invoicing or e-reporting mandate. A VAT invoice is required only when the customer asks for one (MWSTG Art. 26 Abs. 1); the only e-invoicing law obliges public buyers above the procurement thresholds to accept European-standard e-invoices (ÖAWG Art. 49b), which fixes no submission cycle for businesses.

About this calendar

Which Liechtenstein tax deadlines does this calendar cover?

9 recurring indirect-tax obligations — Mehrwertsteuer returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-14). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.