Luxembourg compliance calendar

15 recurring Taxe sur la valeur ajoutée (TVA / VAT) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Luxembourg rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing Report / listing Law change takes effect

Dates already include the weekend and public-holiday shift where Luxembourg applies one — 7 of 15 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Déclaration TVA mensuelle — monthly VAT return

Taxe sur la valeur ajoutée (TVA / VAT) · Monthly · return filing

14th of the month after the month ends Verified 2026-10-08
Who files
Businesses with prior-year turnover above EUR 620,000 (excluding VAT), and any business the AED keeps on or assigns to the monthly regime, which is the legal default
Notes
Monthly filers send the return through eCDF before the 15th of the following month — so by the 14th — and pay the VAT when they file. When the 14th falls on a weekend the deadline moves to Monday: the October 2026 return is due Monday 16 November. Monthly filers also file an annual return before 1 May. The AED decides your filing cycle and reviews it at the end of each year; a return filed for a period other than your registered one is not taken into account.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 64, paragraphe 6; payment article 61bis AED
See the source text
“Elle doit être déposée avant le quinzième jour du mois qui suit la période imposable.”
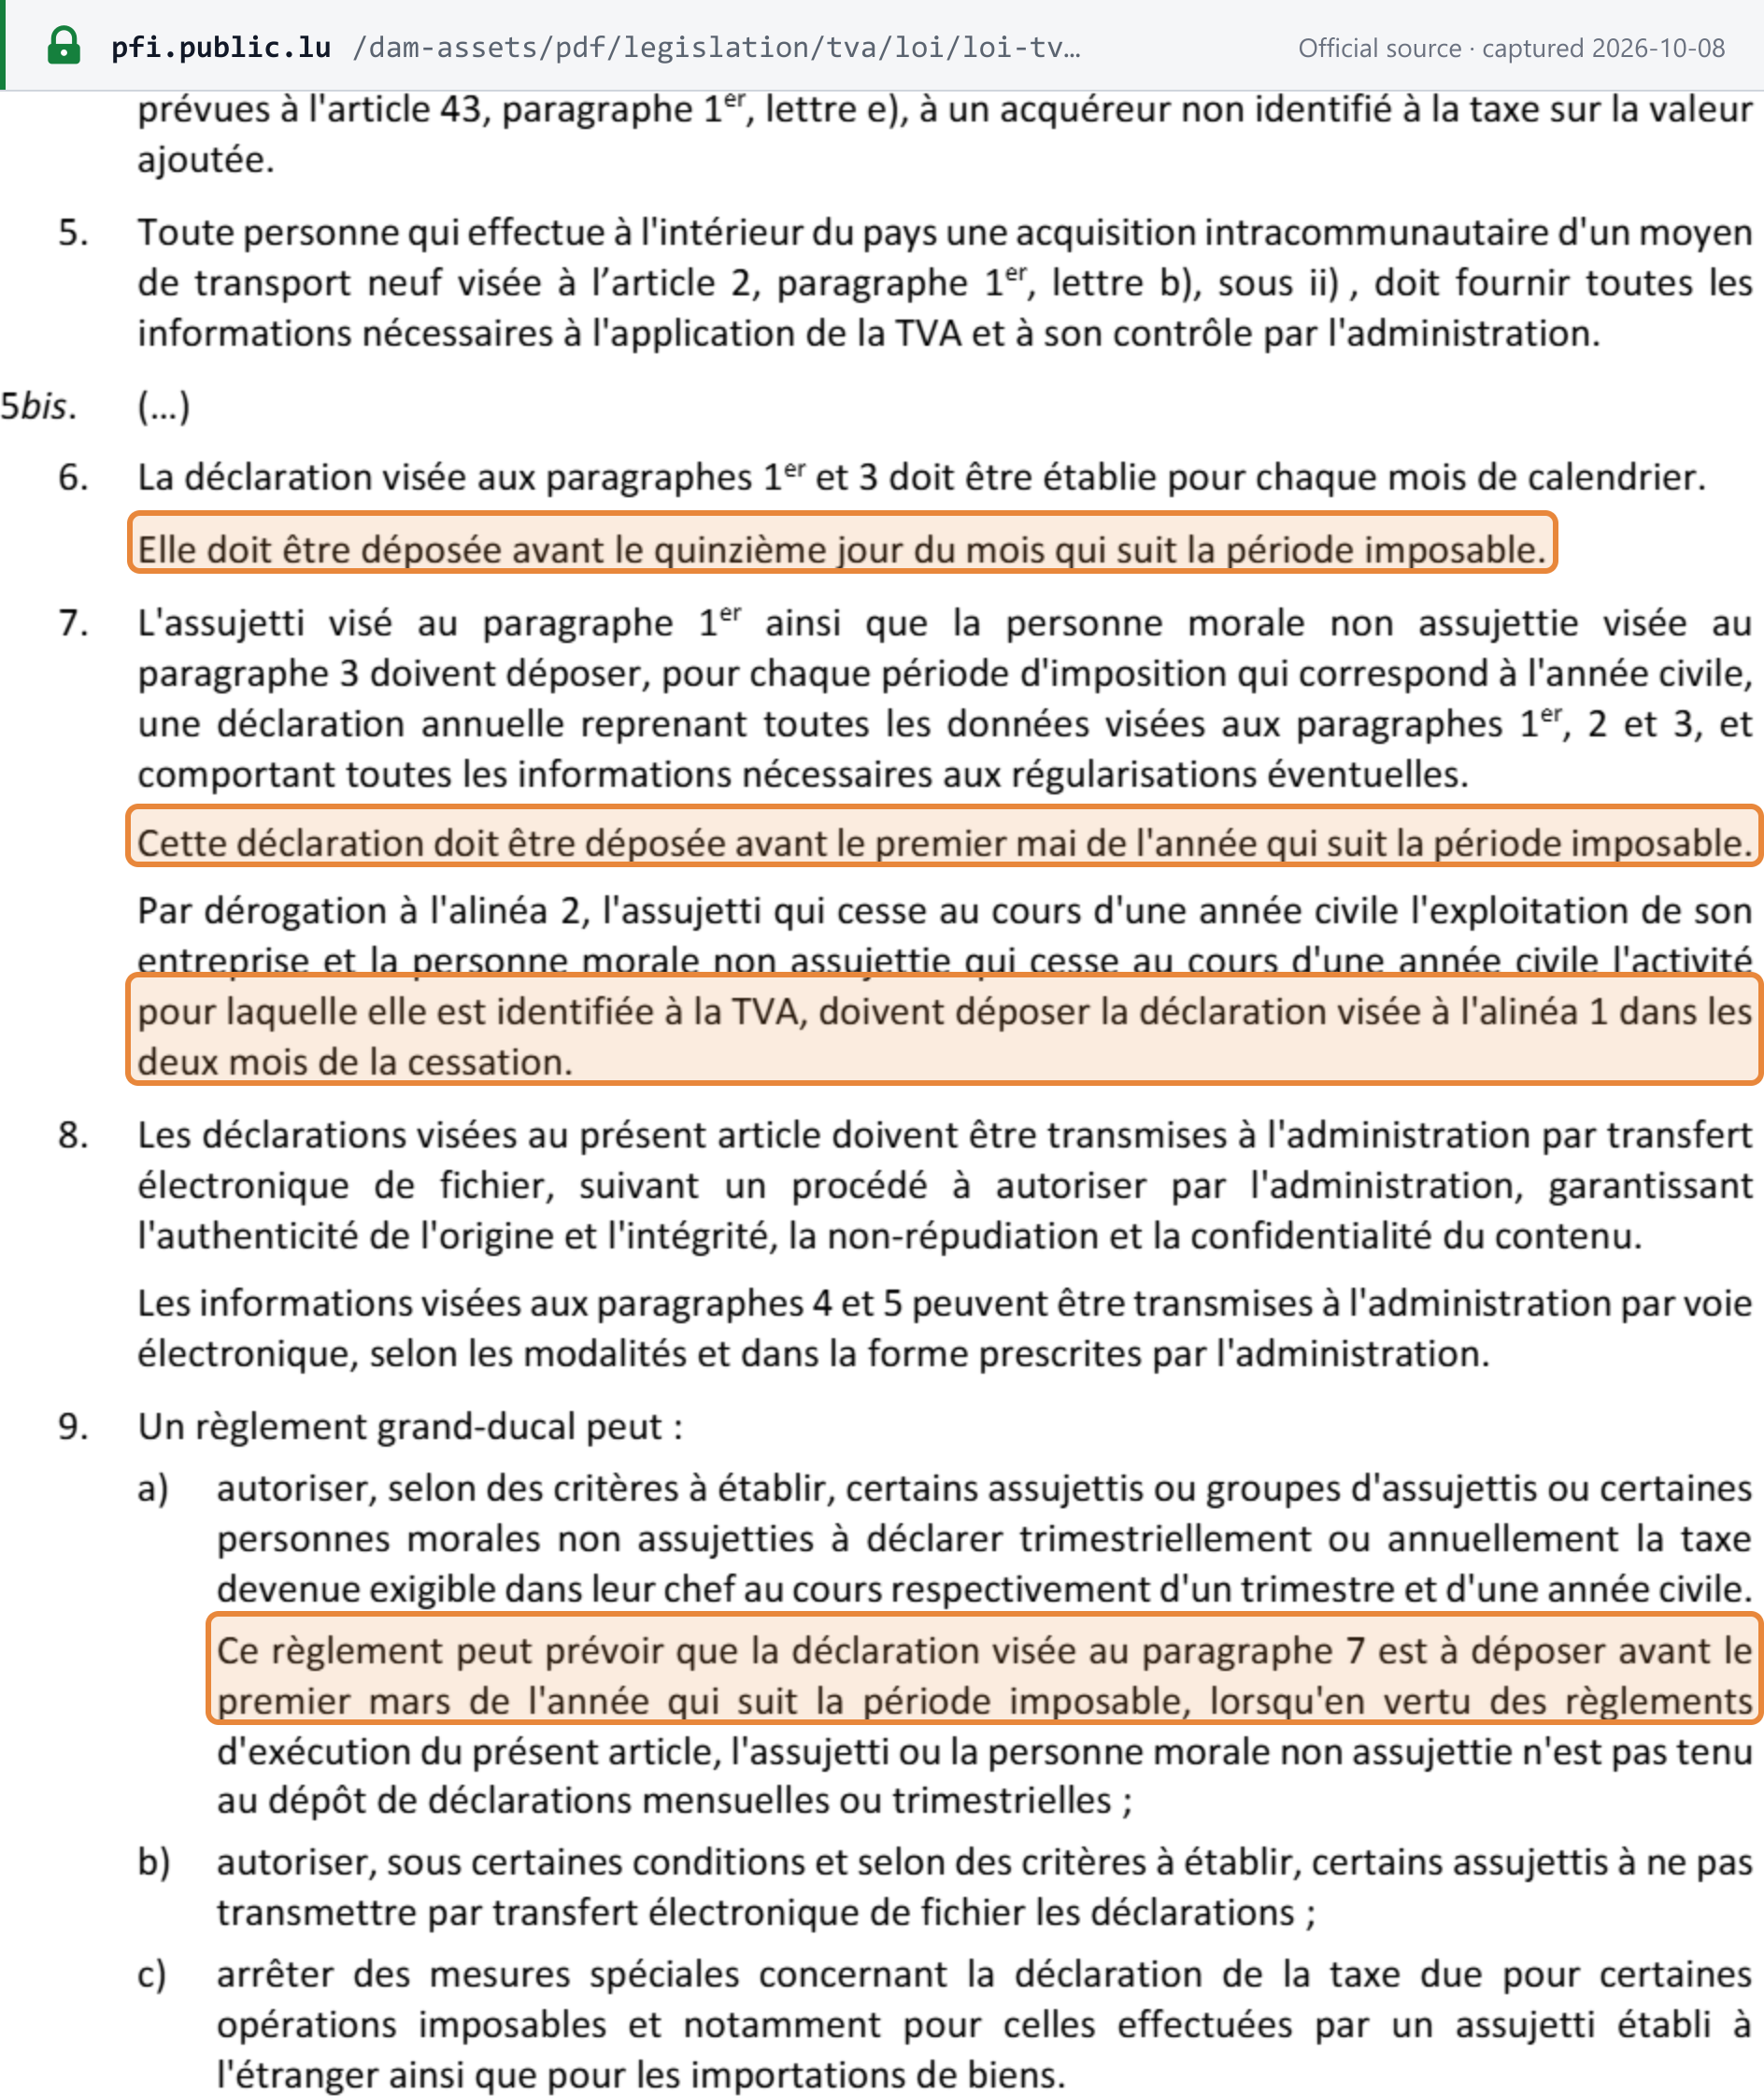
Screenshot of AED showing the Déclaration TVA mensuelle — monthly VAT return deadline Open full size Captured from AED on 2026-10-08
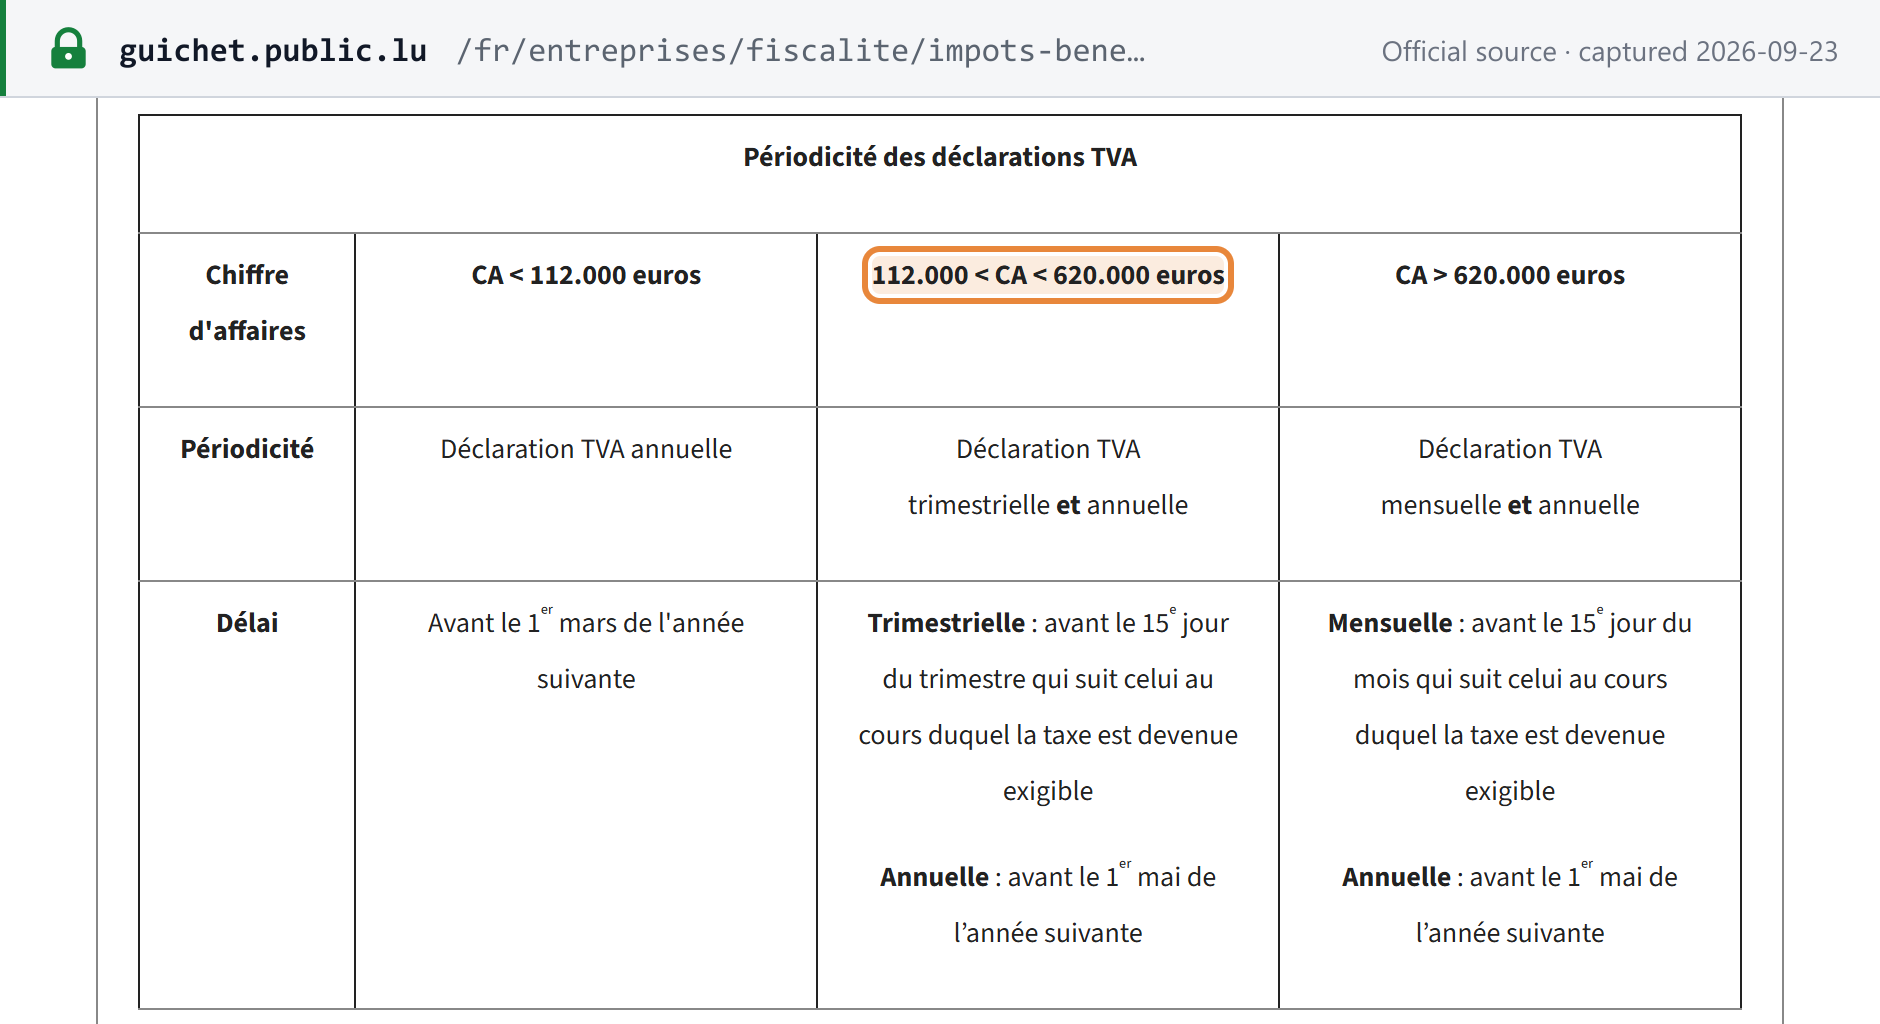
Déclaration TVA trimestrielle — quarterly VAT return

Taxe sur la valeur ajoutée (TVA / VAT) · Quarterly · return filing

14th of the month after the quarter ends Verified 2026-10-08
Who files
Businesses with prior-year turnover above EUR 112,000 and up to EUR 620,000 (excluding VAT), placed on the quarterly regime by the AED
Notes
Quarterly filers file before the 15th of the first month of the next quarter — by 14 January, 14 April, 14 July and 14 October — and pay when they file. They also file an annual return before 1 May. Crossing a turnover band changes your cycle only from the following 1 January, once the AED has notified you in writing.
Source
Guichet.lu — Déclaration de TVA (périodicité et délais); Règlement grand-ducal du 23 décembre 1992, article 2 Guichet.lu
See the source text
“Trimestrielle : avant le 15e jour du trimestre qui suit celui au cours duquel la taxe est devenue exigible”
Screenshot of Guichet.lu showing the Déclaration TVA trimestrielle — quarterly VAT return deadline Open full size Captured from Guichet.lu on 2026-09-23

Déclaration TVA annuelle récapitulative — annual VAT return (monthly and quarterly filers)

Taxe sur la valeur ajoutée (TVA / VAT) · Annually · return filing

30th April each year Verified 2026-10-08
Who files
Every business on the monthly or quarterly regime, for the calendar year
Notes
Monthly and quarterly filers also file an annual summary return for the calendar year before 1 May — by 30 April — carrying the year's adjustments, and pay any balance it shows by the same date. In 2028, 30 April is a Sunday and 1 May a public holiday, so the 2027 return is due Tuesday 2 May. A business that stops trading files this return within two months of ceasing.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 64, paragraphe 7 AED
See the source text
“Cette déclaration doit être déposée avant le premier mai de l'année qui suit la période imposable.”
Screenshot of AED showing the Déclaration TVA annuelle récapitulative — annual VAT return (monthly and quarterly filers) deadline Open full size Captured from AED on 2026-10-08
Déclaration TVA annuelle — annual-only filers

Taxe sur la valeur ajoutée (TVA / VAT) · Annually · return filing

last day of the 2nd month after the year ends Verified 2026-10-08
Who files
Businesses with turnover of EUR 112,000 or less that are not under the small-business franchise, which file a single return for the calendar year
Notes
Smaller businesses file one VAT return a year, before 1 March of the following year — by the last day of February — and pay when they file. The 2026 return is due Monday 1 March 2027, because 28 February is a Sunday.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 64, paragraphe 9, point a); Règlement grand-ducal du 23 décembre 1992, article 3 AED
See the source text
“Ce règlement peut prévoir que la déclaration visée au paragraphe 7 est à déposer avant le premier mars de l'année qui suit la période imposable”
Screenshot of AED showing the Déclaration TVA annuelle — annual-only filers deadline Open full size Captured from AED on 2026-10-08
État récapitulatif — EU sales listing, monthly

Taxe sur la valeur ajoutée (TVA / VAT) · Monthly · report / listing

24th of the month after the month ends Verified 2026-10-08
Who files
VAT-identified businesses that in the month made intra-EU supplies of goods or supplied B2B services on which the customer accounts for the VAT in its member state
Notes
The EU sales listing is filed electronically before the 25th of the following month — by the 24th — for each month in which you made such supplies. A weekend 24th moves to Monday: the September 2026 listing is due Monday 26 October. Paper listings have not been accepted since 2020.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 64bis, paragraphe 3 AED
See the source text
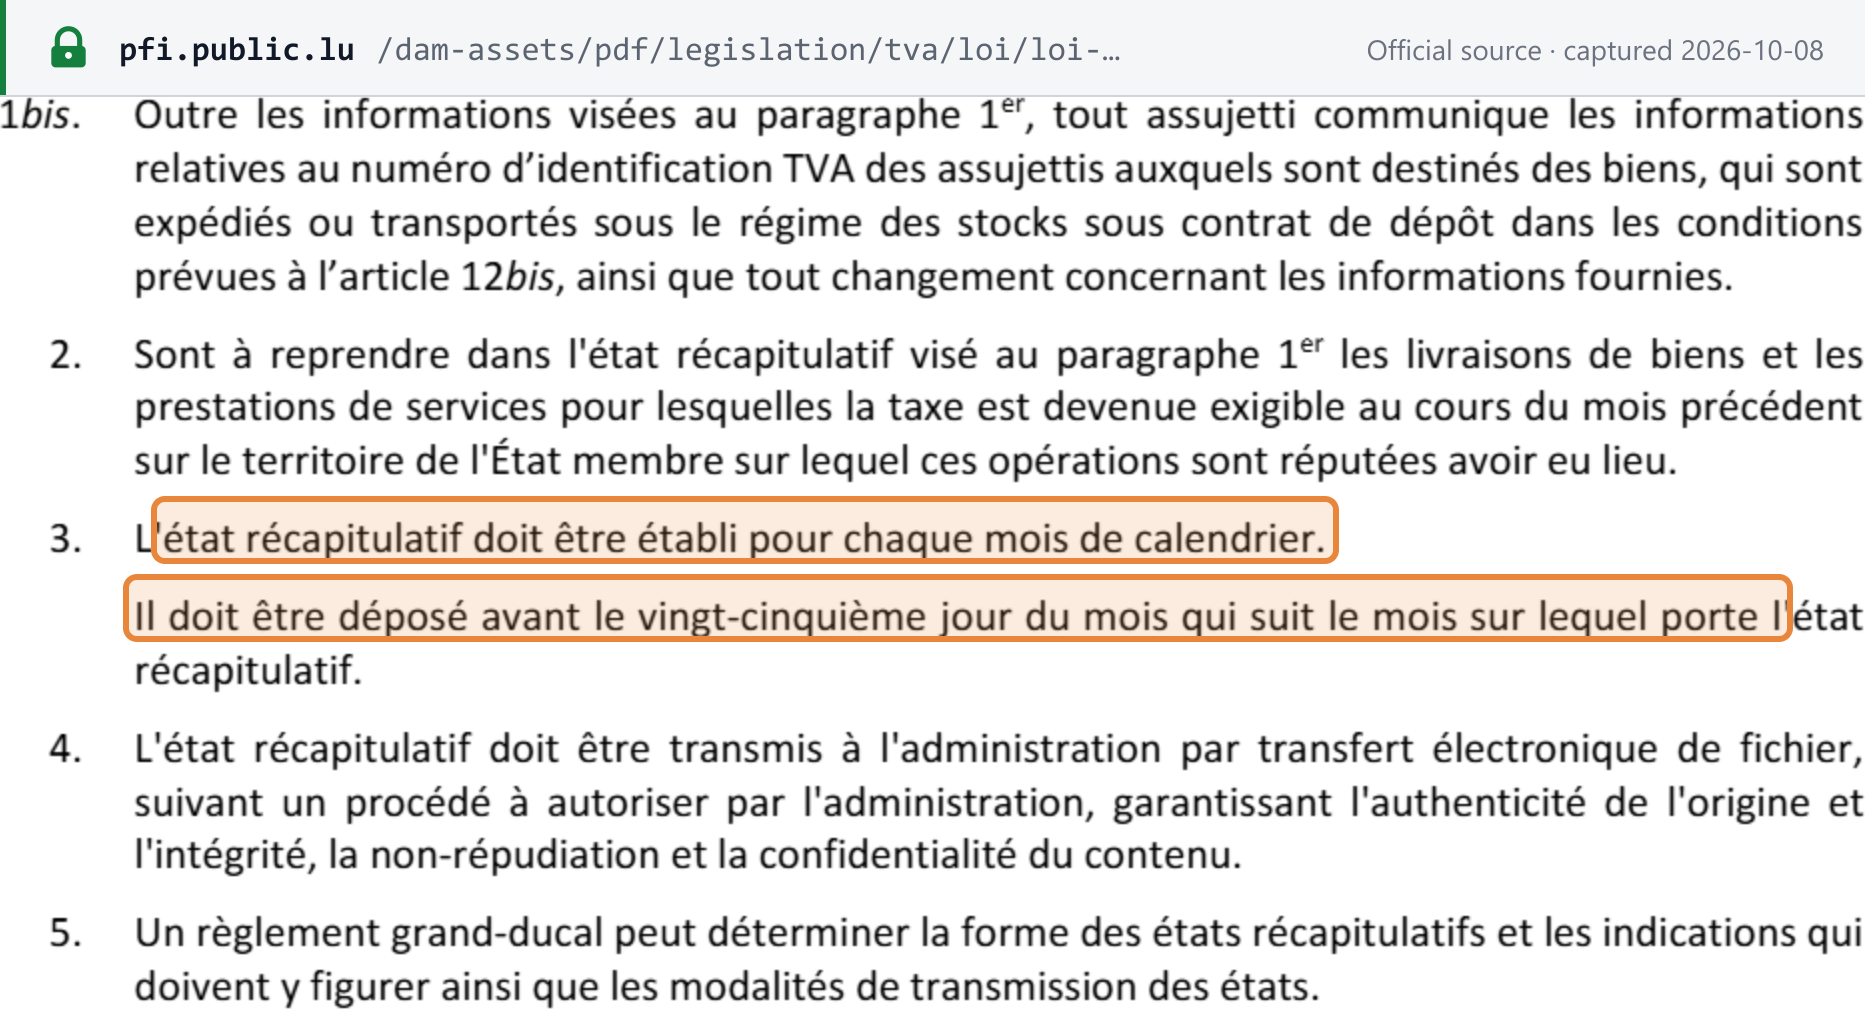
“Il doit être déposé avant le vingt-cinquième jour du mois qui suit le mois sur lequel porte l'état récapitulatif.”
Screenshot of AED showing the État récapitulatif — EU sales listing, monthly deadline Open full size Captured from AED on 2026-10-08
État récapitulatif — EU sales listing, quarterly option

Taxe sur la valeur ajoutée (TVA / VAT) · Quarterly · report / listing

24th of the month after the quarter ends Verified 2026-10-08
Who files
Businesses whose intra-EU supplies of goods stay under EUR 50,000 a quarter, and businesses listing only B2B services, which may choose quarterly listings
Notes
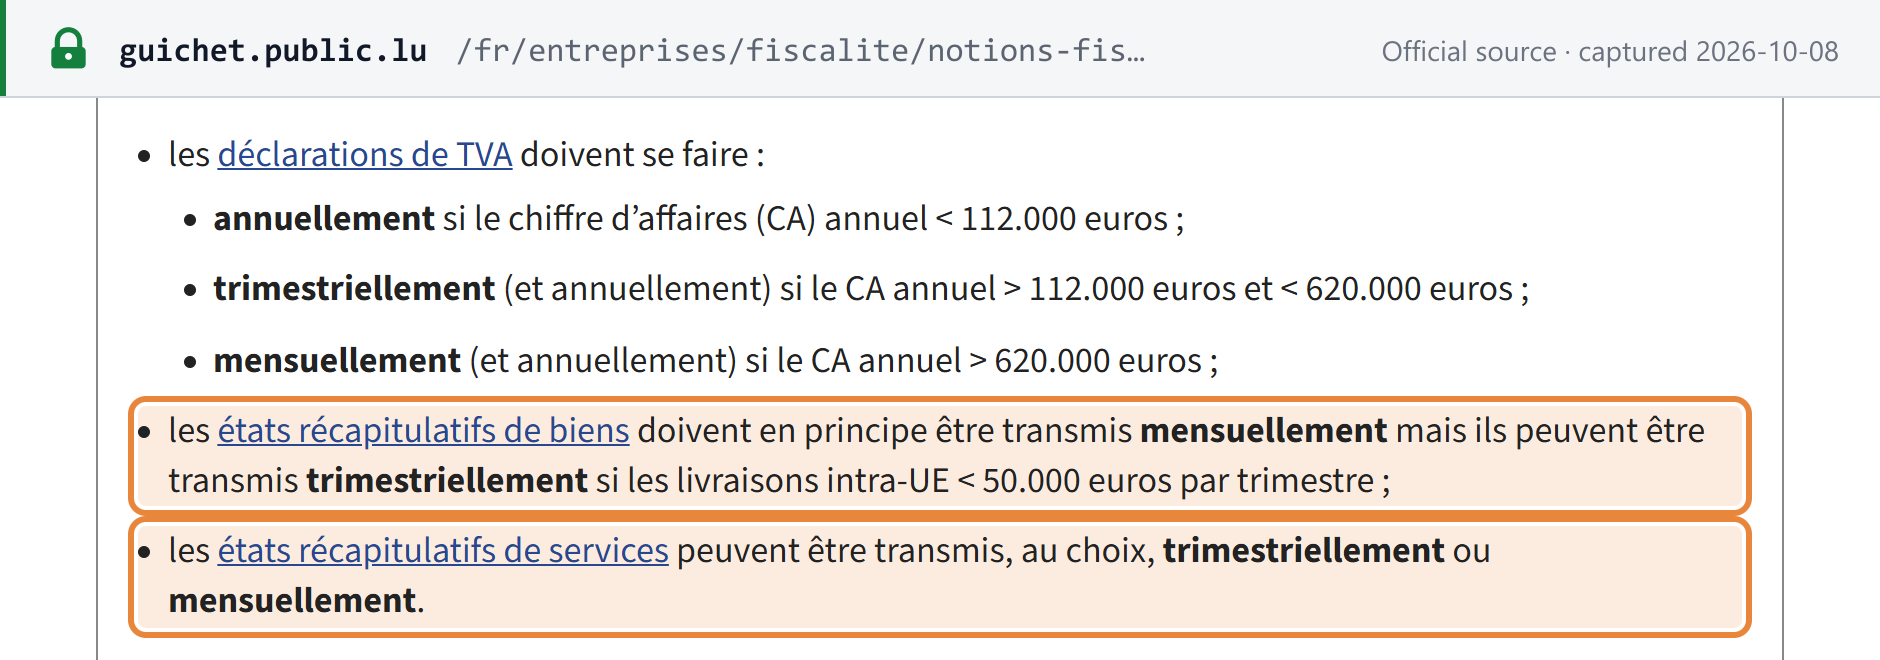
Goods listings may be filed quarterly while intra-EU supplies of goods stay under EUR 50,000 a quarter; services listings may be monthly or quarterly at your choice. A quarterly listing is due before the 25th of the month after the quarter.
Source
Guichet.lu — Calendrier fiscal (conditions préalables); Loi TVA article 64bis, paragraphe 5, point a) Guichet.lu
See the source text
“les états récapitulatifs de services peuvent être transmis, au choix, trimestriellement ou mensuellement.”
Screenshot of Guichet.lu showing the État récapitulatif — EU sales listing, quarterly option deadline Open full size Captured from Guichet.lu on 2026-10-08

OSS — non-Union scheme return

Taxe sur la valeur ajoutée (TVA / VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Non-EU businesses using Luxembourg as their member state of identification for services supplied to consumers in the EU
Notes
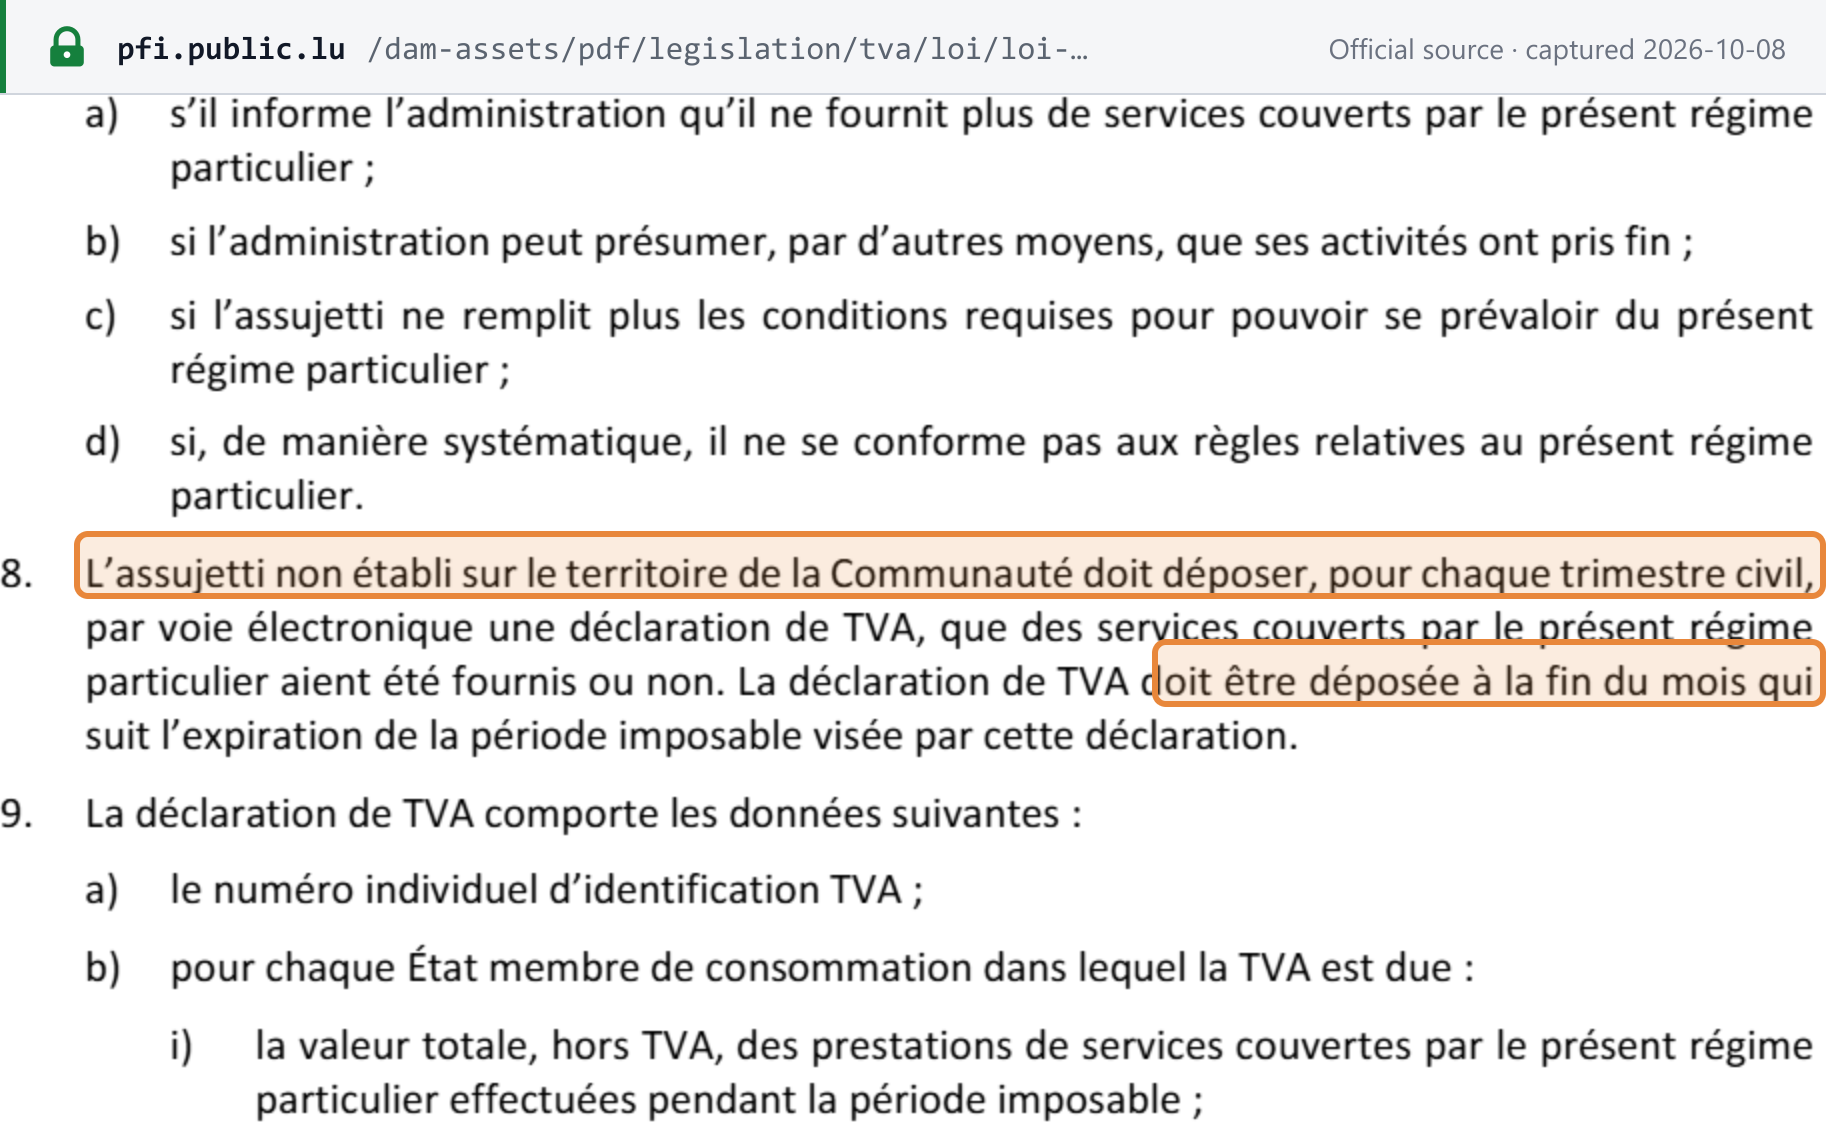
A quarterly return is due by the end of the month after each quarter, including quarters with no supplies, with payment by the same date. The European Commission states that OSS deadlines are not extended for weekends, so the date is shown as it falls: the third quarter of 2026 on Saturday 31 October.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 56quinquies, paragraphe 8 AED
See the source text
“La déclaration de TVA doit être déposée à la fin du mois qui suit l’expiration de la période imposable visée par cette déclaration.”
Screenshot of AED showing the OSS — non-Union scheme return deadline Open full size Captured from AED on 2026-10-08
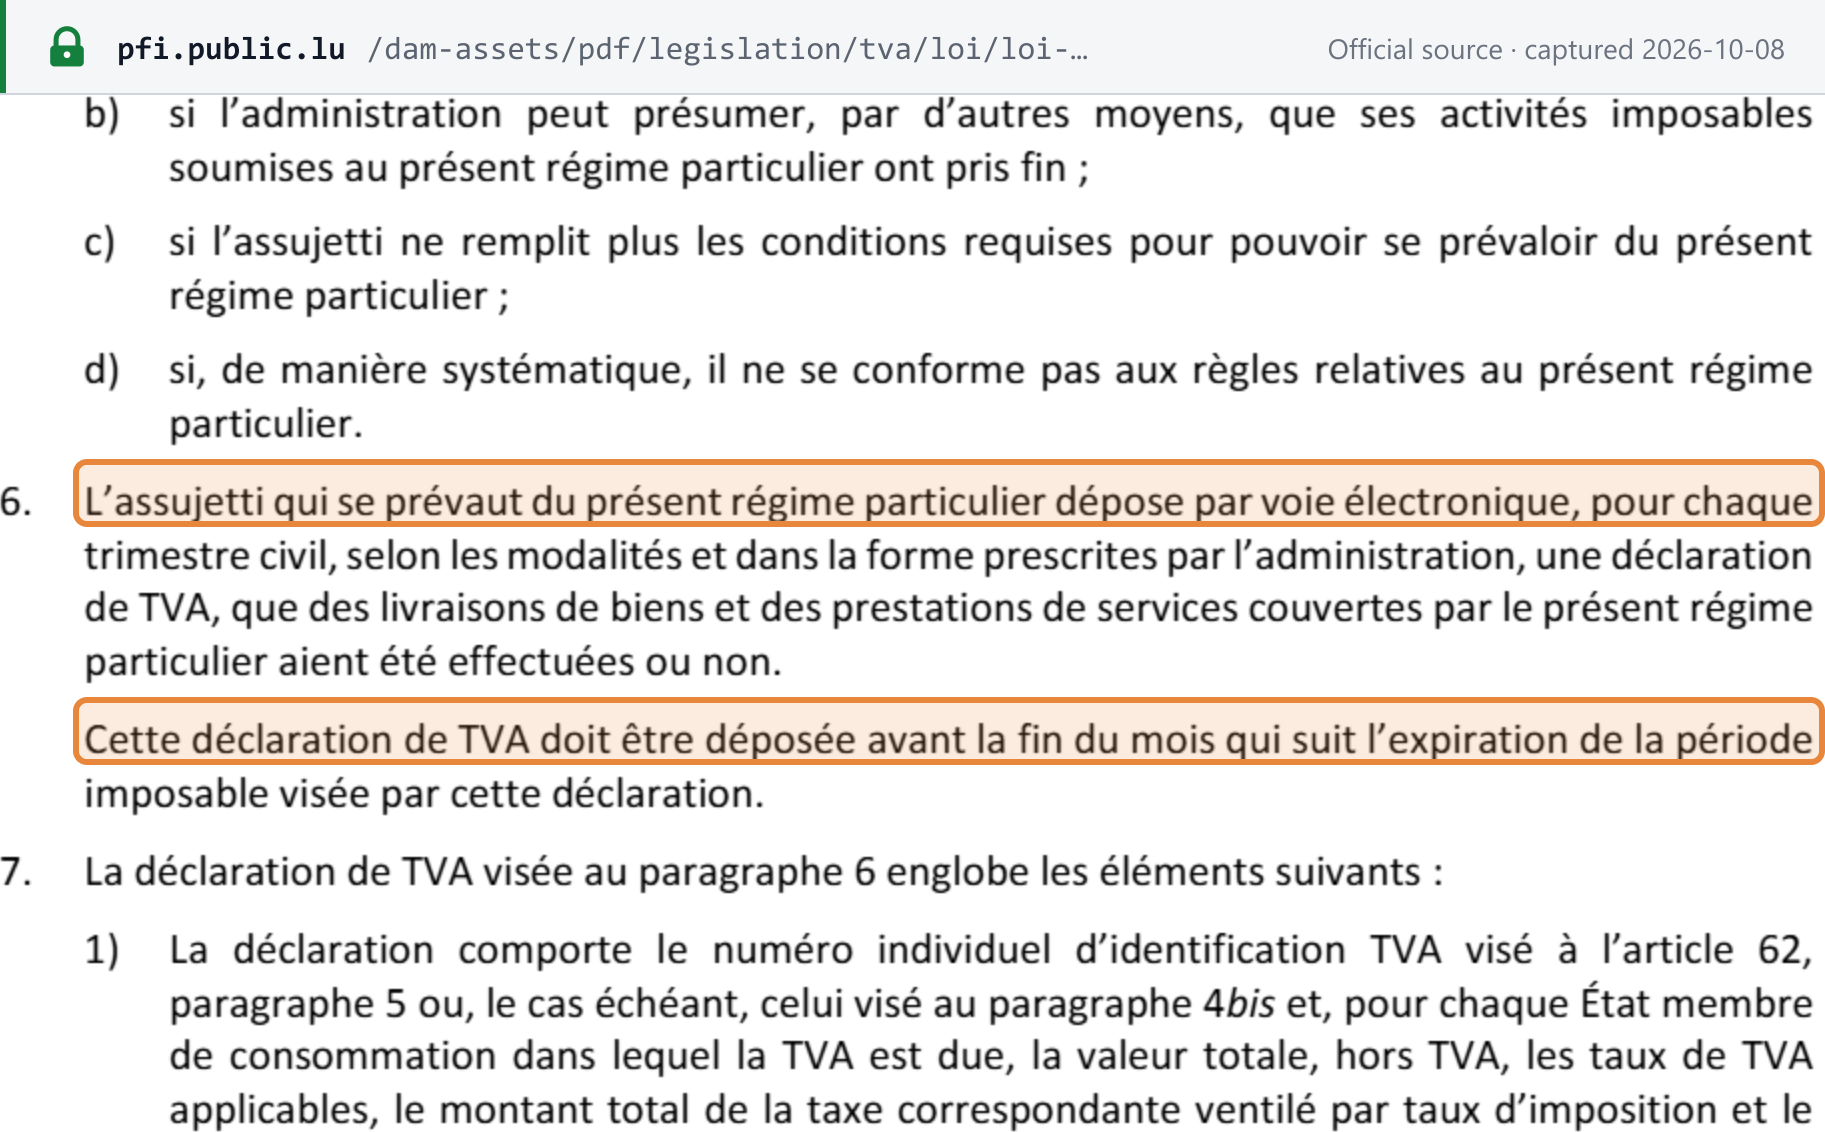
OSS — Union scheme return

Taxe sur la valeur ajoutée (TVA / VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Businesses using Luxembourg as their member state of identification for intra-EU distance sales of goods and B2C services taxed in other member states
Notes
Union OSS returns are quarterly and due before the end of the month after the quarter, with payment by the same date. The European Commission states that OSS deadlines are not extended for weekends or holidays, so the dates are shown as they fall; in practice, file by the last working day of that month.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 56sexies, paragraphe 6 AED
See the source text
“L’assujetti qui se prévaut du présent régime particulier dépose par voie électronique, pour chaque trimestre civil, selon les modalités et dans la forme prescrites par l’administration, une déclaration de TVA”
Screenshot of AED showing the OSS — Union scheme return deadline Open full size Captured from AED on 2026-10-08
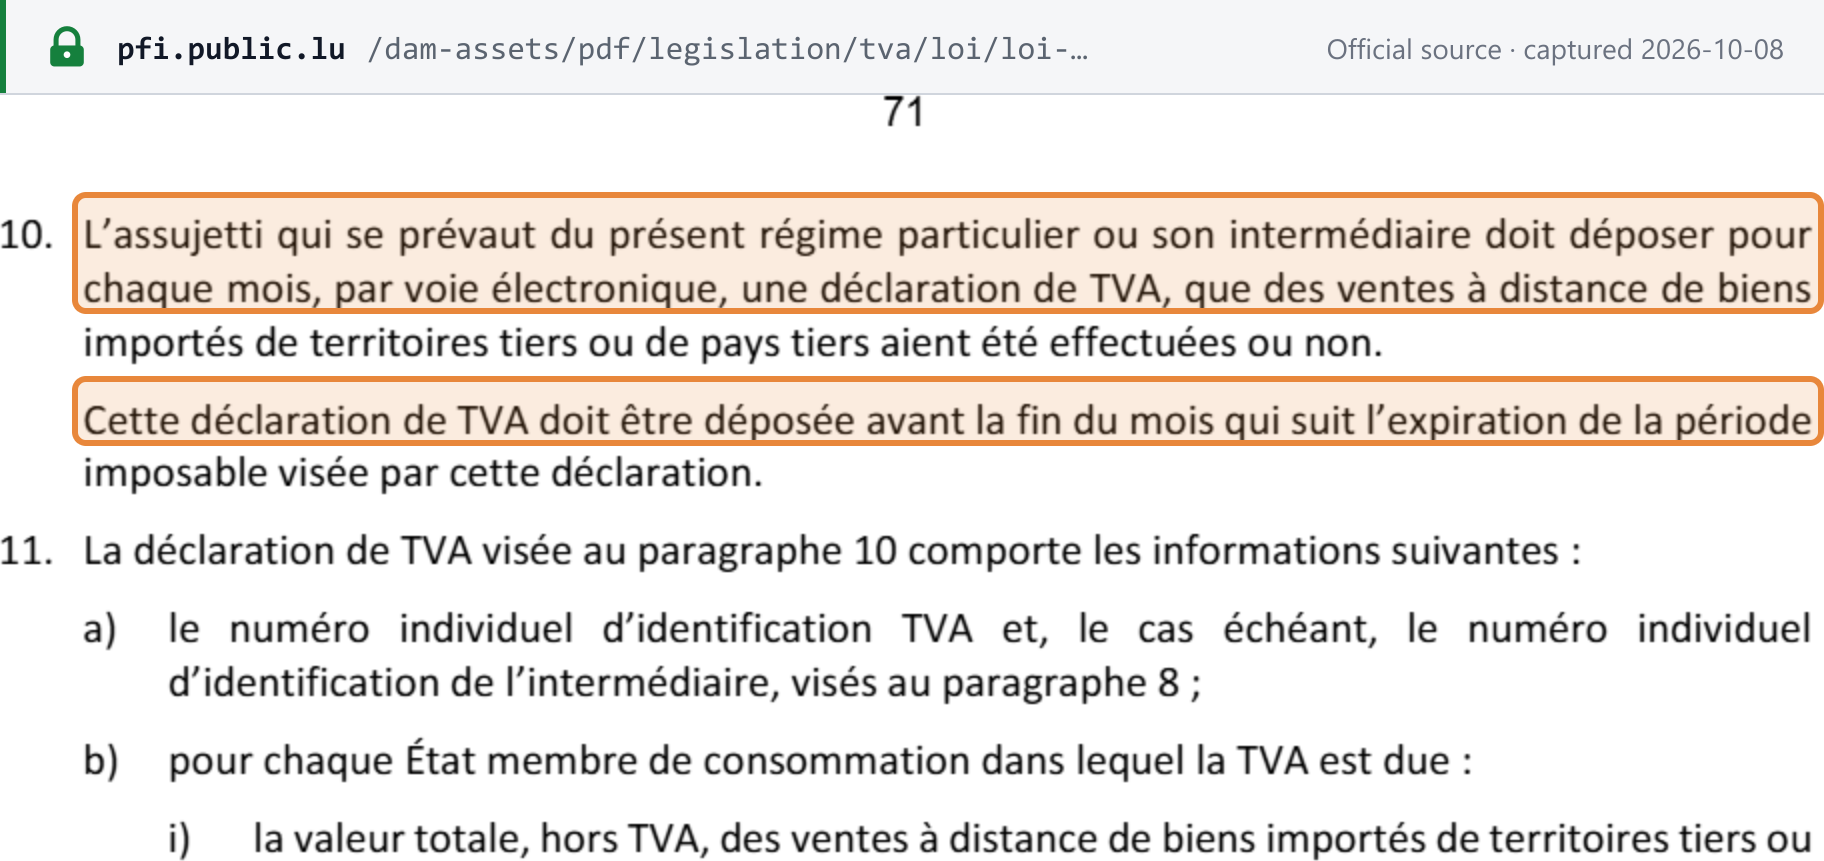
IOSS — import scheme return

Taxe sur la valeur ajoutée (TVA / VAT) — Import One Stop Shop · Monthly · return filing

last day of the month after the month ends Verified 2026-10-08
Who files
Businesses or intermediaries using Luxembourg as their member state of identification for B2C distance sales of imported goods in consignments up to EUR 150
Notes
IOSS returns are monthly, due before the end of the following month with payment. The European Commission states that they are not extended for weekends or holidays, so the dates are shown as they fall.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 56septies, paragraphe 10 AED
See the source text
“L’assujetti qui se prévaut du présent régime particulier ou son intermédiaire doit déposer pour chaque mois, par voie électronique, une déclaration de TVA”
Screenshot of AED showing the IOSS — import scheme return deadline Open full size Captured from AED on 2026-10-08
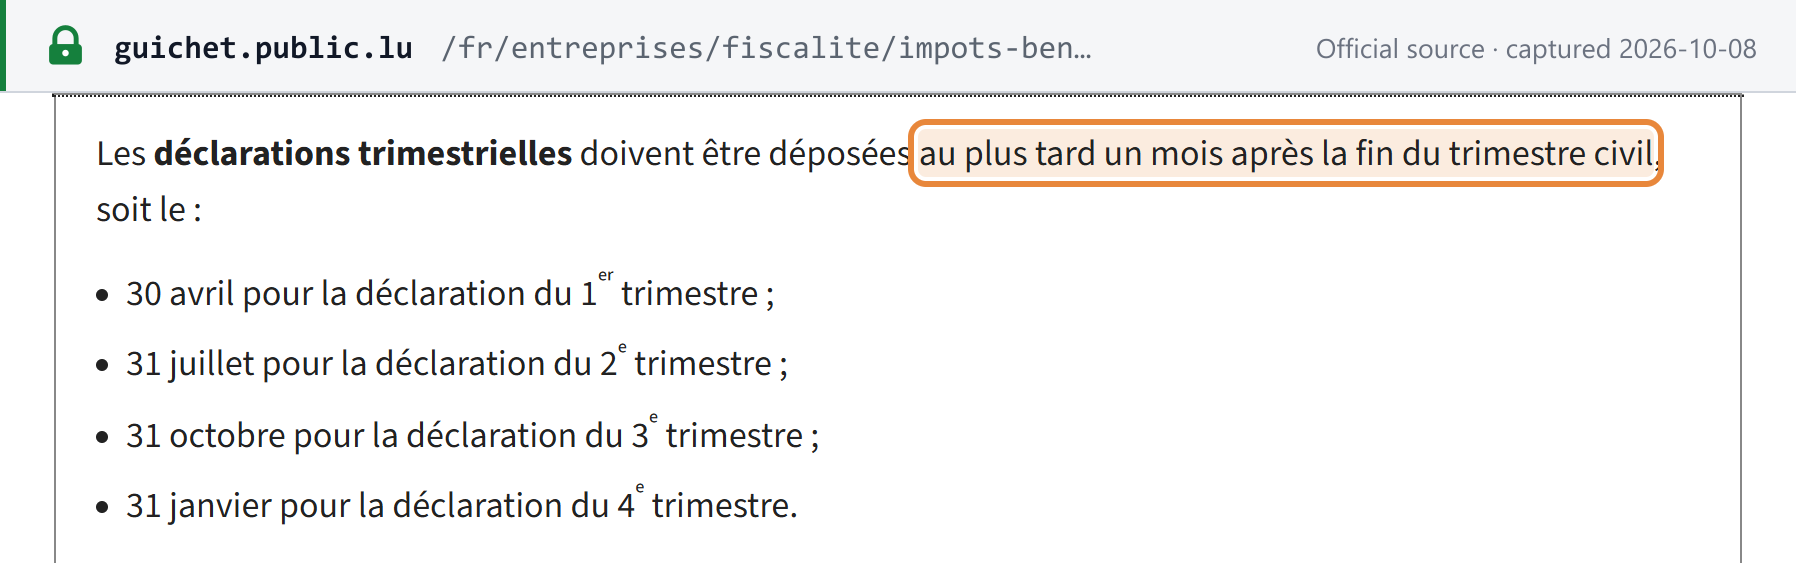
Déclaration trimestrielle — EU cross-border SME scheme

Taxe sur la valeur ajoutée (TVA / VAT) — EU SME scheme · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Luxembourg-established businesses using the VAT exemption in other EU member states under the cross-border franchise scheme
Notes
Small businesses using the EU-wide exemption report their Luxembourg turnover and their turnover in each other member state every quarter through MyGuichet.lu, by 30 April, 31 July, 31 October and 31 January — reporting zero for a quarter with no sales.
Source
Guichet.lu — Régime de franchise transfrontalier; Loi TVA article 57quater, paragraphe 5 Guichet.lu
See the source text
“Les déclarations trimestrielles doivent être déposées au plus tard un mois après la fin du trimestre civil, soit le :”
Screenshot of Guichet.lu showing the Déclaration trimestrielle — EU cross-border SME scheme deadline Open full size Captured from Guichet.lu on 2026-10-08

Small-business franchise — annual turnover notice

Taxe sur la valeur ajoutée (TVA / VAT) · Annually · report / listing

last day of the 2nd month after the year ends Verified 2026-10-08
Who files
Businesses under the national small-business franchise only (annual turnover up to EUR 50,000), which file no VAT returns
Notes
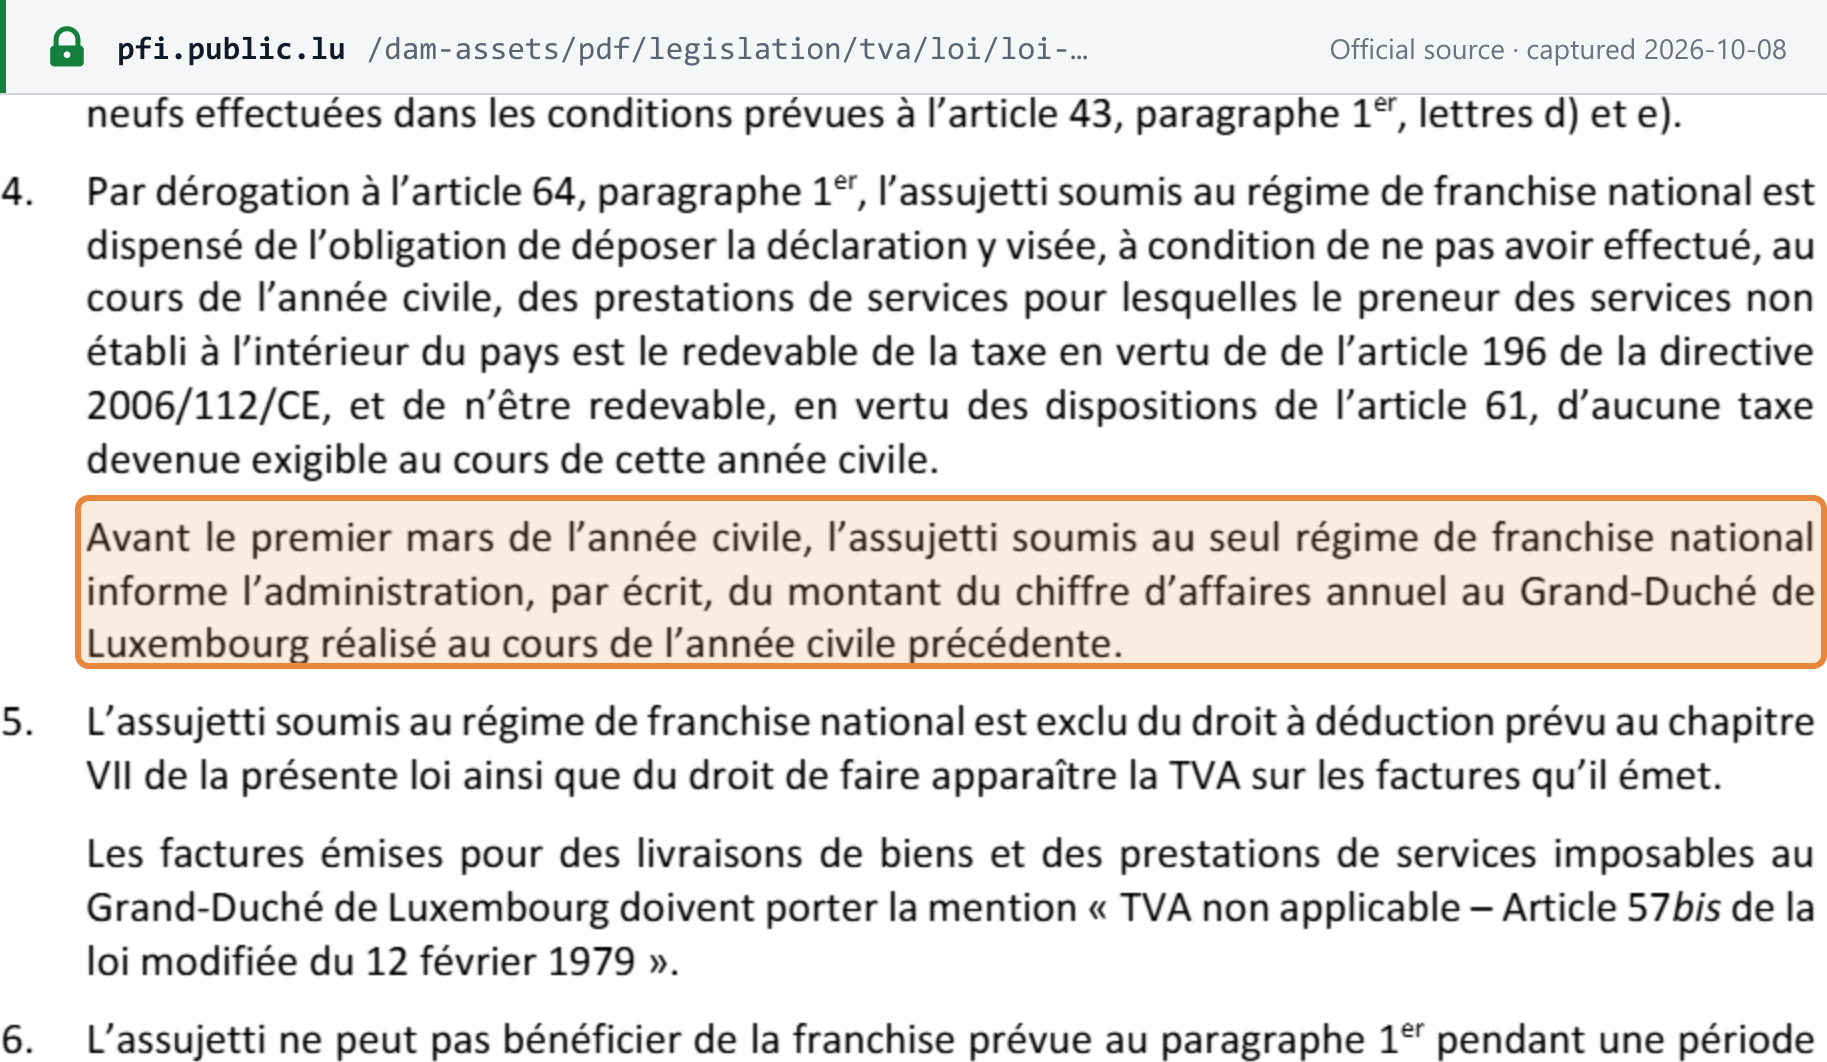
Exempt small businesses do not file VAT returns, but must tell the AED in writing, before 1 March each year, how much turnover they made in Luxembourg in the previous year.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 57bis, paragraphe 4 AED
See the source text
“Avant le premier mars de l’année civile, l’assujetti soumis au seul régime de franchise national informe l’administration, par écrit, du montant du chiffre d’affaires annuel au Grand-Duché de Luxembourg réalisé au cours de l’année civile précédente.”
Screenshot of AED showing the Small-business franchise — annual turnover notice deadline Open full size Captured from AED on 2026-10-08
CESOP — payment data report (payment service providers)

Taxe sur la valeur ajoutée (TVA / VAT) — payment data · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Payment service providers for which Luxembourg is the home or host member state and which exceed the cross-border payment threshold (more than 25 payments to the same payee in a quarter)
Notes
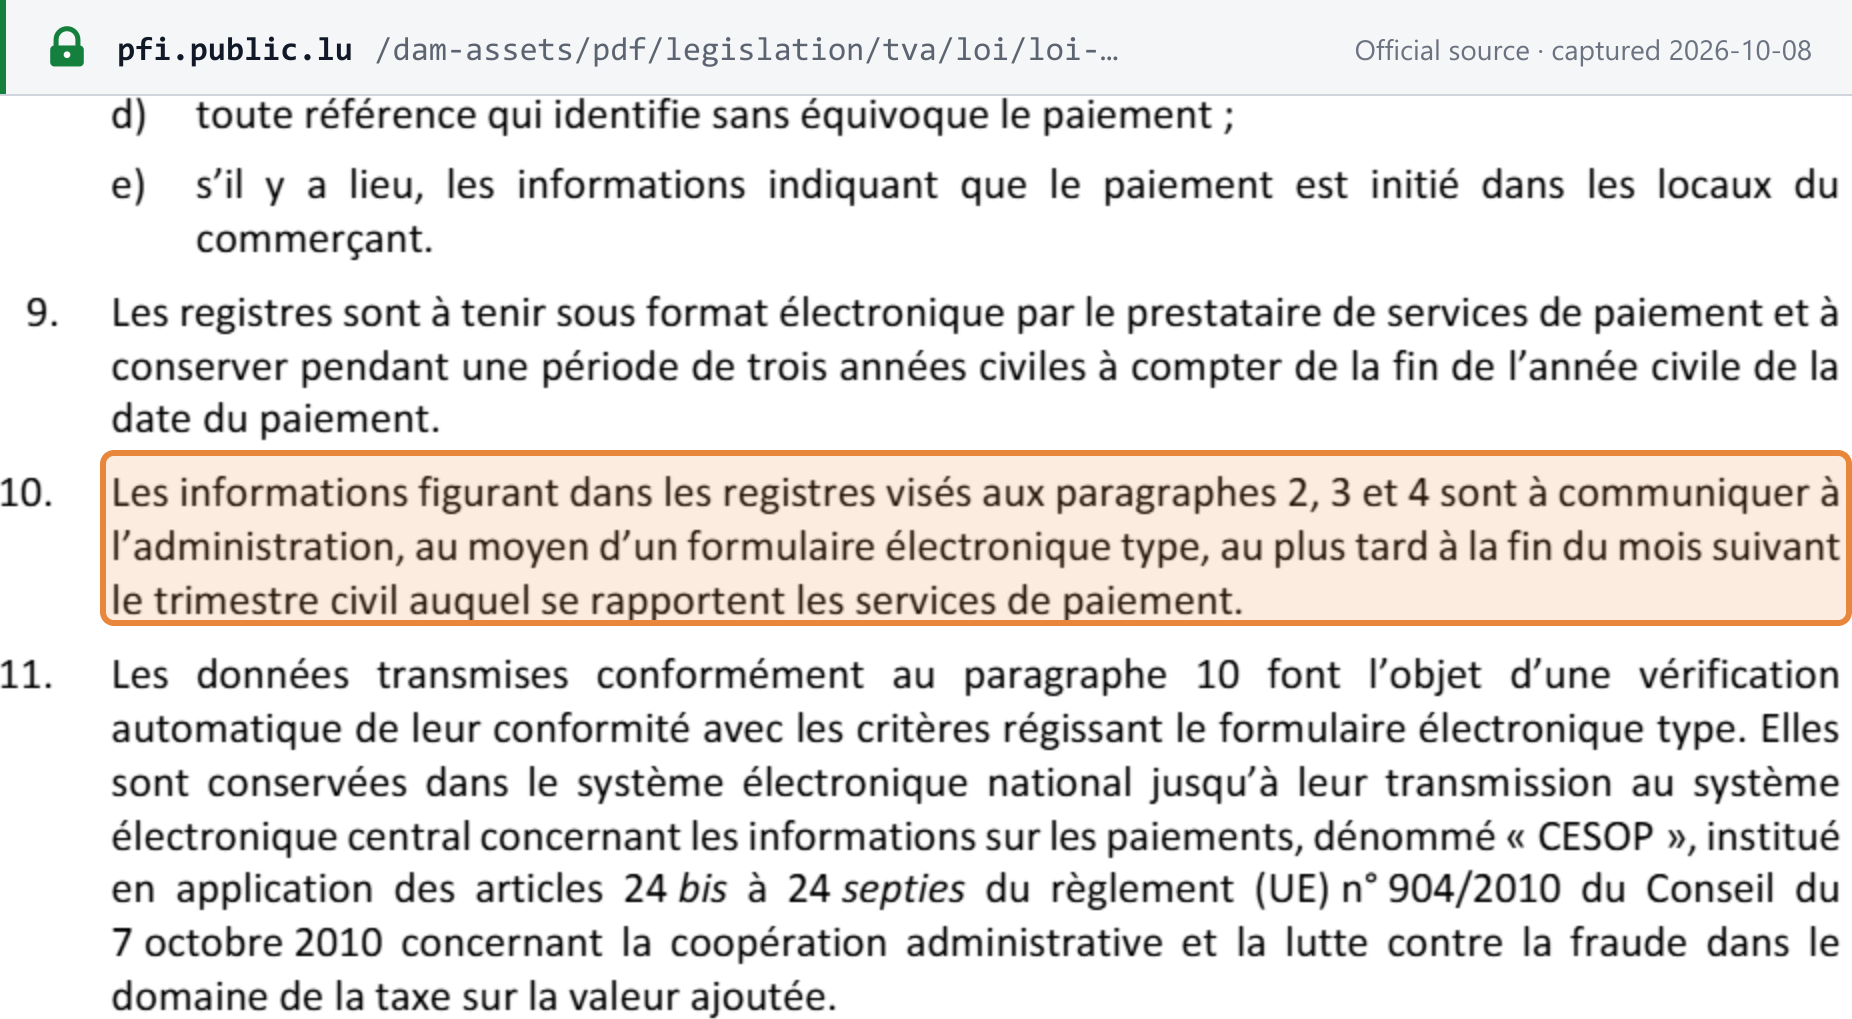
Banks, e-money and payment institutions report cross-border payment data for each quarter by the end of the following month.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 70ter, paragraphe 10 AED
See the source text
“au plus tard à la fin du mois suivant le trimestre civil auquel se rapportent les services de paiement.”
Screenshot of AED showing the CESOP — payment data report (payment service providers) deadline Open full size Captured from AED on 2026-10-08
Immatriculation à la TVA — VAT registration

Taxe sur la valeur ajoutée (TVA / VAT) · One-off · registration

within 15 days of the start of taxable activity Verified 2026-10-08
Who files
Businesses starting a taxable activity in Luxembourg that are not exempt from registration
Notes
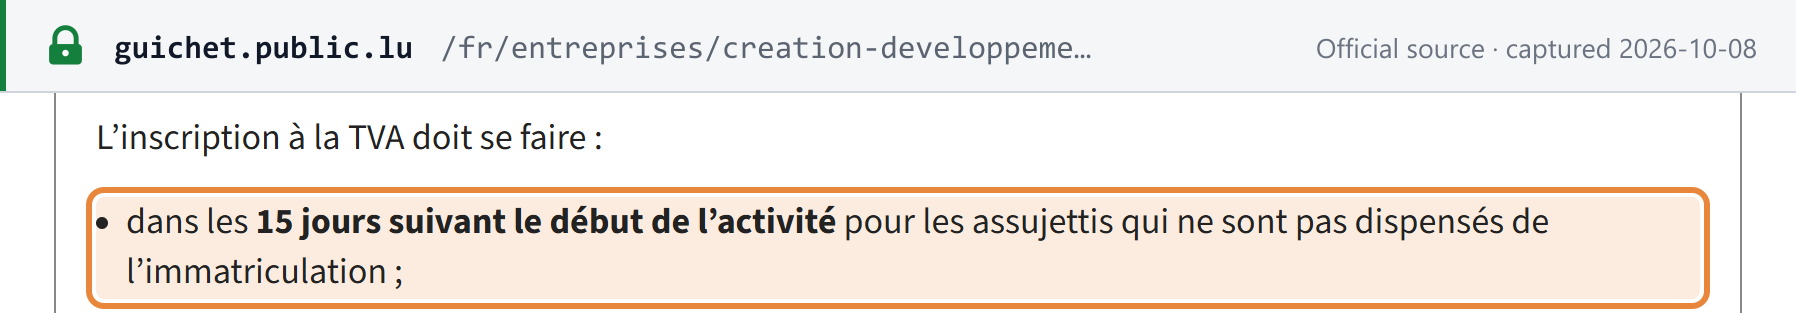
Register with the AED within 15 days of starting a taxable activity. Businesses under the small-business franchise and non-taxable legal persons must register before their first intra-EU acquisition above the threshold, first purchase of services from abroad on which they owe the VAT, or first cross-border B2B service. Non-established businesses have no threshold and register when they first make a supply on which they owe Luxembourg VAT, unless they use OSS.
Source
Guichet.lu — Inscription à la TVA; Règlement grand-ducal du 1er décembre 2009, article 1er; Loi TVA article 62, paragraphe 1er Guichet.lu
See the source text
“dans les 15 jours suivant le début de l’activité pour les assujettis qui ne sont pas dispensés de l’immatriculation ;”
Screenshot of Guichet.lu showing the Immatriculation à la TVA — VAT registration deadline Open full size Captured from Guichet.lu on 2026-10-08

Déclaration de cessation — notice of cessation

Taxe sur la valeur ajoutée (TVA / VAT) · One-off · registration

within 15 days of total or partial cessation of activity Verified 2026-10-08
Who files
VAT-registered businesses ceasing all or part of their activity
Notes
Send the signed cessation declaration to your VAT office within 15 days of stopping all or part of your activity. The final annual return is due within two months of ceasing.
Source
AED — Cessation d'activité économique; Loi TVA article 62, paragraphe 6 AED
See the source text
“une déclaration de cessation doit être envoyée dûment remplie et signée auprès du bureau d'imposition compétent dans les quinze jours de la cessation totale ou partielle.”
Screenshot of AED showing the Déclaration de cessation — notice of cessation deadline Open full size Captured from AED on 2026-10-08
EU SME scheme — notice of exceeding the EUR 100,000 Union threshold

Taxe sur la valeur ajoutée (TVA / VAT) — EU SME scheme · One-off · registration

within 15 business days of EU-wide turnover exceeding EUR 100,000 Verified 2026-10-08
Who files
Luxembourg-established businesses in the cross-border franchise scheme whose EU-wide turnover passes EUR 100,000
Notes
A business that passes EUR 100,000 of EU-wide turnover leaves the cross-border exemption and must tell the AED electronically within 15 working days.
Source
Loi du 12 février 1979 concernant la TVA, texte coordonné au 1er janvier 2026 — article 57quater, paragraphe 6 AED
See the source text
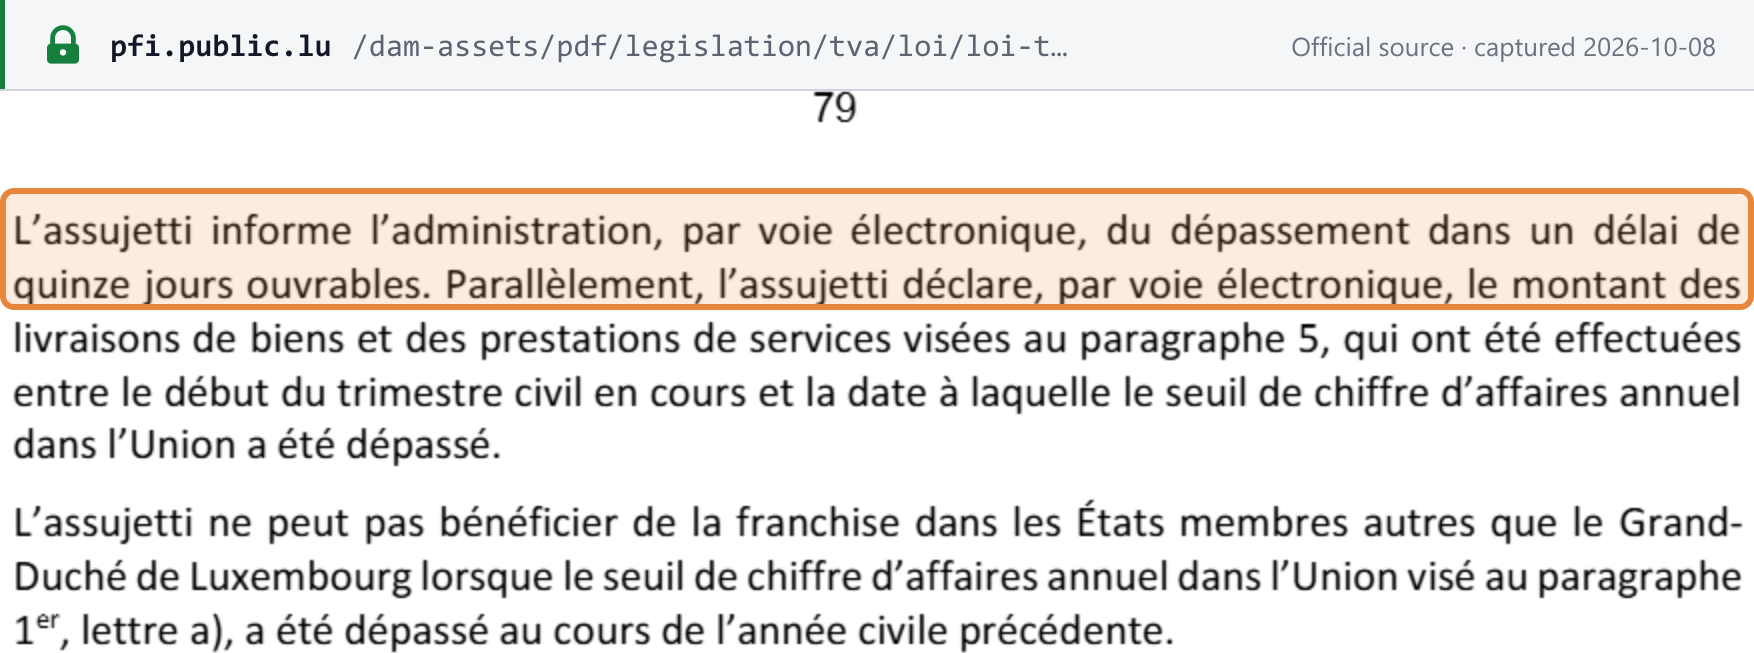
“L’assujetti informe l’administration, par voie électronique, du dépassement dans un délai de quinze jours ouvrables.”
Screenshot of AED showing the EU SME scheme — notice of exceeding the EUR 100,000 Union threshold deadline Open full size Captured from AED on 2026-10-08

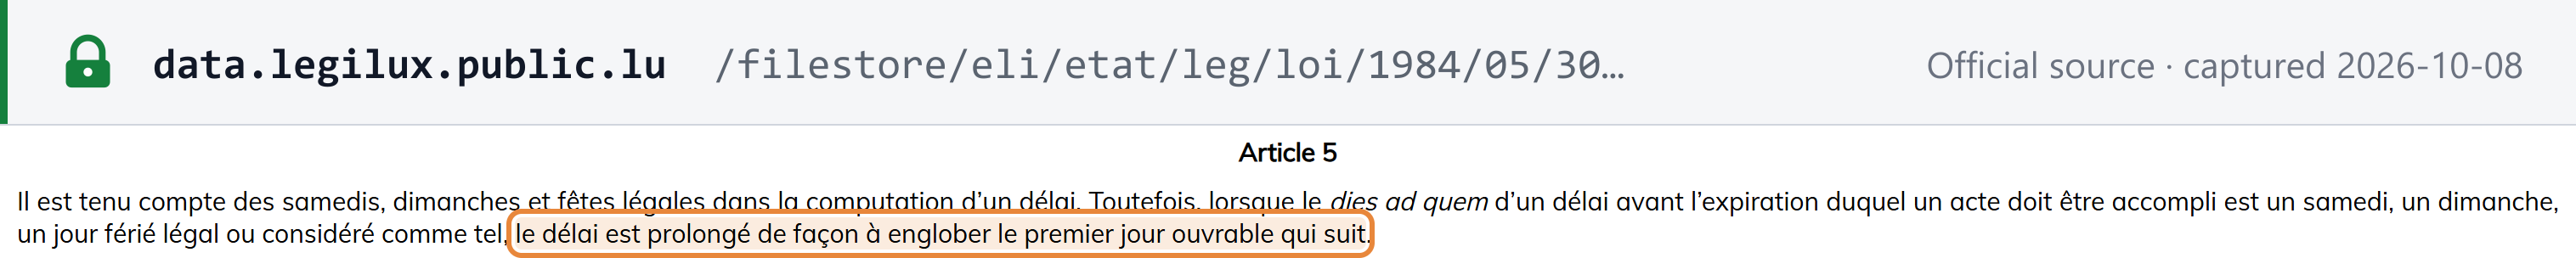
Luxembourg's VAT law sets every domestic deadline as "before" a date: returns before the 15th, the EU sales listing before the 25th, the annual return before 1 May. Read literally, that makes the day before the last day — the 14th, the 24th and 30 April — and those are the dates shown here; the AED does not publish a calendar of dates. Which return cycle you are on depends on turnover: monthly above EUR 620,000, quarterly between EUR 112,000 and EUR 620,000, and once a year below that; the AED assigns the cycle and reviews it each year. VAT is paid when the return is filed. A deadline falling on a Saturday, Sunday or public holiday is extended to the next working day under the general law on time-limits. OSS and IOSS returns follow the EU end-of-month timetable and, as the European Commission states, are not extended for weekends or holidays; they are shown unextended. Weekly excise declarations and insurance premium tax are not on this calendar yet.

“le délai est prolongé de façon à englober le premier jour ouvrable qui suit.”
Screenshot of the official source stating the rule that governs Luxembourg's deadlines
Loi du 30 mai 1984 portant approbation de la Convention européenne sur la computation des délais (Bâle, 16 mai 1972) — Convention, article 5 — Journal officiel du Grand-Duché de Luxembourg, captured 2026-10-08

What this calendar does not list

  • Not applicable E-invoicing / e-reporting cycle — Luxembourg's e-invoicing obligation covers invoices to public bodies through Peppol and fixes no submission cycle; B2B e-invoicing is proposed in bill 8815, which sets issuing dates but no reporting cadence and was not law as of 2026-10-08.
  • Not yet covered Periodic return — Not yet modelled: excise release-for-consumption declarations (AC4), due to customs by the Thursday of the week after goods leave the tax warehouse — a weekly cadence the calendar cannot yet express; insurance premium tax, declared and paid within 30 days of the quarter or year end depending on the regime the administration sets, whose governing law was not read; and the quarterly list of invoices at the 3% housing rate (Loi TVA art. 65bis, before the 15th of each quarter), whose filing channel was not confirmed.

New Luxembourg rules taking effect

Confirmed changes from the weekly scan — each links to its full record with the official source.

About this calendar

Which Luxembourg tax deadlines does this calendar cover?

15 recurring indirect-tax obligations — Taxe sur la valeur ajoutée (TVA / VAT) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-08). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.