Romania compliance calendar

17 recurring Taxa pe valoarea adăugată (TVA) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Romania rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing Report / listing Other Law change takes effect

Dates already include the weekend and public-holiday shift where Romania applies one — 9 of 17 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Decont de taxă pe valoarea adăugată (D300) — monthly

Taxa pe valoarea adăugată (TVA) · Monthly · return filing

25th of the month after the month ends — but the 21st in December (moved to the working day before if that is not a working day) Verified 2026-10-07
Who files
Every person registered for VAT under art. 316 of the Fiscal Code whose tax period is the calendar month — the default, and compulsory where previous-year turnover exceeded EUR 100,000 or any intra-EU acquisition of goods was made
Notes
The calendar month is the default VAT period, and both the return and the VAT it shows are due by the 25th of the following month. A deadline on a Saturday, Sunday or public holiday moves to the next working day — the September 2026 return is due Monday 26 October. December is different: a return that would fall due on 25 December is due on 21 December instead, and if the 21st is not a working day, on the working day before it. File even when there is nothing to declare: ANAF cancels the VAT number of a monthly filer who files no return for six consecutive months. A business registered ex officio files monthly for its registration year.
Source
OPANAF nr. 174/2026 — Anexa 2, instrucțiuni de completare a decontului de TVA (formular 300), termenele de depunere Agenția Națională de Administrare Fiscală (ANAF)
See the source text
“pentru care termenul de declarare se împlineşte la 25 decembrie se depune la organul fiscal competent până la data de 21 decembrie. În situaţia în care data de 21 decembrie este zi nelucrătoare, formularul se depune până în ultima zi lucrătoare anterioară datei de 21 decembrie”
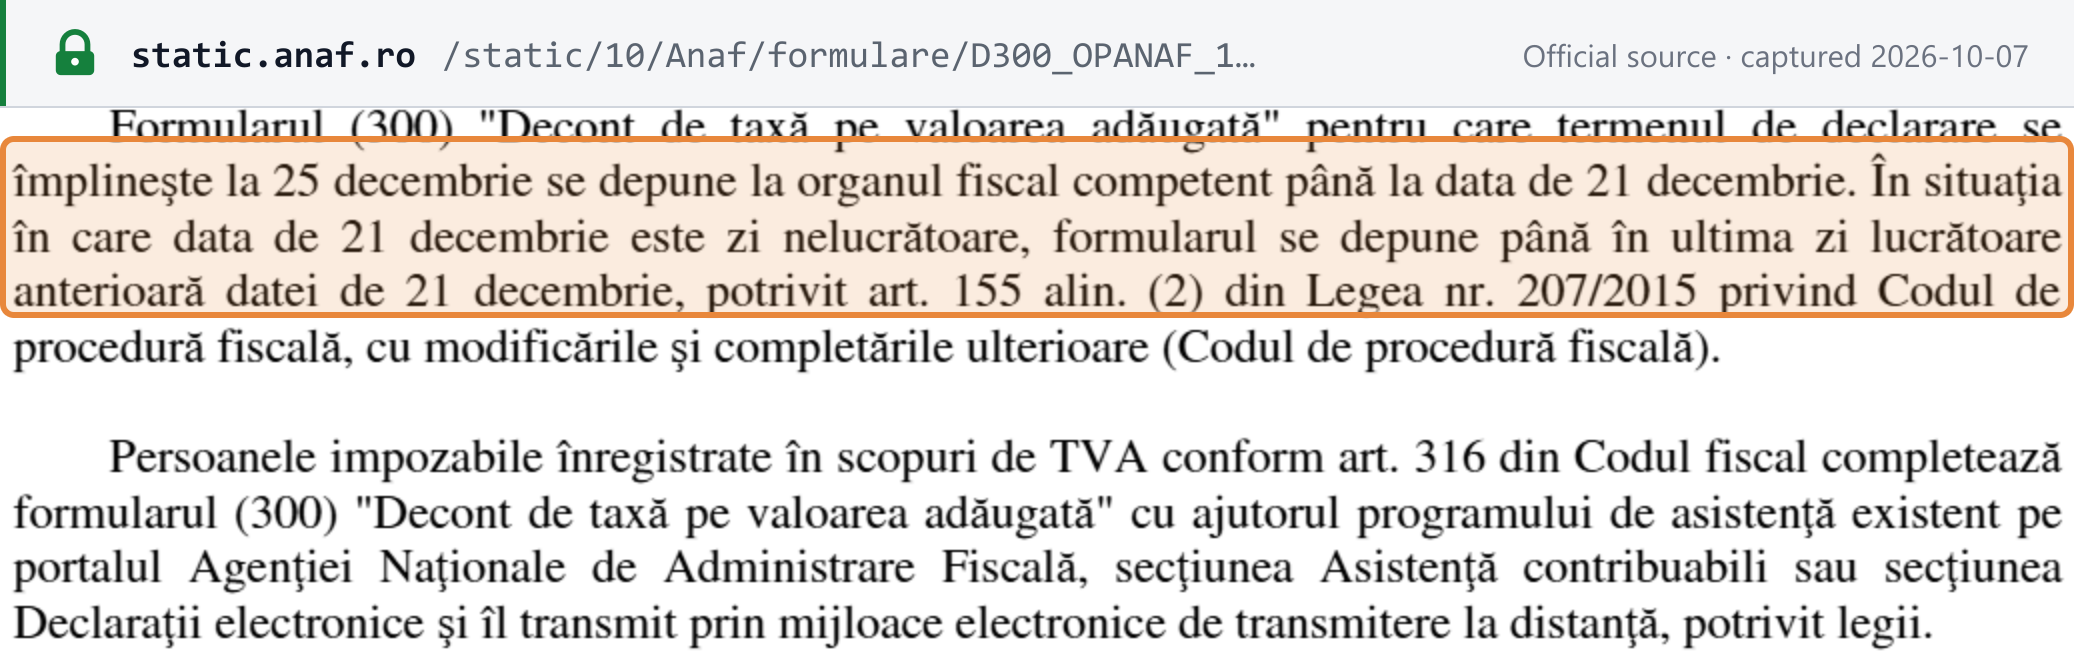
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Decont de taxă pe valoarea adăugată (D300) — monthly deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Decont de taxă pe valoarea adăugată (D300) — quarterly

Taxa pe valoarea adăugată (TVA) · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-07
Who files
VAT-registered persons whose previous-year turnover (taxable, exempt with credit and out-of-scope with credit) did not exceed EUR 100,000, converted at the BNR rate for 31 December, and who made no intra-EU acquisitions of goods in that year
Notes
You file quarterly if last year's turnover stayed within EUR 100,000 and you made no intra-EU acquisitions of goods. The return and the payment are due by the 25th of the month after the quarter, moved to the next working day where needed, so Q3 2026 is due 26 October and Q4 on 25 January 2027. A single taxable intra-EU acquisition of goods puts you on monthly returns for the rest of that year and the whole of the next, and a notice is due within five working days of the end of that month. Two consecutive quarters without a return cost you your VAT number. Half-yearly and annual periods exist only with ANAF's approval, for businesses that trade in very few months of the year.
Source
OPANAF nr. 174/2026 — Anexa 2, instrucțiuni de completare a decontului de TVA (formular 300), termenele de depunere Agenția Națională de Administrare Fiscală (ANAF)
See the source text
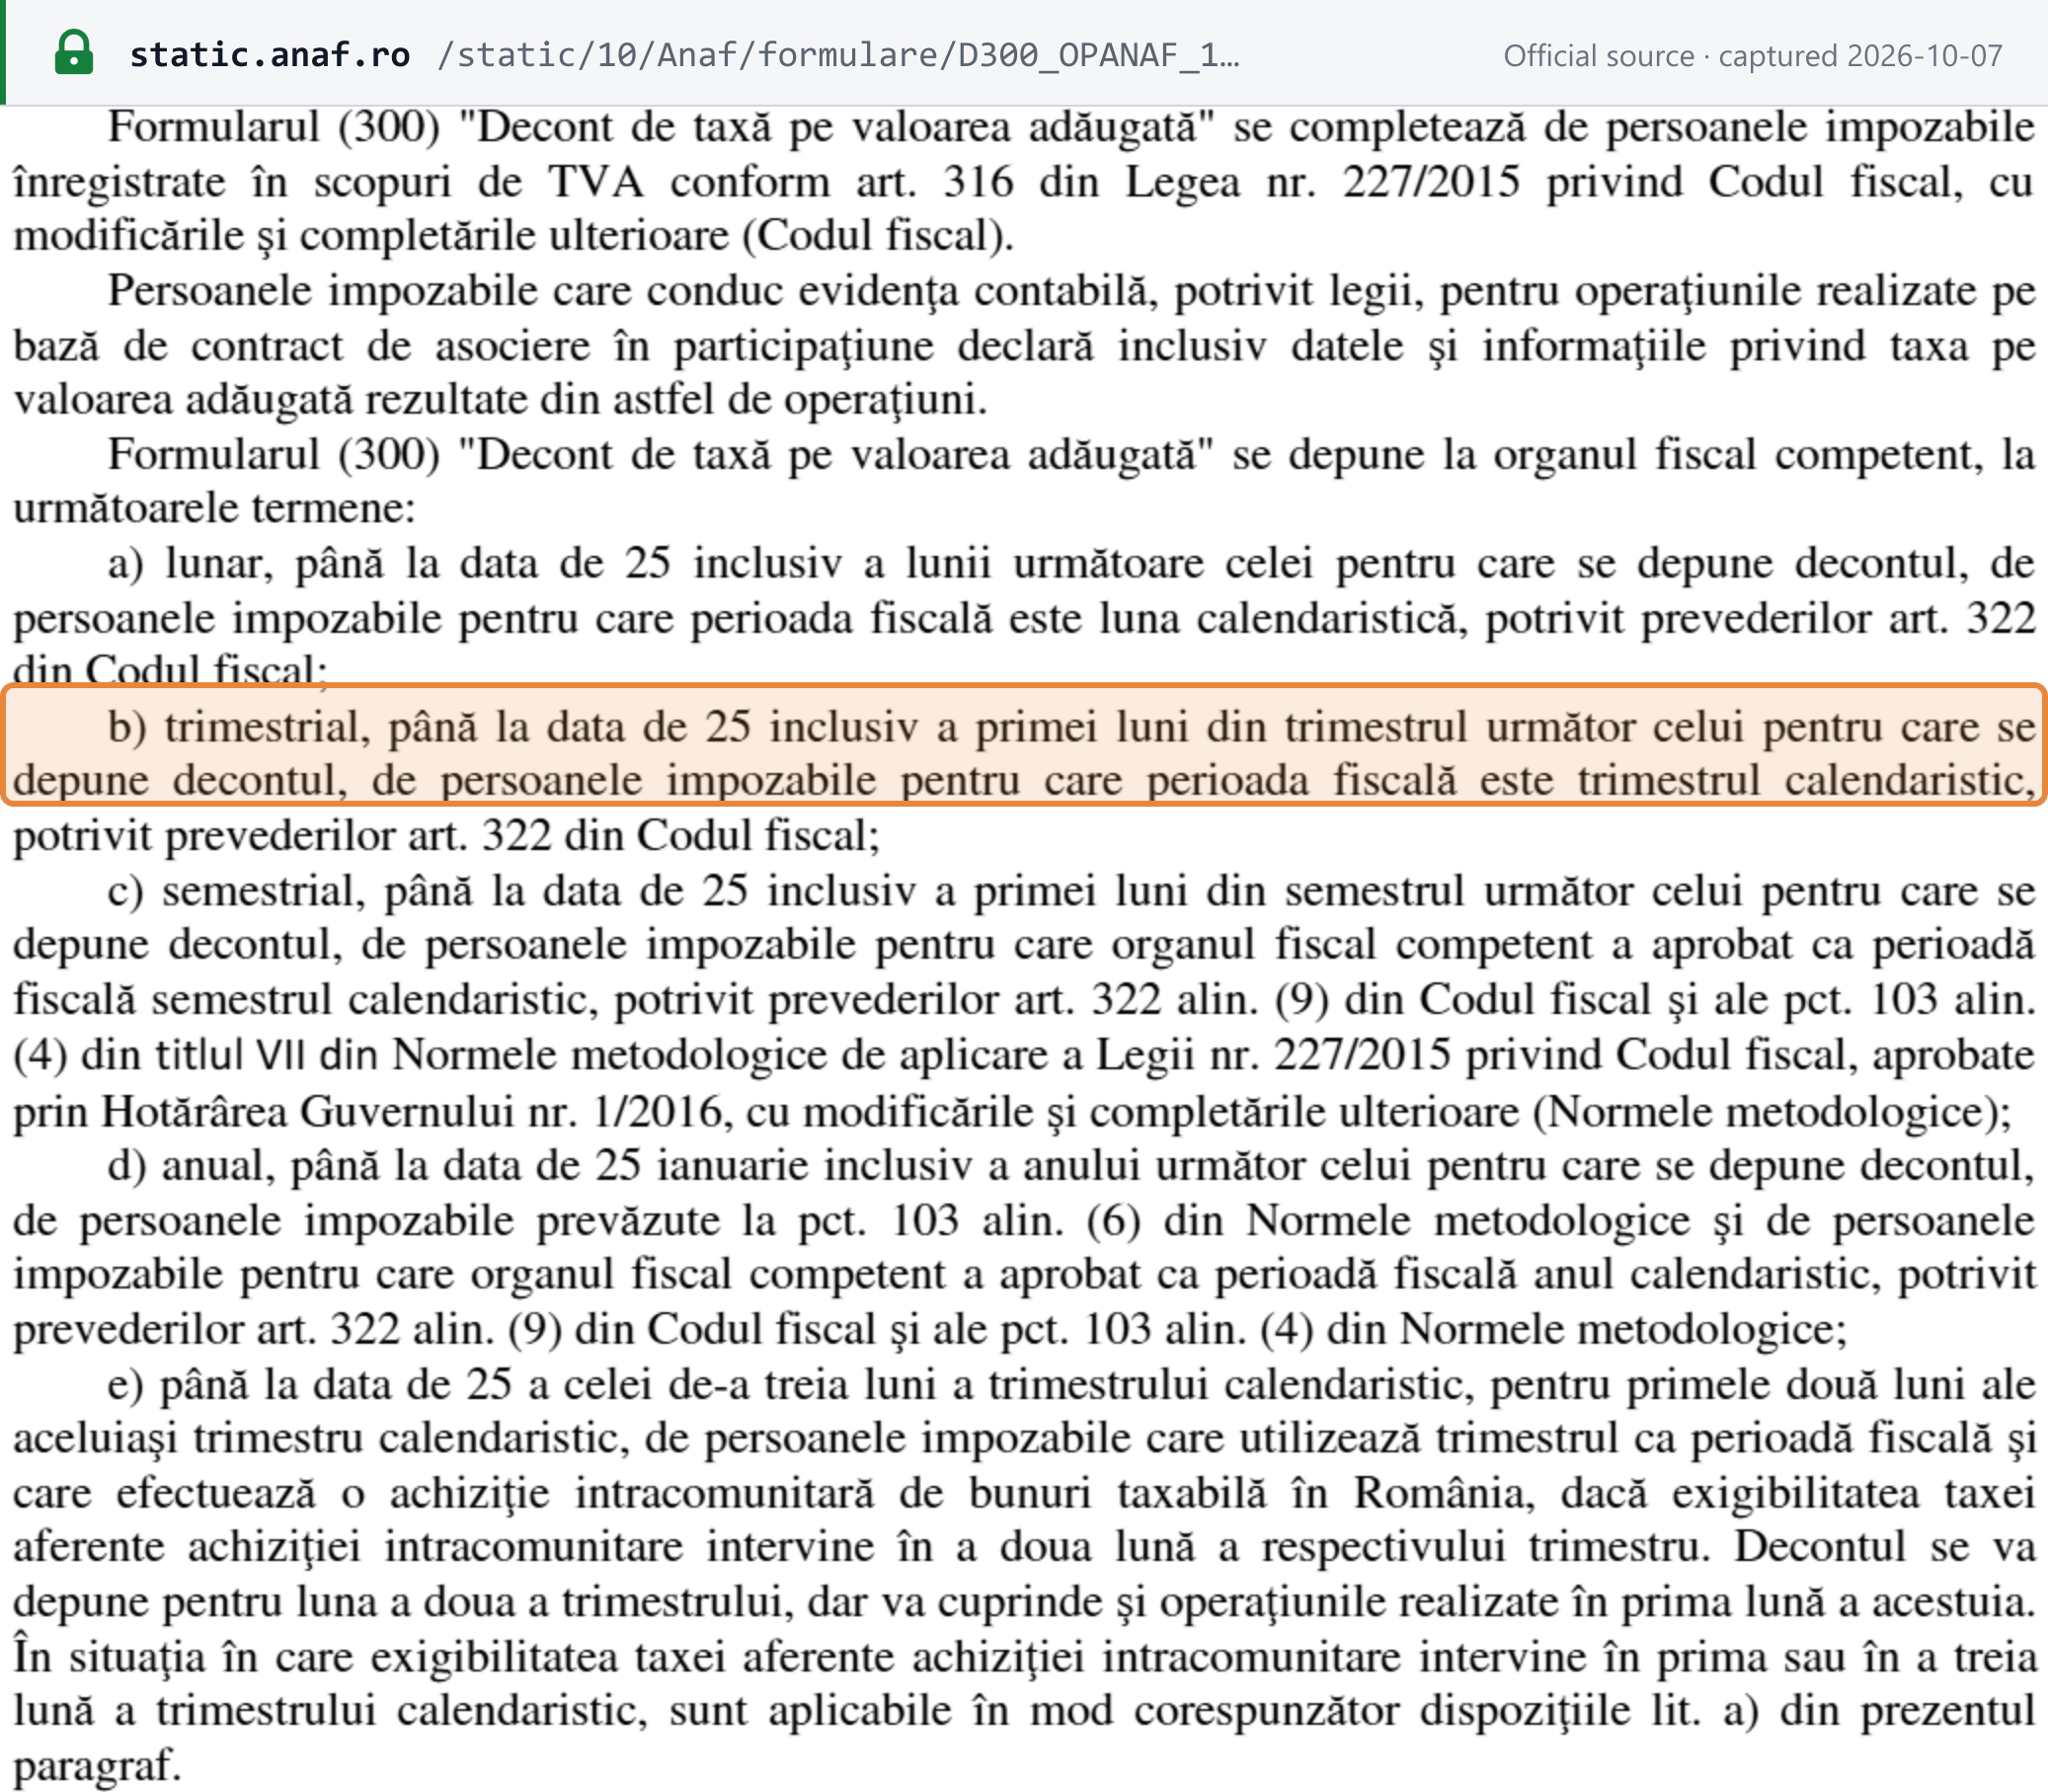
“b) trimestrial, până la data de 25 inclusiv a primei luni din trimestrul următor celui pentru care se depune decontul”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Decont de taxă pe valoarea adăugată (D300) — quarterly deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Declarație de mențiuni privind cifra de afaceri — quarterly filers, by 25 January

Taxa pe valoarea adăugată (TVA) · Annually · other

25th January each year Verified 2026-10-07
Who files
VAT-registered persons filing quarterly under art. 322(2) and (5) of the Fiscal Code, except those asking to be removed from the VAT register to use the small-business exemption
Notes
Quarterly filing has to be reconfirmed every year. By 25 January a quarterly filer must declare last year's turnover and state that it made no intra-EU acquisitions of goods, which is what entitles it to stay on quarters. When 25 January falls on a weekend the declaration is due the next working day, as on Monday 26 January 2026; the next one is due Monday 25 January 2027.
Source
Legea nr. 227/2015 privind Codul fiscal — art. 322 alin. (6) (declarația de mențiuni a persoanelor cu perioadă fiscală trimestrială) (consolidated edition published by ANAF, updated to OUG nr. 38/2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
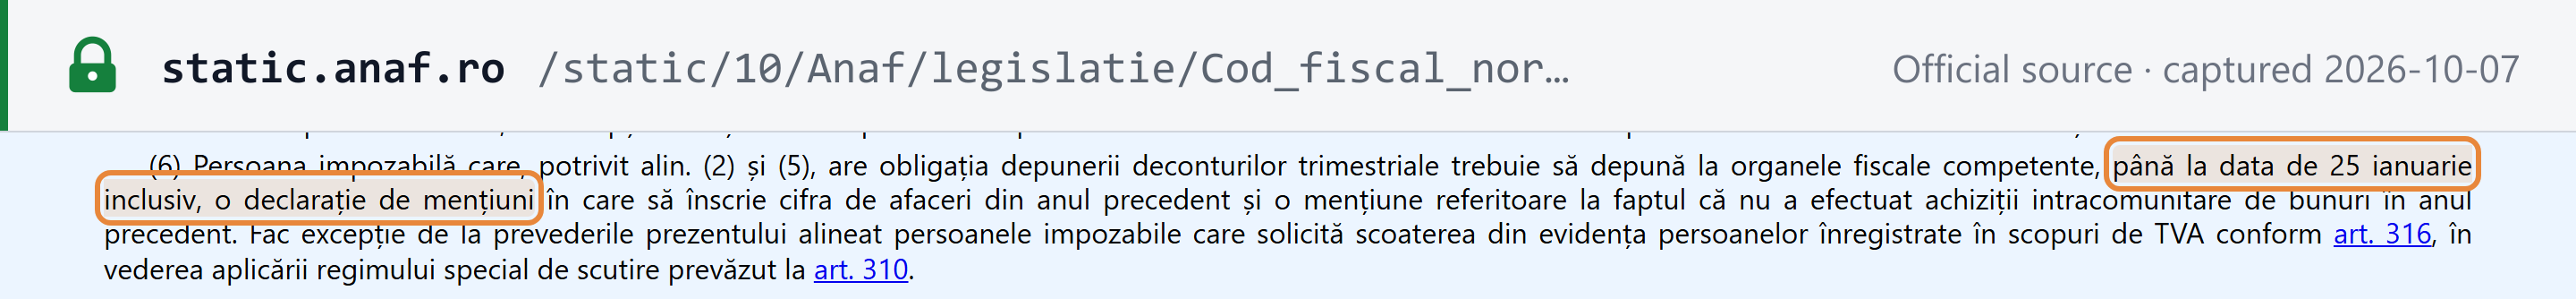
“până la data de 25 ianuarie inclusiv, o declarație de mențiuni în care să înscrie cifra de afaceri din anul precedent”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Declarație de mențiuni privind cifra de afaceri — quarterly filers, by 25 January deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Decont special de taxă (D301)

Taxa pe valoarea adăugată (TVA) · Monthly · return filing

25th of the month after the month ends — but the 21st in December (moved to the working day before if that is not a working day) Verified 2026-10-07
Who files
Persons not registered for VAT under art. 316 who owe Romanian VAT — on intra-EU acquisitions of goods, as the customer liable under the reverse charge, or on new means of transport — and only for months in which the tax became chargeable
Notes
A special return for people who are not registered for VAT under the normal rules but still owe Romanian VAT — typically on intra-EU purchases of goods, or as the customer who must account for the tax under the reverse charge. It is due by the 25th of the month after the tax became chargeable, only for months in which it did, and the tax is paid by the same date. The December rule that brings the VAT return forward to the 21st catches this return too. Buyers of a new means of transport from another member state file before registering the vehicle instead.
Source
Legea nr. 227/2015 privind Codul fiscal — art. 324 alin. (2) (decontul special de taxă) (consolidated edition published by ANAF, updated to OUG nr. 38/2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
“se depune până la data de 25 inclusiv a lunii următoare celei în care ia naștere exigibilitatea operațiunilor menționate la alin. (1). Decontul special de taxă trebuie depus numai pentru perioadele în care ia naștere exigibilitatea taxei.”
Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Declarație recapitulativă (D390 VIES) — EC Sales List

Taxa pe valoarea adăugată (TVA) · Monthly · report / listing

25th of the month after the month ends Verified 2026-10-07
Who files
Persons registered under art. 316 or 317 making intra-EU supplies or acquisitions of goods, B2B services to or from other member states, triangular supplies or call-off-stock movements — for each month in which such an operation became chargeable
Notes
The recapitulative statement of intra-EU goods, B2B services, triangulation and call-off stock is due by the 25th of the month after the month in which the tax became chargeable. It is filed only for months with such operations — there is no nil statement — and there is no quarterly option. It is not brought forward to 21 December the way the VAT return is: ANAF dated the November 2023 statement 27 December, and the November 2026 statement falls on Monday 28 December after the Christmas holidays and a weekend.
Source
ANAF — Calendarul obligațiilor fiscale pentru anul 2026, Formularul 390 VIES Agenția Națională de Administrare Fiscală (ANAF)
See the source text
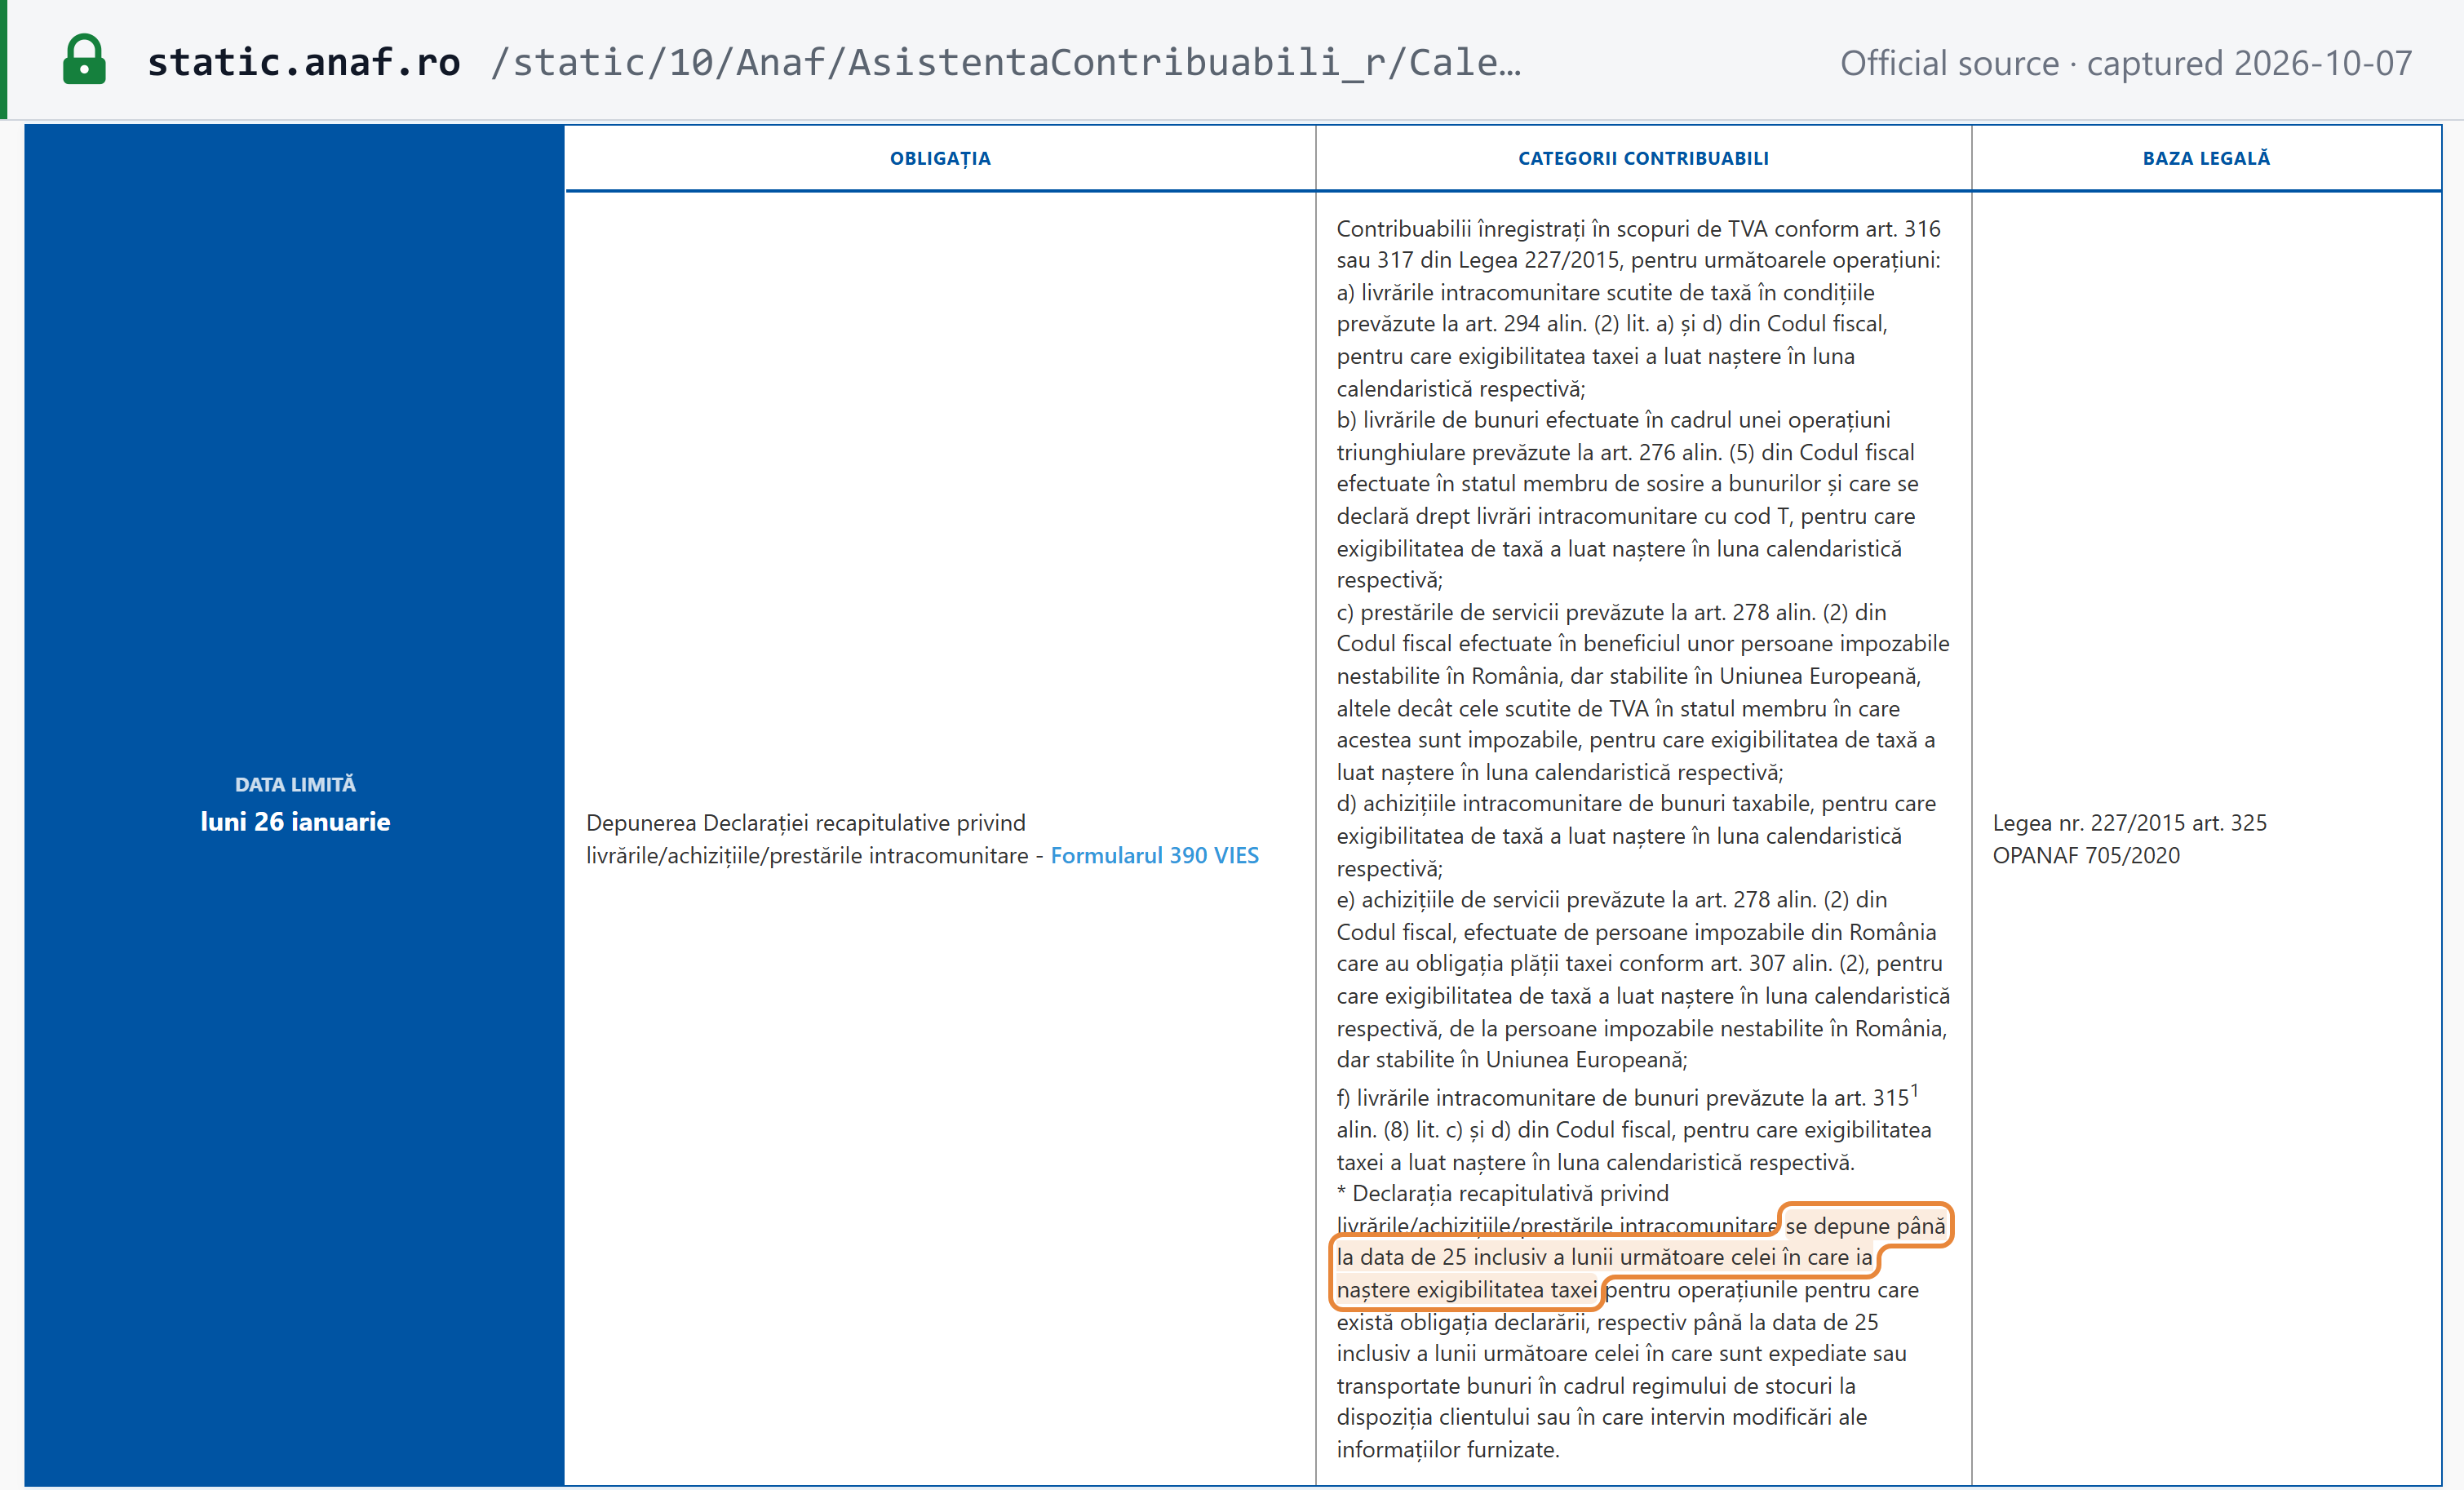
“se depune până la data de 25 inclusiv a lunii următoare celei în care ia naștere exigibilitatea taxei pentru operațiunile pentru care există obligația declarării”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Declarație recapitulativă (D390 VIES) — EC Sales List deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Declarație informativă privind livrările/prestările și achizițiile pe teritoriul național (D394) — monthly

Taxa pe valoarea adăugată (TVA) · Monthly · report / listing

30th of the month after the month ends Verified 2026-10-07
Who files
Every person registered for VAT under art. 316 whose VAT period is the month, reporting domestic supplies and purchases
Notes
Romania's domestic sales-and-purchases statement is filed by every VAT-registered business by the 30th of the month after its VAT period, and it is due even for a period with no operations at all. January's statement is due on the last day of February. Holiday clusters push it furthest: the April 2026 statement was due Tuesday 2 June, after a weekend that was also Pentecost and the 1 June holiday, and October 2026's falls on Wednesday 2 December, after the 30 November and 1 December holidays.
Source
OPANAF nr. 77/2022 — Anexa 2 pct. 2, instrucțiuni de completare a declarației informative 394 Agenția Națională de Administrare Fiscală (ANAF)
See the source text
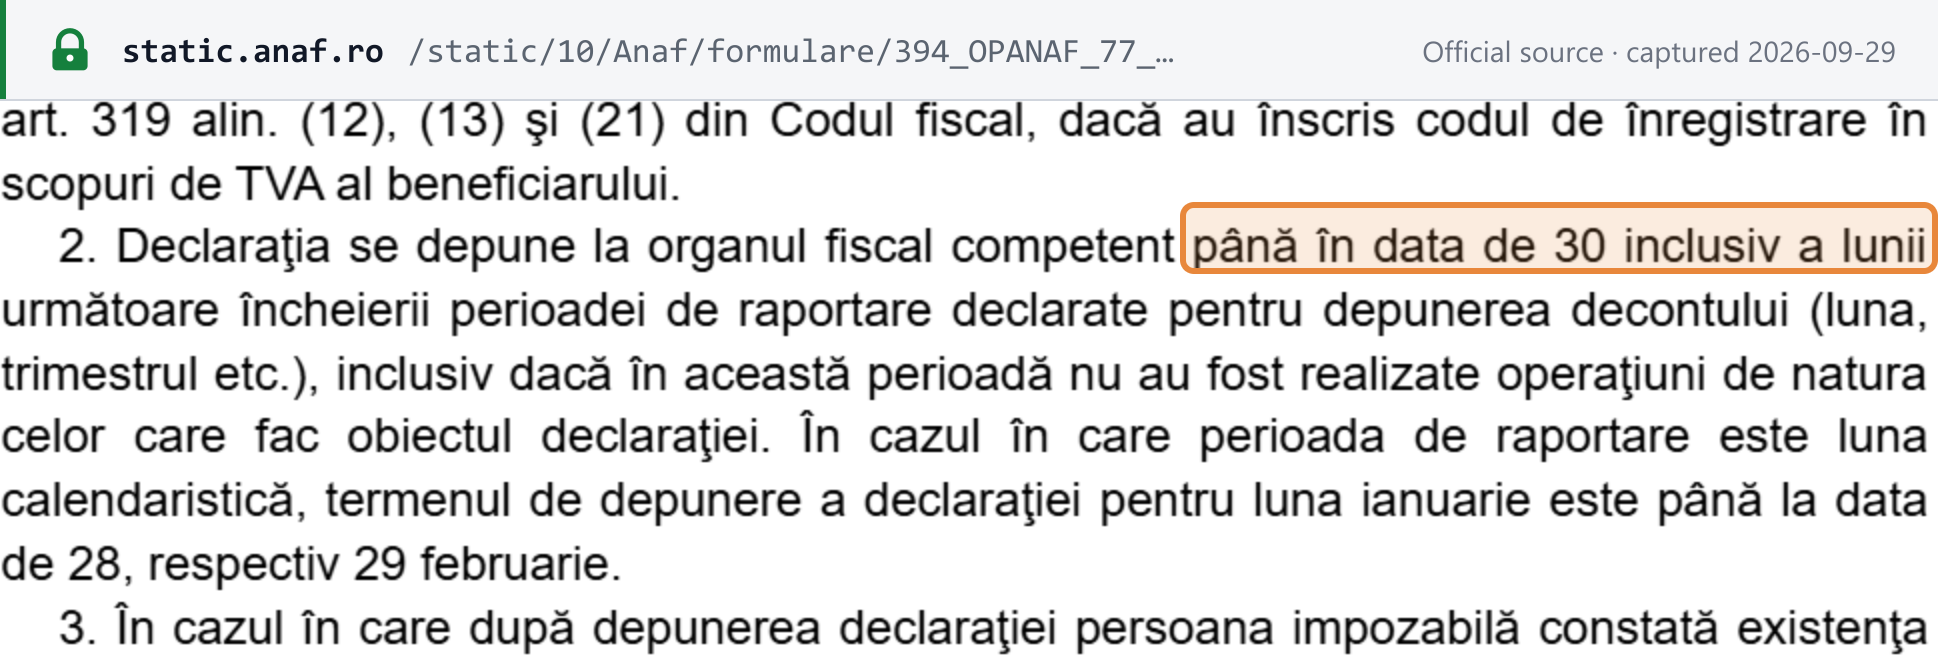
“până în data de 30 inclusiv a lunii următoare încheierii perioadei de raportare declarate pentru depunerea decontului (luna, trimestrul etc.), inclusiv dacă în această perioadă nu au fost realizate operaţiuni de natura celor care fac obiectul declaraţiei.”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Declarație informativă privind livrările/prestările și achizițiile pe teritoriul național (D394) — monthly deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Declarație informativă privind livrările/prestările și achizițiile pe teritoriul național (D394) — quarterly

Taxa pe valoarea adăugată (TVA) · Quarterly · report / listing

30th of the month after the quarter ends Verified 2026-10-07
Who files
Persons registered for VAT under art. 316 whose VAT period is the calendar quarter
Notes
Quarterly VAT filers file this statement quarterly too, by the 30th of the month after the quarter: 30 October 2026, then Monday 1 February 2027 because 30 January is a Saturday, then Tuesday 4 May because Orthodox Easter runs from Friday 30 April to Monday 3 May. The period always follows your VAT return's and cannot be chosen separately, and a nil statement is still due.
Source
OPANAF nr. 77/2022 — Anexa 2 pct. 2, instrucțiuni de completare a declarației informative 394 Agenția Națională de Administrare Fiscală (ANAF)
See the source text
“până în data de 30 inclusiv a lunii următoare încheierii perioadei de raportare declarate pentru depunerea decontului (luna, trimestrul etc.), inclusiv dacă în această perioadă nu au fost realizate operaţiuni de natura celor care fac obiectul declaraţiei.”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Declarație informativă privind livrările/prestările și achizițiile pe teritoriul național (D394) — quarterly deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Declarație informativă D406 (SAF-T) — monthly

Taxa pe valoarea adăugată (TVA) — fișierul standard de control fiscal · Monthly · report / listing

last day of the month after the month ends Verified 2026-10-07
Who files
Companies and other taxpayers in scope of SAF-T (including non-residents holding a Romanian VAT number since 1 January 2025) whose VAT period is the month; sole traders, liberal professions and public institutions are exempt
Notes
The SAF-T file is due by the last day of the month after the reporting period, and that period follows your VAT period, so monthly VAT filers report monthly. A last day on a weekend or holiday moves forward, as September 2026's does to Monday 2 November. Companies and non-residents with a Romanian VAT number file it; sole traders, the liberal professions and public institutions do not. The fixed-assets section is filed once a year with the annual financial statements, and the inventory section only when ANAF asks, with at least 30 days to answer. New filers get a few months' grace from penalties.
Source
OPANAF nr. 1783/2021 — Anexa 4 pct. 1 (termenele de transmitere a fișierului standard de control fiscal, D406) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
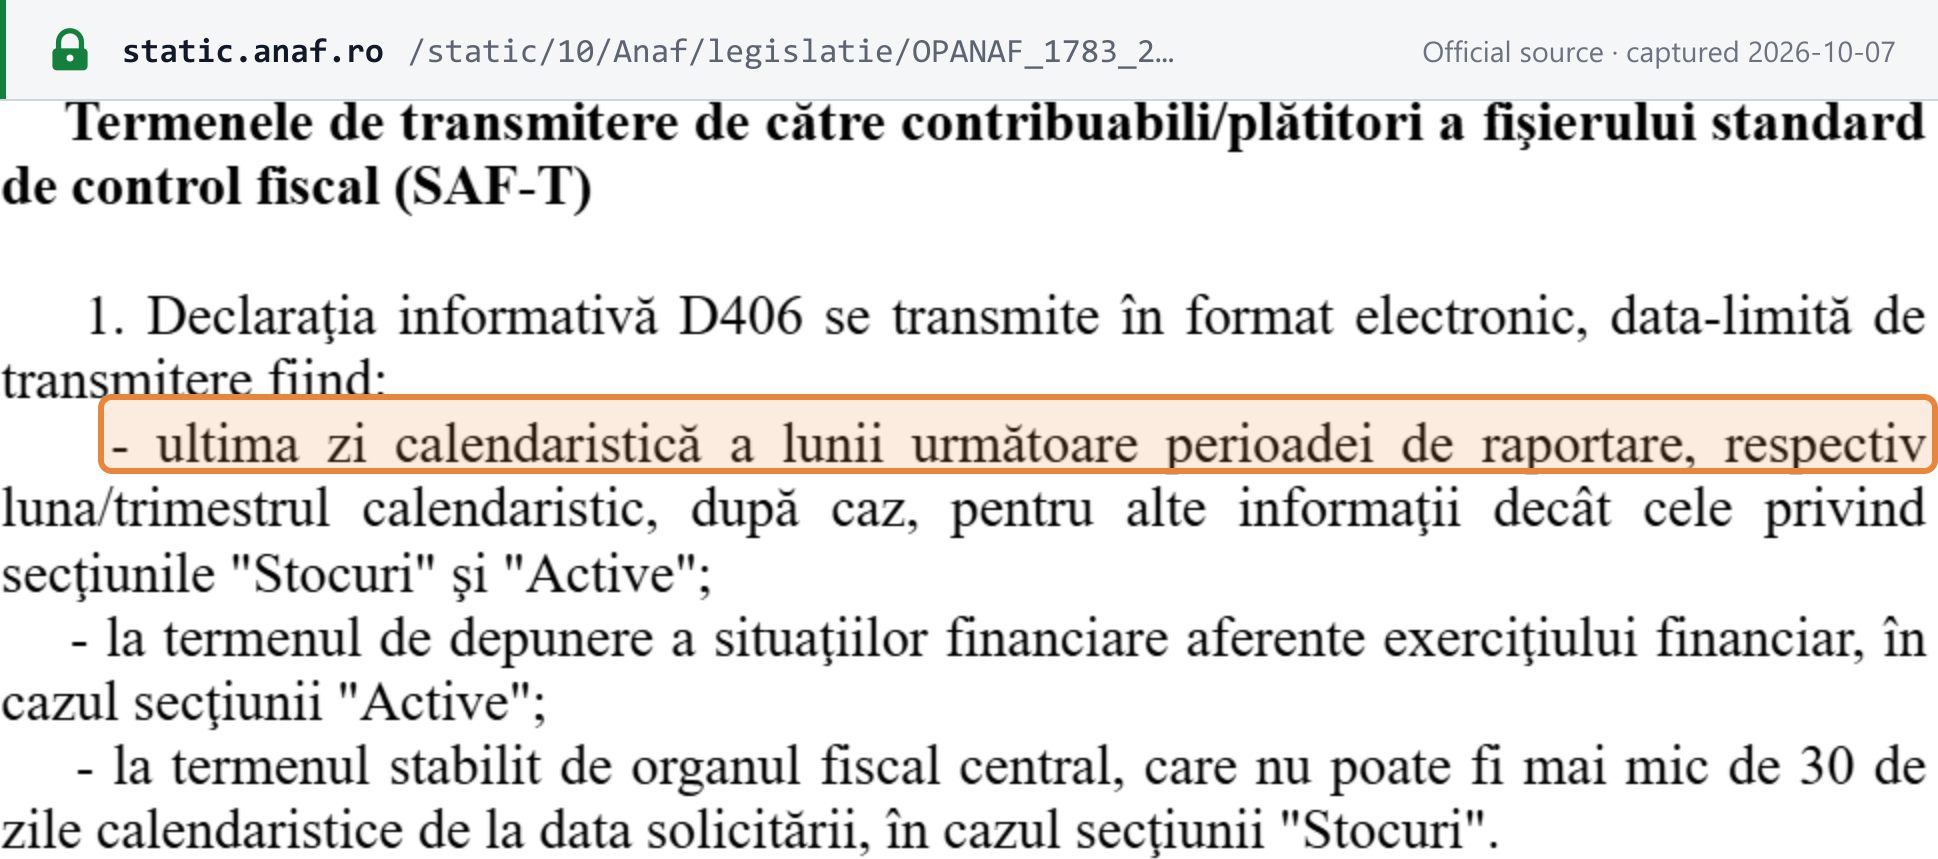
“ultima zi calendaristică a lunii următoare perioadei de raportare, respectiv luna/trimestrul calendaristic, după caz”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Declarație informativă D406 (SAF-T) — monthly deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Declarație informativă D406 (SAF-T) — quarterly

Taxa pe valoarea adăugată (TVA) — fișierul standard de control fiscal · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-07
Who files
SAF-T filers whose VAT period is the quarter, the half-year or the year, and taxpayers in scope who are not registered for VAT at all
Notes
Quarterly VAT filers report SAF-T every quarter, and so does any business in scope that is not registered for VAT, along with those on a half-yearly or annual VAT period. The deadline is the last day of the month after the quarter, moved forward off a non-working day: Q3 2026 is due Monday 2 November and Q4 on Monday 1 February 2027. A first quarterly file has a three-month grace period before penalties apply.
Source
OPANAF nr. 1783/2021 — Anexa 4 pct. 1 (termenele de transmitere a fișierului standard de control fiscal, D406) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
“ultima zi calendaristică a lunii următoare perioadei de raportare, respectiv luna/trimestrul calendaristic, după caz”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Declarație informativă D406 (SAF-T) — quarterly deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
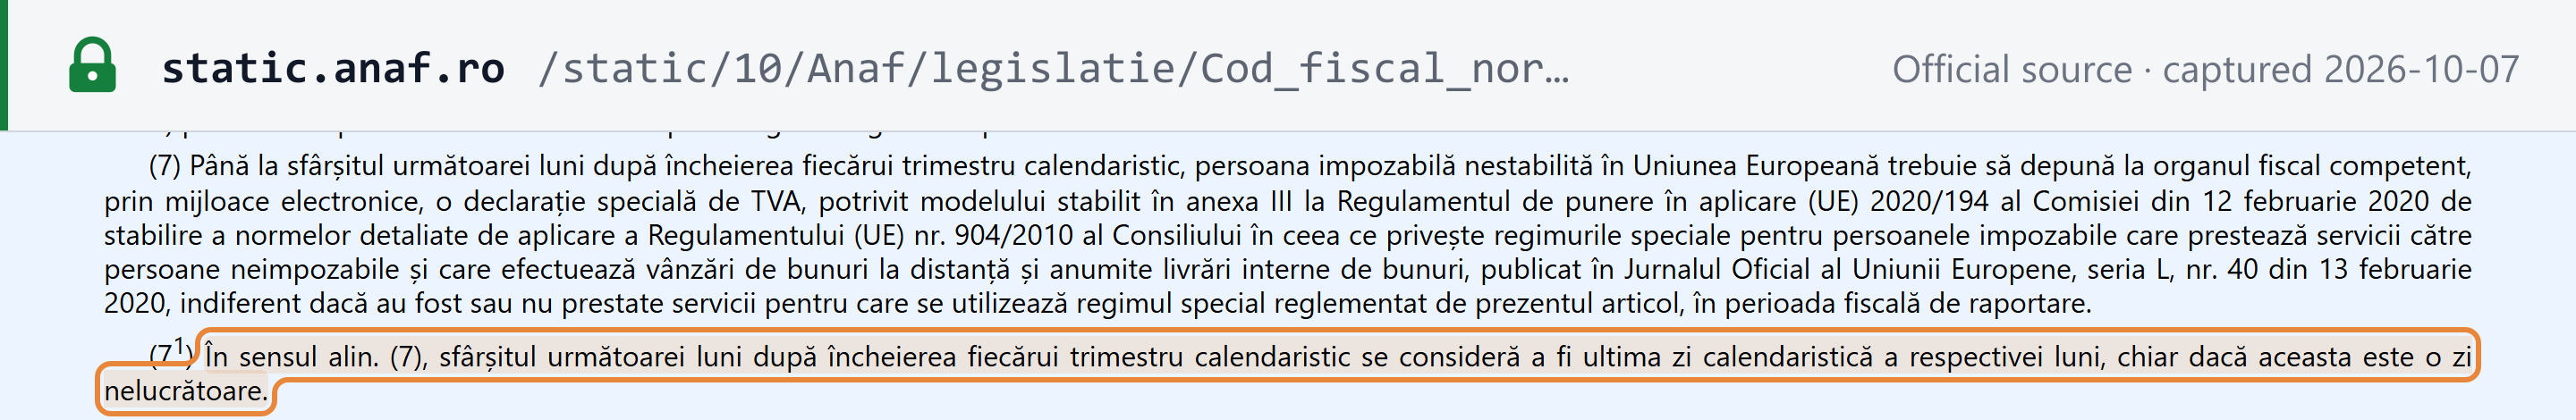
Declarație specială de TVA (formular 398) — OSS Union scheme

Taxa pe valoarea adăugată (TVA) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-07
Who files
Taxable persons using the Union OSS scheme with Romania as member state of identification, for intra-EU distance sales of goods, certain domestic supplies by platforms and B2C services
Notes
Quarterly return and payment, due by the end of the month after the quarter and owed even for a quarter with no supplies, where Romania is your member state of identification. This date does not move: the Fiscal Code says the last calendar day counts even when it is a non-working day, so Saturday 31 October 2026 and Sunday 31 January 2027 stand. The domestic VAT return for September 2026 moves to Monday 26 October, but this return stays on Saturday 31 October.
Source
Legea nr. 227/2015 privind Codul fiscal — art. 315 alin. (6) și (6^1) (regimul special pentru vânzările intracomunitare de bunuri la distanță și serviciile către persoane neimpozabile) (consolidated edition published by ANAF, updated to OUG nr. 38/2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
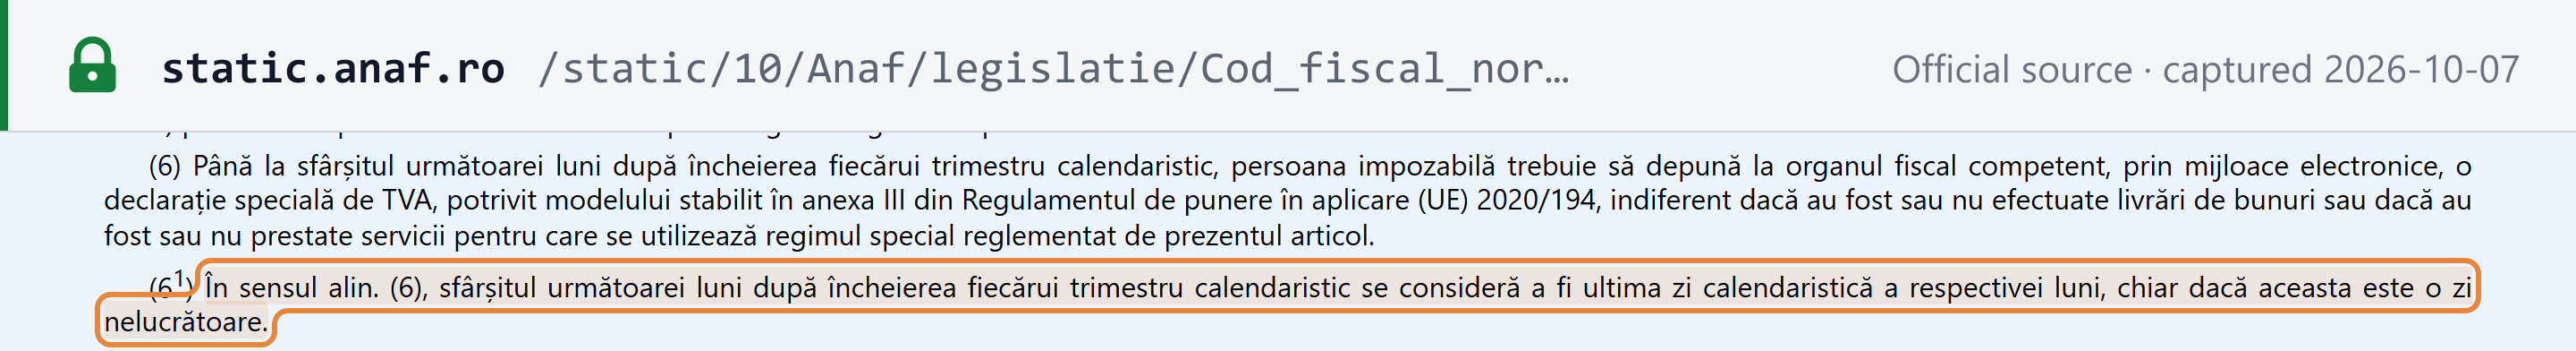
“În sensul alin. (6), sfârșitul următoarei luni după încheierea fiecărui trimestru calendaristic se consideră a fi ultima zi calendaristică a respectivei luni, chiar dacă aceasta este o zi nelucrătoare.”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Declarație specială de TVA (formular 398) — OSS Union scheme deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
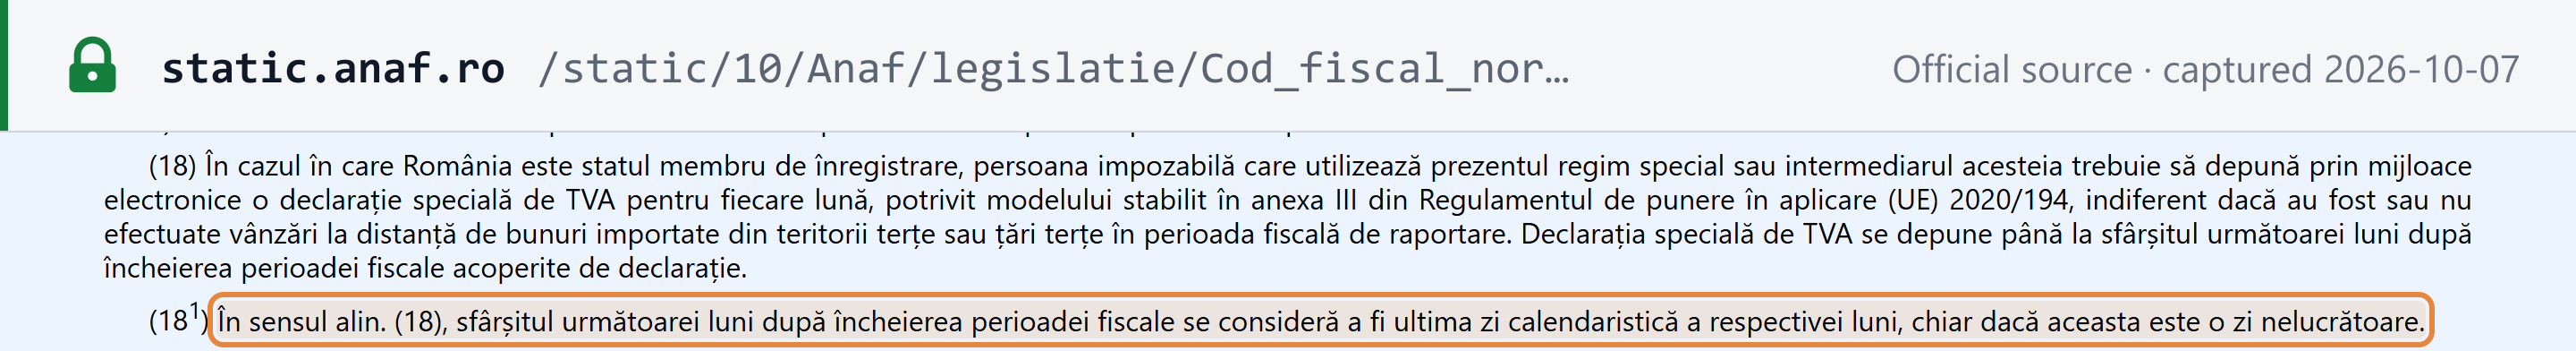
Declarație specială de TVA (formular 398) — OSS non-Union scheme

Taxa pe valoarea adăugată (TVA) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-07
Who files
Taxable persons not established in the EU supplying services to EU consumers, with Romania as member state of identification
Notes
For businesses established outside the EU that supply services to EU consumers and are identified in Romania. It runs on the same quarterly cycle as the Union scheme with the same fixed date — the last day of the month after the quarter, whether or not that is a working day — and a return is due even for a quarter with no supplies.
Source
Legea nr. 227/2015 privind Codul fiscal — art. 314 alin. (7) și (7^1) (regimul special pentru serviciile prestate de persoane impozabile nestabilite în Uniunea Europeană) (consolidated edition published by ANAF, updated to OUG nr. 38/2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
“În sensul alin. (7), sfârșitul următoarei luni după încheierea fiecărui trimestru calendaristic se consideră a fi ultima zi calendaristică a respectivei luni, chiar dacă aceasta este o zi nelucrătoare.”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Declarație specială de TVA (formular 398) — OSS non-Union scheme deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
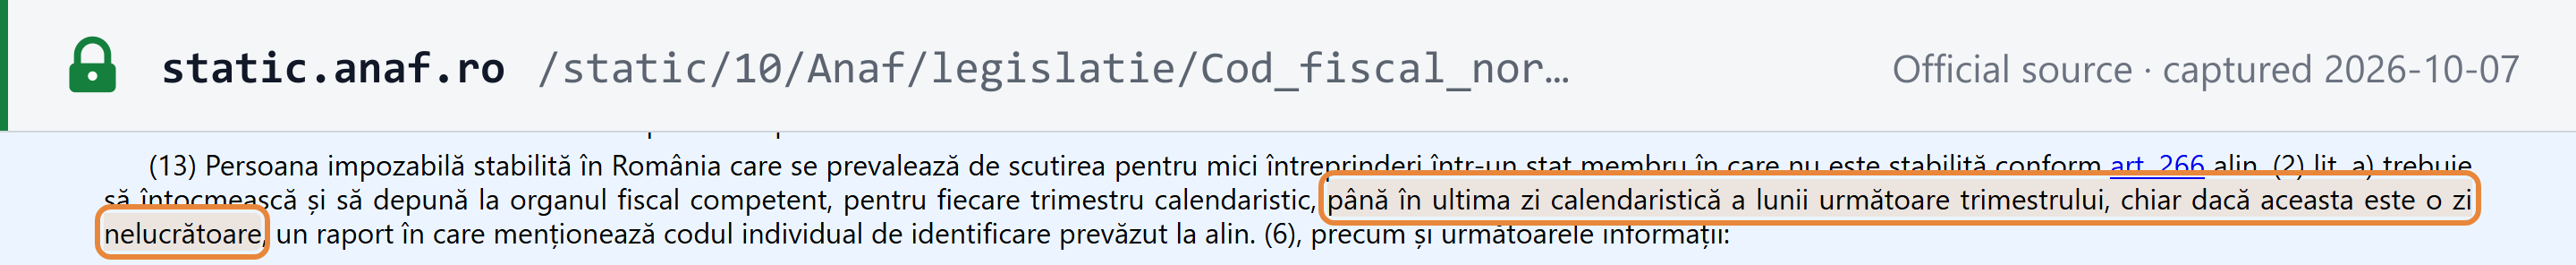
Declarație specială de TVA (formular 398) — IOSS import scheme

Taxa pe valoarea adăugată (TVA) — Import One Stop Shop · Monthly · return filing

last day of the month after the month ends Verified 2026-10-07
Who files
Taxable persons, or their intermediaries, using the import scheme for distance sales of goods imported in consignments up to EUR 150, with Romania as member state of identification
Notes
The import scheme is monthly rather than quarterly, which is the slip to avoid if you use more than one One-Stop-Shop scheme. The return is due by the end of the following month, nil months included, and the last day counts even on a weekend: ANAF published Saturday 28 February and Sunday 31 May 2026 as live deadlines.
Source
Legea nr. 227/2015 privind Codul fiscal — art. 315^2 alin. (18) și (18^1) (regimul special pentru vânzarea la distanță de bunuri importate) (consolidated edition published by ANAF, updated to OUG nr. 38/2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
“În sensul alin. (18), sfârșitul următoarei luni după încheierea perioadei fiscale se consideră a fi ultima zi calendaristică a respectivei luni, chiar dacă aceasta este o zi nelucrătoare.”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Declarație specială de TVA (formular 398) — IOSS import scheme deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Raport trimestrial — EU cross-border small-enterprise exemption

Taxa pe valoarea adăugată (TVA) — regimul special de scutire pentru întreprinderile mici · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-07
Who files
Romania-established taxable persons using the small-enterprise exemption in another member state (EX-suffix identification number), under the EUR 100,000 Union turnover ceiling
Notes
If your Romanian business uses the small-enterprise exemption in other member states, you report quarterly by the last calendar day of the following month, weekend or not, entering 0 where nothing was supplied. Pass the EUR 100,000 EU-wide turnover ceiling and you have 15 working days to tell ANAF.
Source
Legea nr. 227/2015 privind Codul fiscal — art. 310^1 alin. (13) (raportul trimestrial al întreprinderii mici care aplică scutirea în alte state membre) (consolidated edition published by ANAF, updated to OUG nr. 38/2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
“pentru fiecare trimestru calendaristic, până în ultima zi calendaristică a lunii următoare trimestrului, chiar dacă aceasta este o zi nelucrătoare, un raport”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Raport trimestrial — EU cross-border small-enterprise exemption deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07
Declarație specială de TVA lunară — special mechanism for imports (art. 315^3)

Taxa pe valoarea adăugată (TVA) la import · Monthly · return filing

16th of the month after the month ends Verified 2026-10-07
Who files
Persons presenting goods to customs on behalf of the consignee — couriers, postal operators, customs agents — who are authorised to use the special mechanism for declaring and paying import VAT on consignments outside IOSS
Notes
Carriers and customs agents who present low-value consignments on the consignee's behalf, collect the VAT from the consignee and pay it to customs, file a monthly special VAT declaration with the customs authority. The declaration and the VAT collected in the month are due by the deferred customs payment date — at the latest the 16th of the following month.
Source
Legea nr. 227/2015 privind Codul fiscal — art. 315^3 alin. (6) (mecanismul special pentru declararea și plata TVA la import) (consolidated edition published by ANAF, updated to OUG nr. 38/2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
“Persoana care prezintă bunurile în vamă trebuie să depună declarația specială de TVA și să plătească TVA încasată în luna calendaristică de raportare până la termenul de plată aplicabil plății taxelor la import care fac obiectul amânării plății, respectiv cel târziu în a șaisprezecea zi a lunii următoare lunii calendaristice de raportare.”
Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07

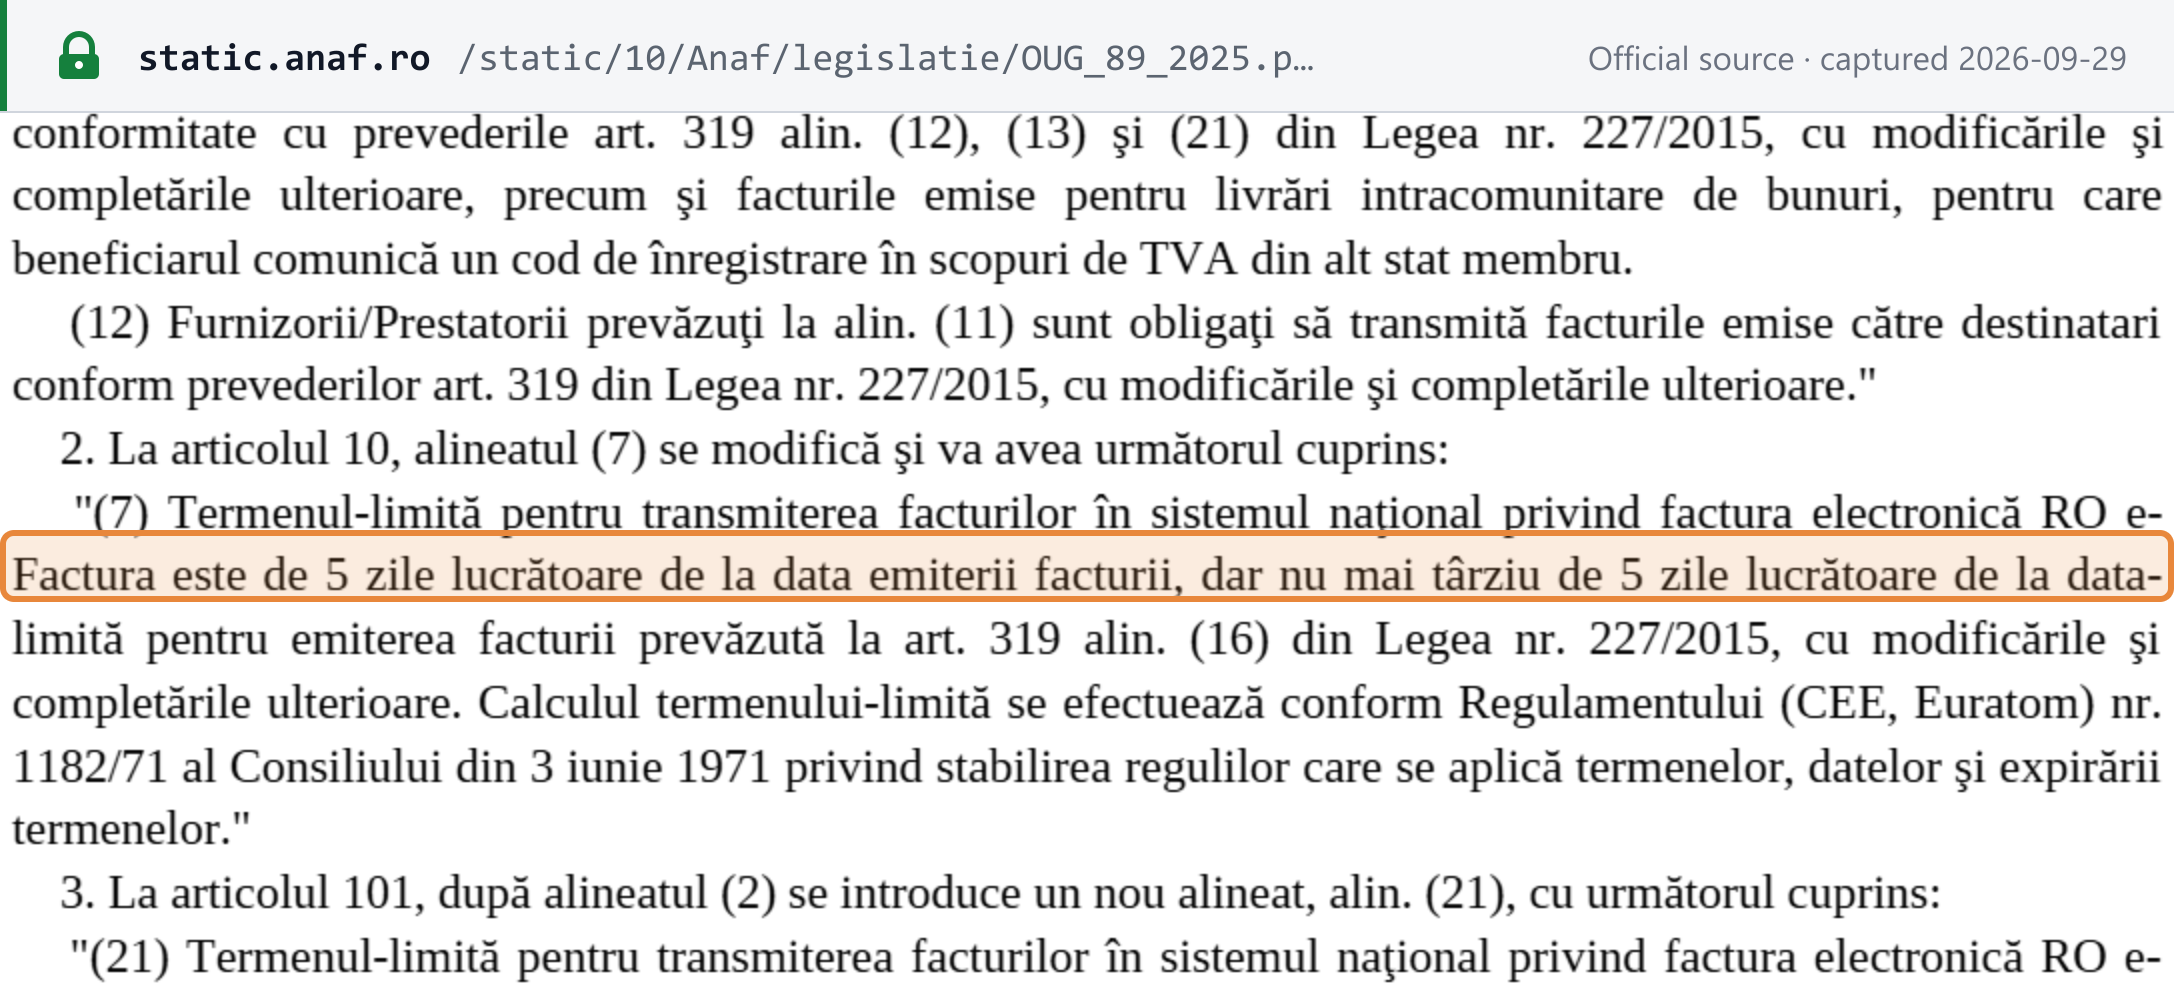
RO e-Factura — transmission of invoices

Taxa pe valoarea adăugată (TVA) — facturare electronică · One-off · other

within 5 business days of the invoice issue date Verified 2026-10-07
Who files
Suppliers issuing invoices in scope of RO e-Factura: B2B and B2G between Romania-established persons, B2C since 1 January 2025, and since 1 January 2026 supplies to non-established persons registered for Romanian VAT
Notes
Invoices in scope must reach RO e-Factura within five working days of the invoice date — and in any event no later than five working days after the legal deadline for issuing the invoice, which is the 15th of the month after the chargeable event. The window was five calendar days until the end of 2025. Late transmission is fined for each calendar month. RO e-TVA is a pre-filled return that ANAF produces; since 1 January 2026 it sets no reply deadline for you.
Source
OUG nr. 89/2025 — art. X pct. 2 (art. 10 alin. (7) din OUG nr. 120/2021, în vigoare de la 1 ianuarie 2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
“este de 5 zile lucrătoare de la data emiterii facturii”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the RO e-Factura — transmission of invoices deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07

VAT registration on crossing the RON 395,000 ceiling

Taxa pe valoarea adăugată (TVA) · One-off · registration

no later than the day of crossing the RON 395,000 calendar-year turnover ceiling Verified 2026-10-07
Who files
Romania-established taxable persons using the small-business exemption whose calendar-year turnover exceeds RON 395,000 (the ceiling since 1 September 2025)
Notes
A Romanian small business must apply for VAT registration no later than the day its turnover for the year passes RON 395,000, and the normal VAT regime applies from the transaction that takes it over. There is no grace period after the event. Register late and ANAF registers you ex officio from the crossing date and assesses the VAT you should have charged. Businesses not established in Romania have no threshold: they must register before their first operation giving a right to deduct, unless the customer accounts for the VAT or they use a One-Stop-Shop scheme.
Source
Legea nr. 227/2015 privind Codul fiscal — art. 316 alin. (1) lit. b) (înregistrarea în scopuri de TVA la depășirea plafonului de scutire) (consolidated edition published by ANAF, updated to OUG nr. 38/2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
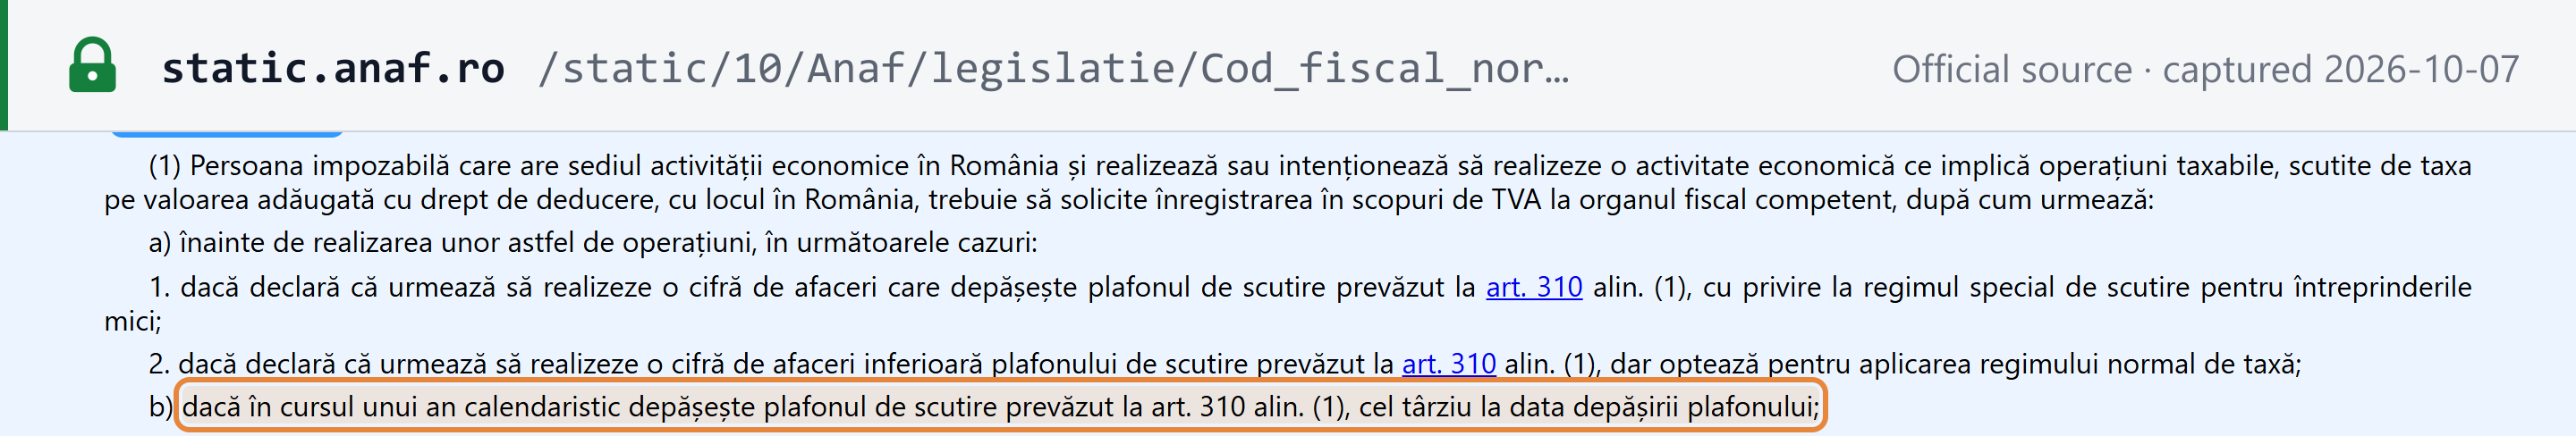
“dacă în cursul unui an calendaristic depășește plafonul de scutire prevăzut la art. 310 alin. (1), cel târziu la data depășirii plafonului;”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the VAT registration on crossing the RON 395,000 ceiling deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07

Notice of cessation for removal from the VAT register

Taxa pe valoarea adăugată (TVA) · One-off · registration

within 15 days of ceasing operations giving a right of deduction, or ceasing economic activity Verified 2026-10-07
Who files
Persons registered for VAT under art. 316 who stop making operations giving a right of deduction, or stop their economic activity
Notes
Stop making supplies that carry a right to deduct, or stop trading altogether, and you have 15 days to tell ANAF in writing so it can take you off the VAT register. Changes to your registration details carry the same 15 days. Once ANAF communicates a decision cancelling your registration, you owe one last VAT return, whatever your usual period, by the 25th of the following month.
Source
Legea nr. 227/2015 privind Codul fiscal — art. 316 alin. (20) (scoaterea din evidența persoanelor înregistrate în scopuri de TVA) (consolidated edition published by ANAF, updated to OUG nr. 38/2026) Agenția Națională de Administrare Fiscală (ANAF)
See the source text
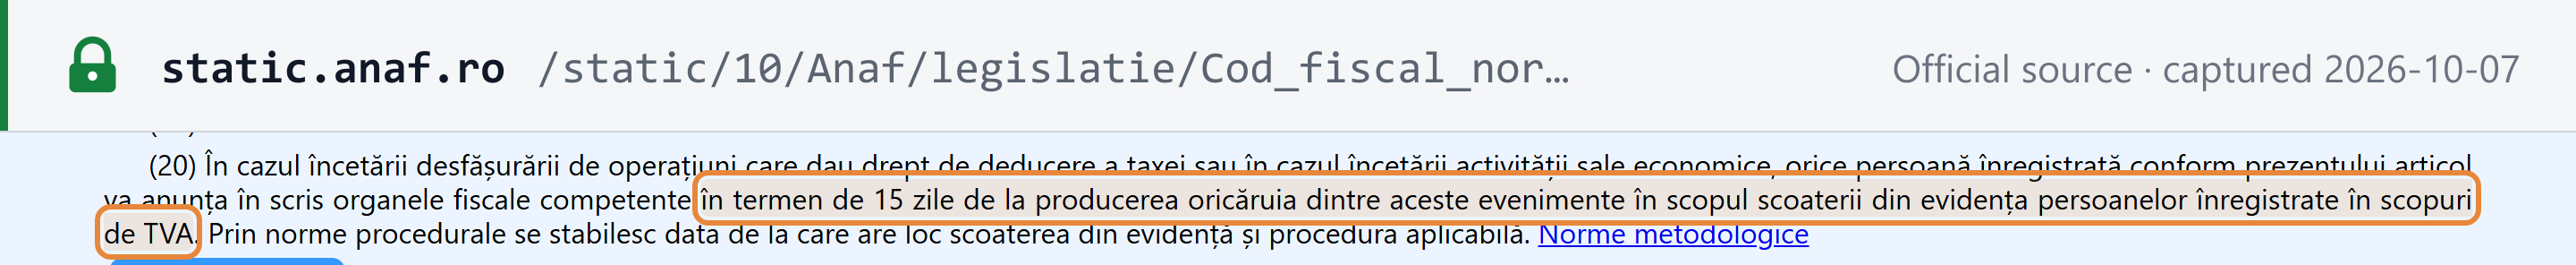
“va anunța în scris organele fiscale competente în termen de 15 zile de la producerea oricăruia dintre aceste evenimente în scopul scoaterii din evidența persoanelor înregistrate în scopuri de TVA.”
Screenshot of Agenția Națională de Administrare Fiscală (ANAF) showing the Notice of cessation for removal from the VAT register deadline Open full size Captured from Agenția Națională de Administrare Fiscală (ANAF) on 2026-10-07

Romanian deadlines move forward to the next working day when they fall on a Saturday, a Sunday or a public holiday — payments as well as filings. Two exceptions run the other way. A VAT return or payment that would fall due on 25 December is due on 21 December, or on the working day before it if the 21st is not a working day. And the One-Stop-Shop returns and the cross-border small-business report never move: the Fiscal Code makes the last calendar day of the month the deadline even when it is a non-working day. ANAF's 2026 calendar shows both behaviours side by side, moving the September VAT return to Monday 26 October while leaving the One-Stop-Shop return on Saturday 31 January. The holiday list is the Labour Code's, including 6 and 7 January, Orthodox Good Friday, Easter and Pentecost; a holiday falling on a weekend is not replaced by another day off. VAT is paid by the date the return is due. Not shown because they run from events or are not periodic: the RO e-Transport code required before each road shipment, the final VAT return after cancellation, and the forms for adjustments after deregistration (307) and for VAT collected while a VAT number is cancelled (311). Excise, the retail mark-up report, payroll and profit tax are out of scope.

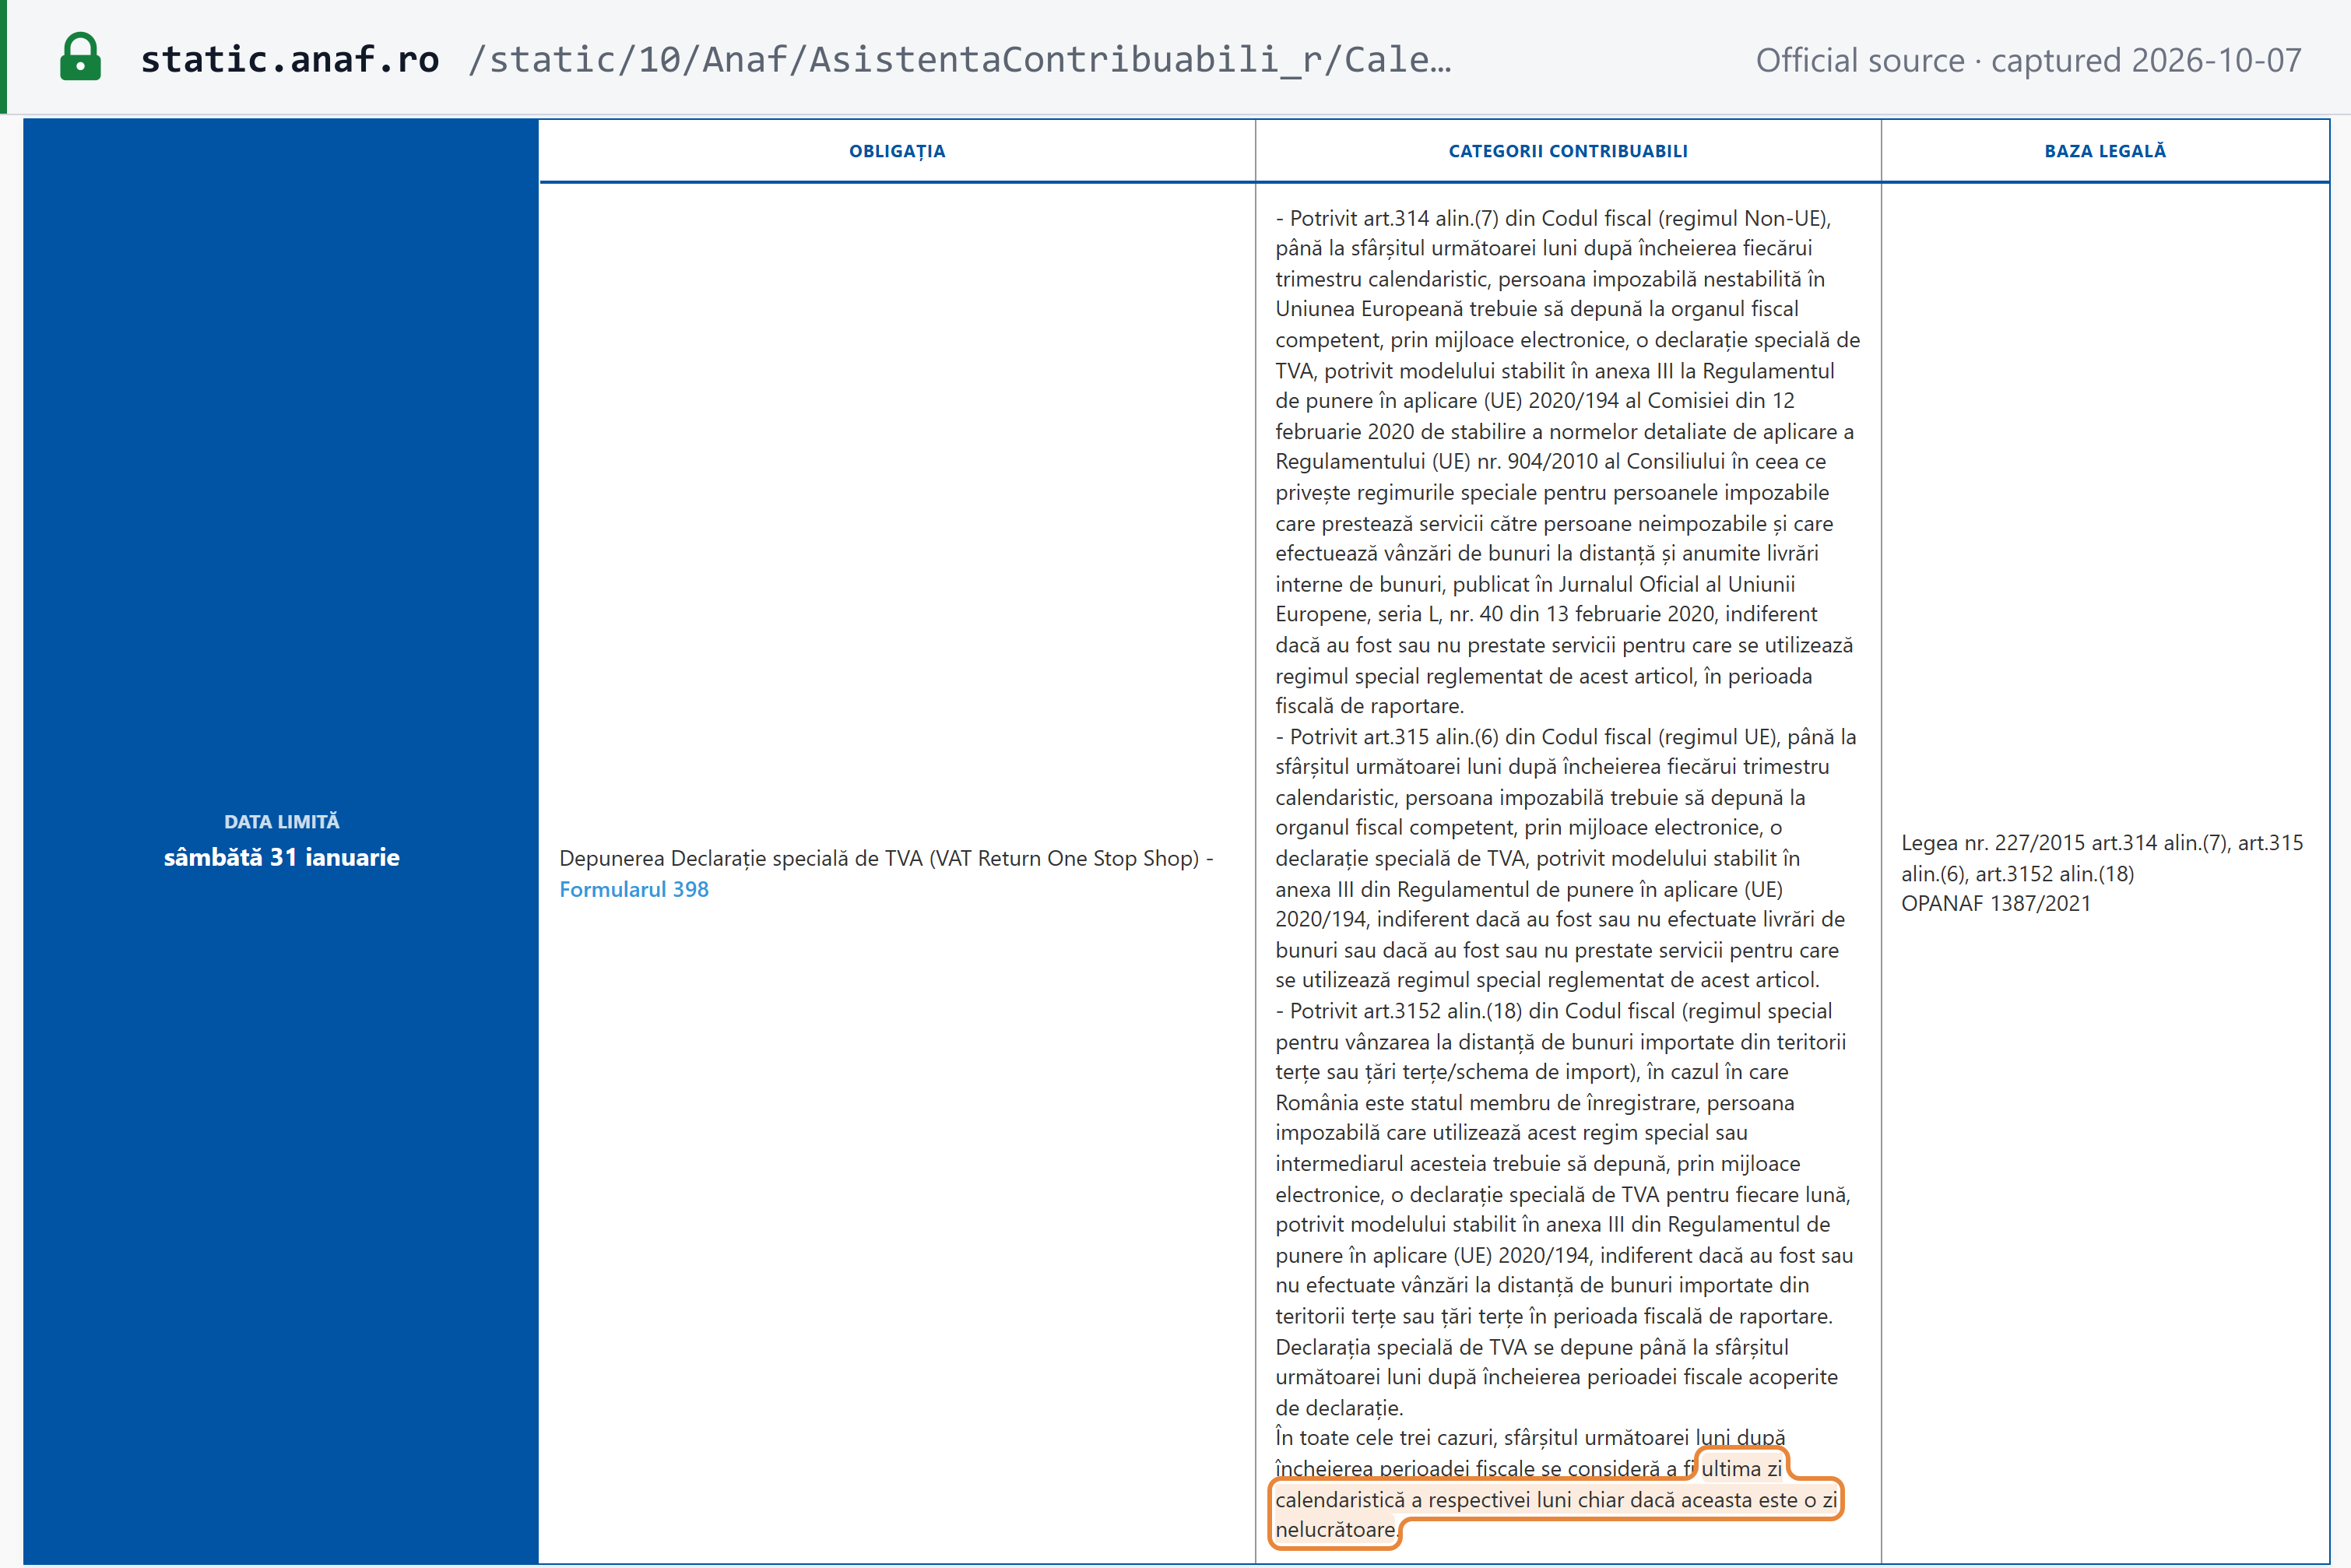
“În toate cele trei cazuri, sfârșitul următoarei luni după încheierea perioadei fiscale se consideră a fi ultima zi calendaristică a respectivei luni chiar dacă aceasta este o zi nelucrătoare.”
Screenshot of the official source stating the rule that governs Romania's deadlines
ANAF — Calendarul obligațiilor fiscale pentru anul 2026, Formularul 398 (VAT Return One Stop Shop) — Agenția Națională de Administrare Fiscală (ANAF), captured 2026-10-07

What this calendar does not list

  • Not yet covered Annual or reconciliation return — Romania has no annual VAT return. The annual notifications 392A, 392B and 393 are suspended until 31 December 2026; unless that suspension is extended again, the notification for 2026 is due 25 February 2027.

About this calendar

Which Romania tax deadlines does this calendar cover?

17 recurring indirect-tax obligations — Taxa pe valoarea adăugată (TVA) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-07). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.