Налоговая декларация по НДС — quarterly VAT return
Налог на добавленную стоимость (НДС / VAT) · Quarterly · return filing
25th of the month after the quarter ends Verified 2026-10-15- Who files
- Every VAT payer and every tax agent — including tax agents that are not themselves VAT payers or are exempt — and businesses outside VAT that issued an invoice showing VAT; one return per taxpayer at its place of registration, not per branch
- Notes
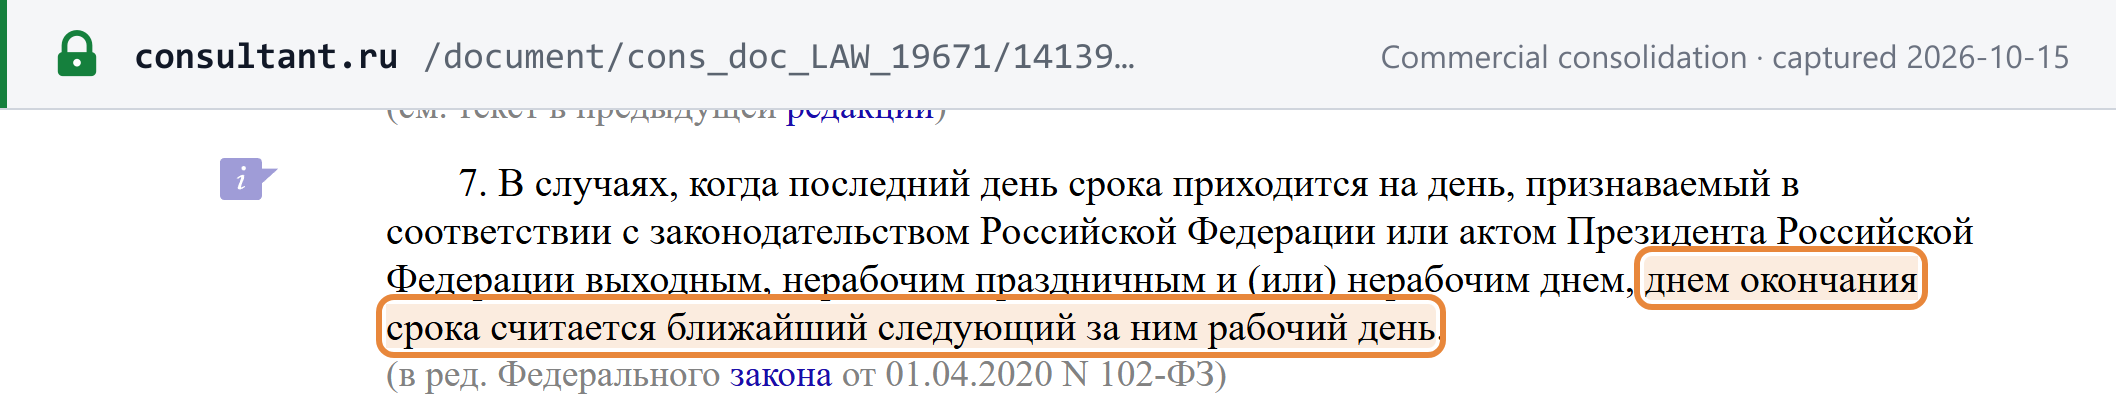
- The return for each calendar quarter is due by the 25th of the following month — for the third quarter of 2026, Monday 26 October, because the 25th is a Sunday. It can only be filed electronically through an EDI operator; a paper return counts as not filed. The purchase and sales ledgers go inside the return, and a nil return is due even for a quarter with no sales. A return more than 20 days late lets the FNS freeze the company’s bank accounts. A business with no transactions and no money moving through its accounts can file the single simplified declaration instead, by the 20th of the month after the quarter.
- Source
- Налоговый кодекс РФ, часть вторая — статья 174, пункт 5 (period: статья 163) КонсультантПлюс (commercial consolidation of the official text)
See the source text
“обязаны представить в налоговые органы по месту своего учета соответствующую налоговую декларацию по установленному формату в электронной форме по телекоммуникационным каналам связи через оператора электронного документооборота в срок не позднее 25-го числа месяца, следующего за истекшим налоговым периодом, если иное не предусмотрено настоящей главой.”
 Open full size Captured from КонсультантПлюс (commercial consolidation of the official text) on 2026-10-15