Slovenia compliance calendar

20 recurring Davek na dodano vrednost (DDV / VAT) and DDV (VAT) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Slovenia rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing Report / listing Payment Law change takes effect

Dates already include the weekend and public-holiday shift where Slovenia applies one — 11 of 20 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Obračun DDV (DDV-O) — monthly

Davek na dodano vrednost (DDV / VAT) · Monthly · return filing

last business day of the month after the month ends Verified 2026-10-13
Who files
VAT-identified taxable persons on the default calendar-month period that do not file the recapitulative statement (RP-O): everyone in their first 12 months after identification, businesses not established in Slovenia, VAT groups, and established businesses whose taxable turnover last year exceeded EUR 210,000
Notes
The deadline is the last working day of the following month, so when the month ends on a weekend or public holiday it comes earlier, not later: the September 2026 return is due Friday 30 October, because 31 October is both a Saturday and Reformation Day. In years when 31 October falls on a weekday it is still a holiday, so the deadline is the 30th or earlier (Friday 29 October in 2027). A return is due even for a month with nothing to pay. Files of the output and input VAT records are due by the same day.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 88. člen (1)-(3), 89. člen PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Če ni s tem zakonom drugače določeno, mora davčni zavezanec obračun DDV predložiti davčnemu organu do zadnjega delovnega dne naslednjega meseca po poteku davčnega obdobja.”
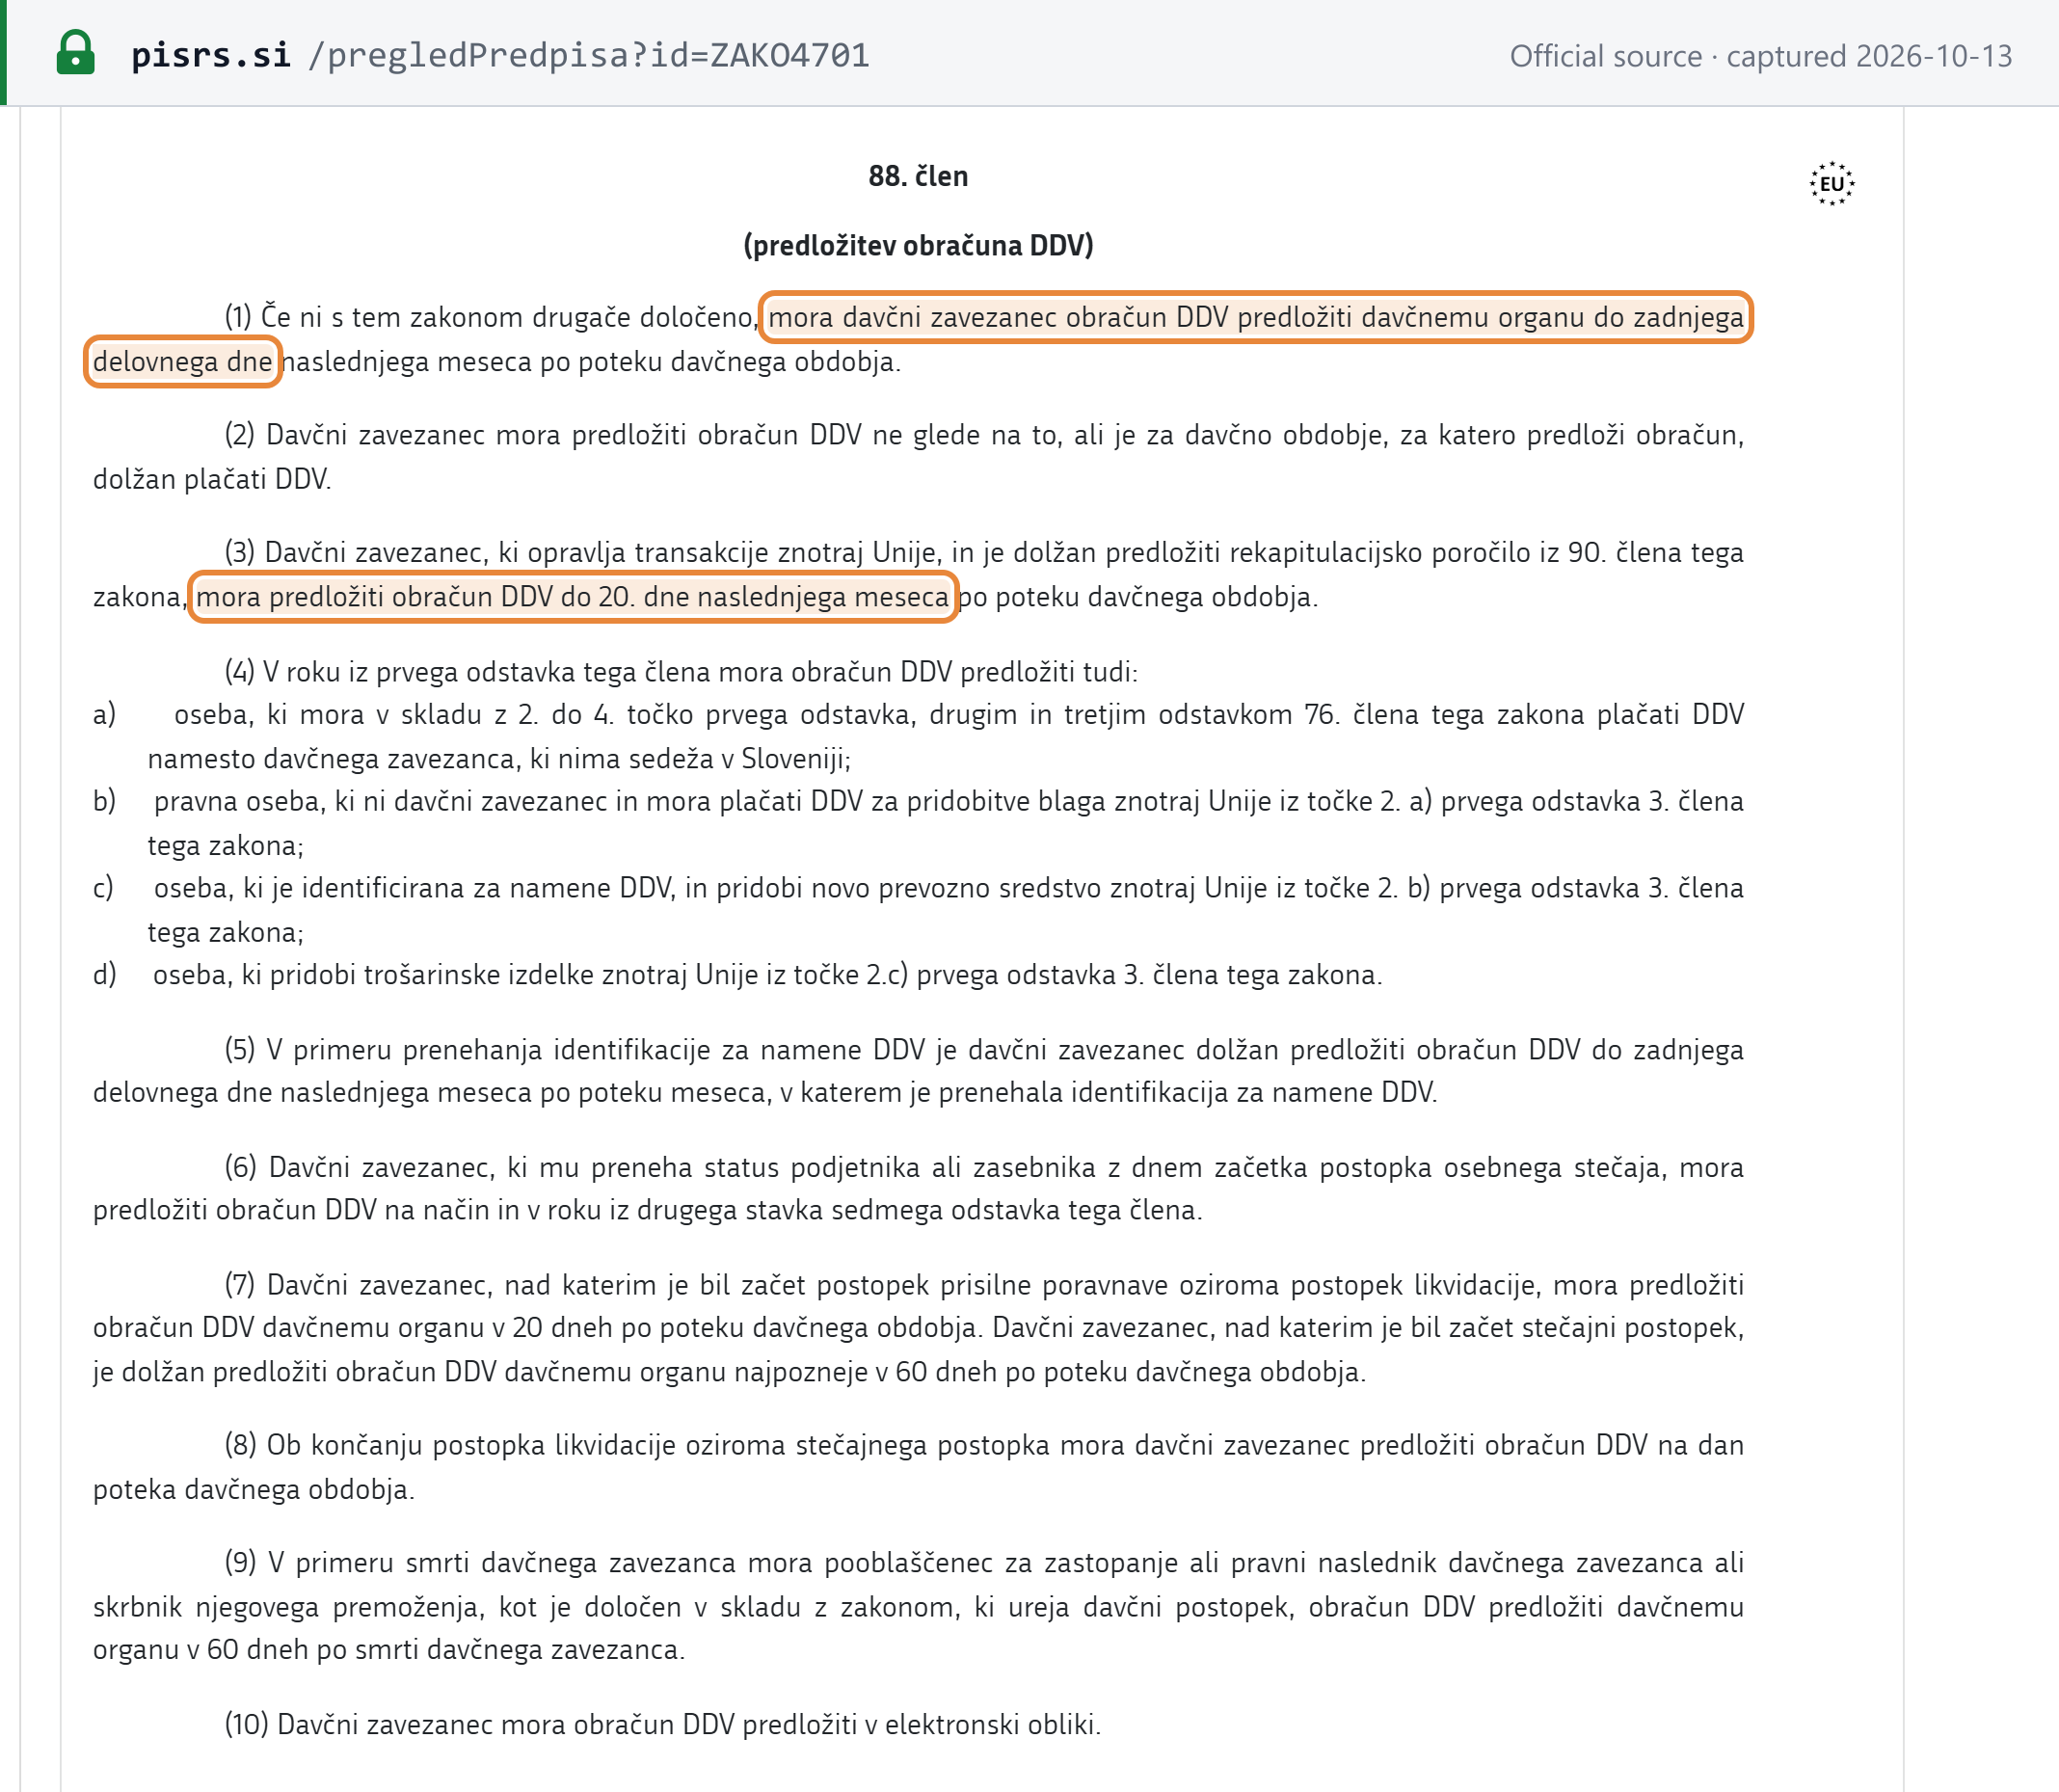
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Obračun DDV (DDV-O) — monthly deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Obračun DDV (DDV-O) — quarterly

Davek na dodano vrednost (DDV / VAT) · Quarterly · return filing

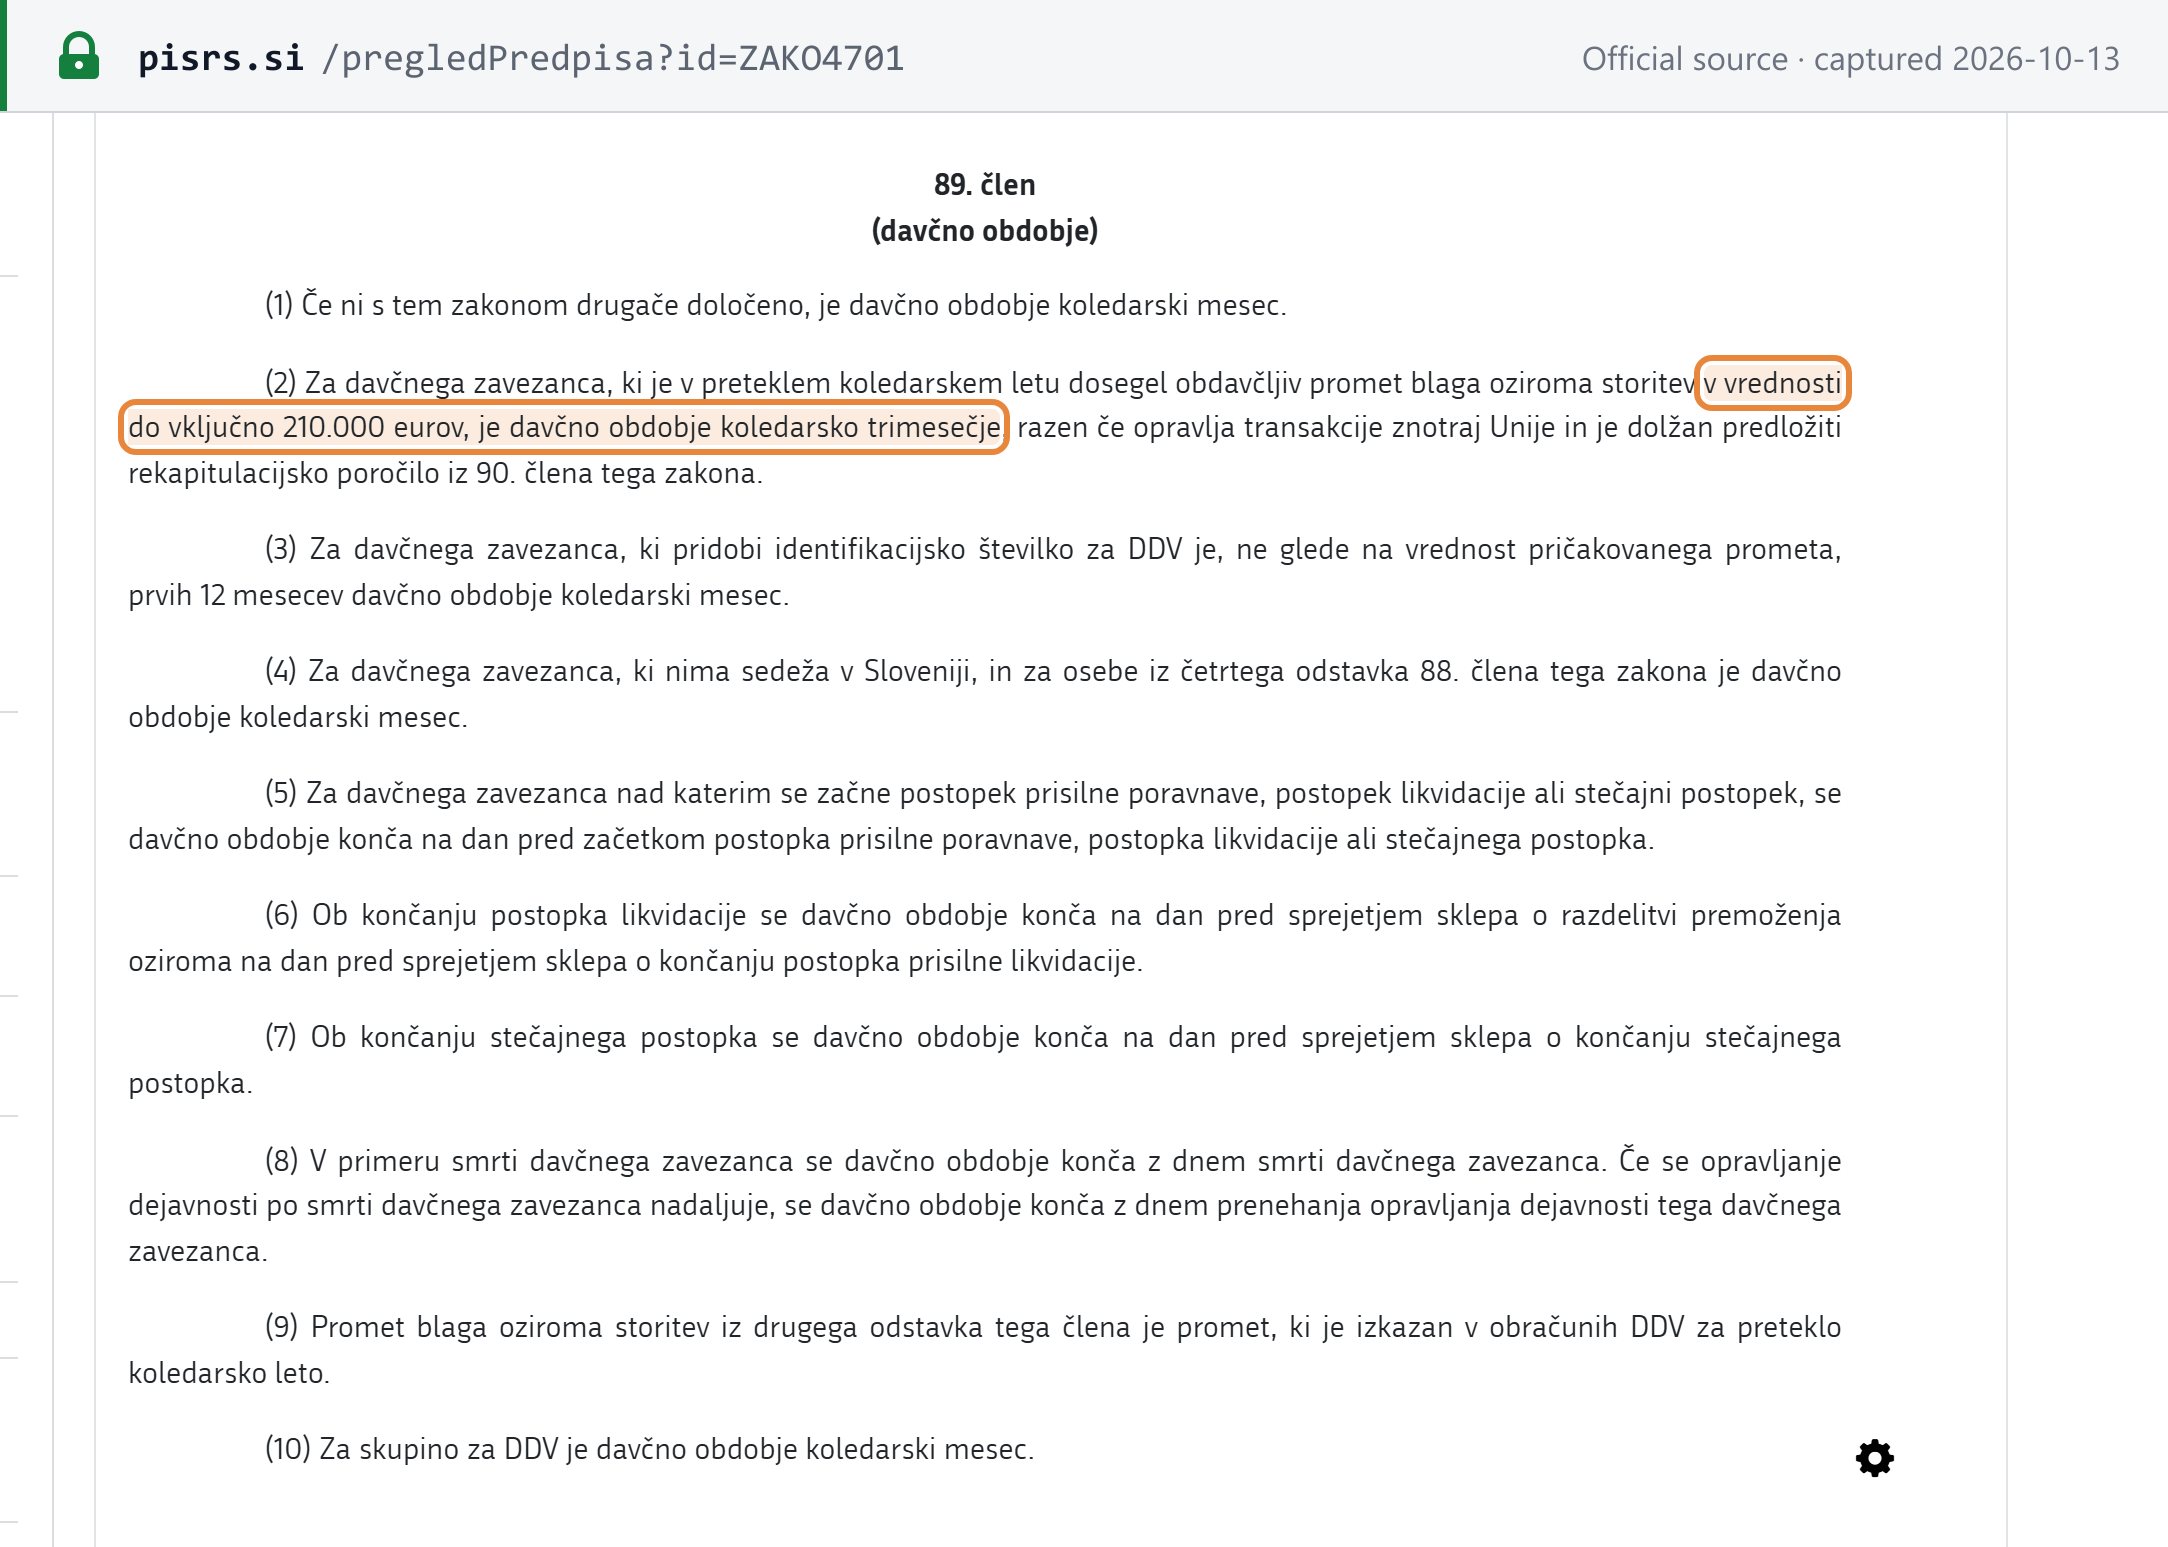
last business day of the month after the quarter ends Verified 2026-10-13
Who files
Established taxable persons whose taxable turnover shown in last year's VAT returns was EUR 210,000 or less and who make no intra-EU transactions requiring a recapitulative statement — automatically, not by election. Never in the first 12 months after identification, never for businesses not established in Slovenia or for VAT groups
Notes
Quarterly filing follows from the law once last year's turnover is EUR 210,000 or less; you do not apply for it. Starting intra-EU sales of goods or services that need a recapitulative statement takes you out of it and onto monthly returns. Quarters are calendar quarters and the return is due by the last working day of the next month. The third-quarter return never falls on 31 October, which is a public holiday every year: in 2028 it is due Monday 30 October.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 89. člen (2), 88. člen (1) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Za davčnega zavezanca, ki je v preteklem koledarskem letu dosegel obdavčljiv promet blaga oziroma storitev v vrednosti do vključno 210.000 eurov, je davčno obdobje koledarsko trimesečje, razen če opravlja transakcije znotraj Unije in je dolžan predložiti rekapitulacijsko poročilo iz 90. člena tega zakona.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Obračun DDV (DDV-O) — quarterly deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Obračun DDV (DDV-O) — monthly, taxpayers filing the recapitulative statement

Davek na dodano vrednost (DDV / VAT) · Monthly · return filing

20th of the month after the month ends Verified 2026-10-13
Who files
Taxable persons carrying out intra-EU transactions that must file the recapitulative statement (RP-O); always monthly, because those transactions exclude the quarterly period
Notes
Businesses with intra-EU supplies or services file their VAT return by the 20th of the following month, together with the recapitulative statement, but they do not pay until the last working day of that month. If the 20th is a Saturday, Sunday or holiday the deadline moves to the next working day — the May 2027 return is due Monday 21 June, as 20 June is a Sunday. A return is required for every month, with or without tax to pay.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 88. člen (3) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Davčni zavezanec, ki opravlja transakcije znotraj Unije, in je dolžan predložiti rekapitulacijsko poročilo iz 90. člena tega zakona, mora predložiti obračun DDV do 20. dne naslednjega meseca po poteku davčnega obdobja.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Obračun DDV (DDV-O) — monthly, taxpayers filing the recapitulative statement deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Plačilo DDV — monthly filers

Davek na dodano vrednost (DDV / VAT) · Monthly · payment

last business day of the month after the month ends Verified 2026-10-13
Who files
Every monthly VAT filer, including taxpayers who file their return by the 20th because they submit the recapitulative statement
Notes
VAT for a month is paid by the last working day of the following month, which is also the return deadline for most filers. Intra-EU traders who file on the 20th still have until that last working day to pay. Pay to the state budget account SI56 0110 0888 1000 030 quoting reference SI19, your tax number and 62006. Because the deadline is a working day, a month ending on a weekend brings it forward: VAT for January 2027 is due Friday 26 February.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 77. člen (1)-(2) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Ne glede na prvi odstavek tega člena mora davčni zavezanec v primerih iz tretjega odstavka 88. člena tega zakona plačati DDV najpozneje zadnji delovni dan naslednjega meseca po poteku davčnega obdobja”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Plačilo DDV — monthly filers deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
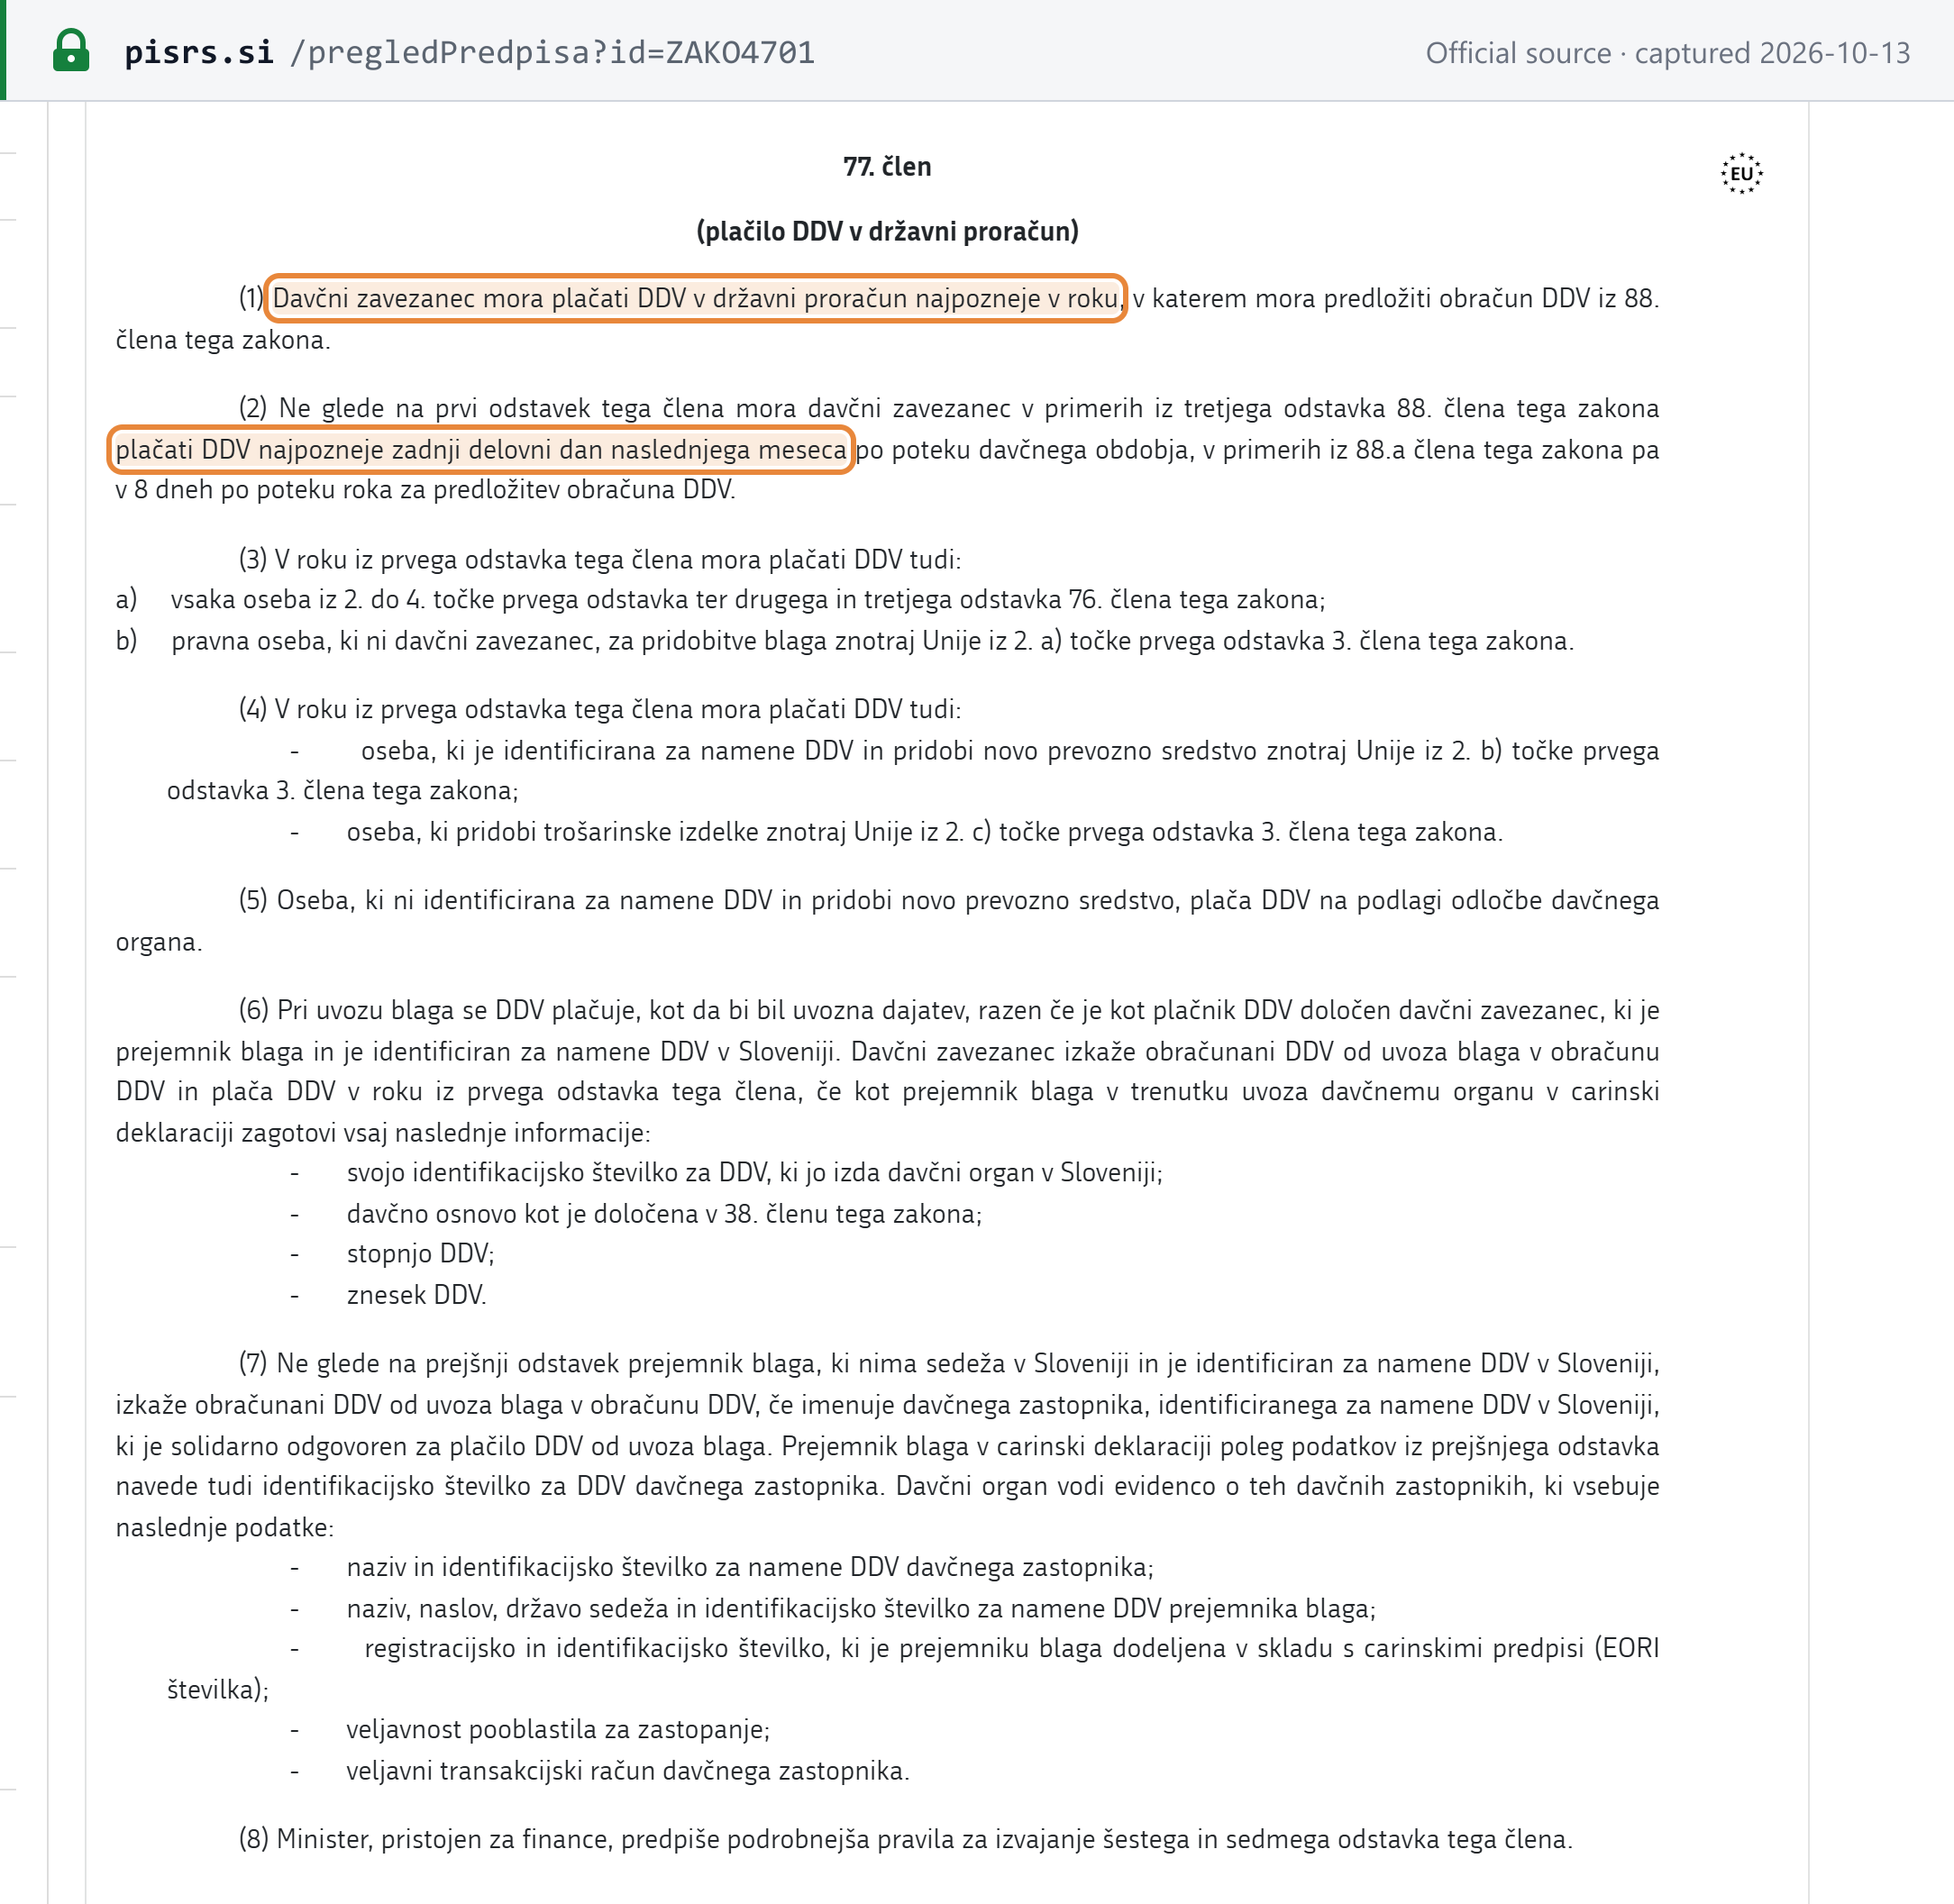
Plačilo DDV — quarterly filers

Davek na dodano vrednost (DDV / VAT) · Quarterly · payment

last business day of the month after the quarter ends Verified 2026-10-13
Who files
Quarterly VAT filers (established, prior-year taxable turnover up to EUR 210,000, no intra-EU transactions requiring a recapitulative statement)
Notes
Quarterly filers pay on the same day they file: the last working day of the month after the quarter. For the October–December quarter that is the end of January, which moves back to Friday 29 January in 2027 because the 31st is a Sunday.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 77. člen (1) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Davčni zavezanec mora plačati DDV v državni proračun najpozneje v roku, v katerem mora predložiti obračun DDV iz 88. člena tega zakona.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Plačilo DDV — quarterly filers deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Evidenca obračunanega DDV in evidenca odbitka DDV (VAT records of output and input VAT)

Davek na dodano vrednost (DDV / VAT) · Monthly · report / listing

last business day of the month after the month ends Verified 2026-10-13
Who files
Every VAT-identified taxable person, for each return period: monthly filers monthly, quarterly filers quarterly; due with the return, so by the 20th for taxpayers who file their return on the 20th
Notes
Since July 2025 every taxpayer submits two structured records — output VAT charged and input VAT deducted — no later than the deadline for the VAT return they support. The dates shown are for monthly filers; quarterly filers submit them with the quarterly return, and taxpayers filing on the 20th by the 20th. Submit them at least three working days before the deadline and FURS prepares a pre-filled return for you. If the return you file disagrees with records already submitted, correct the records within three working days of filing it.
Source
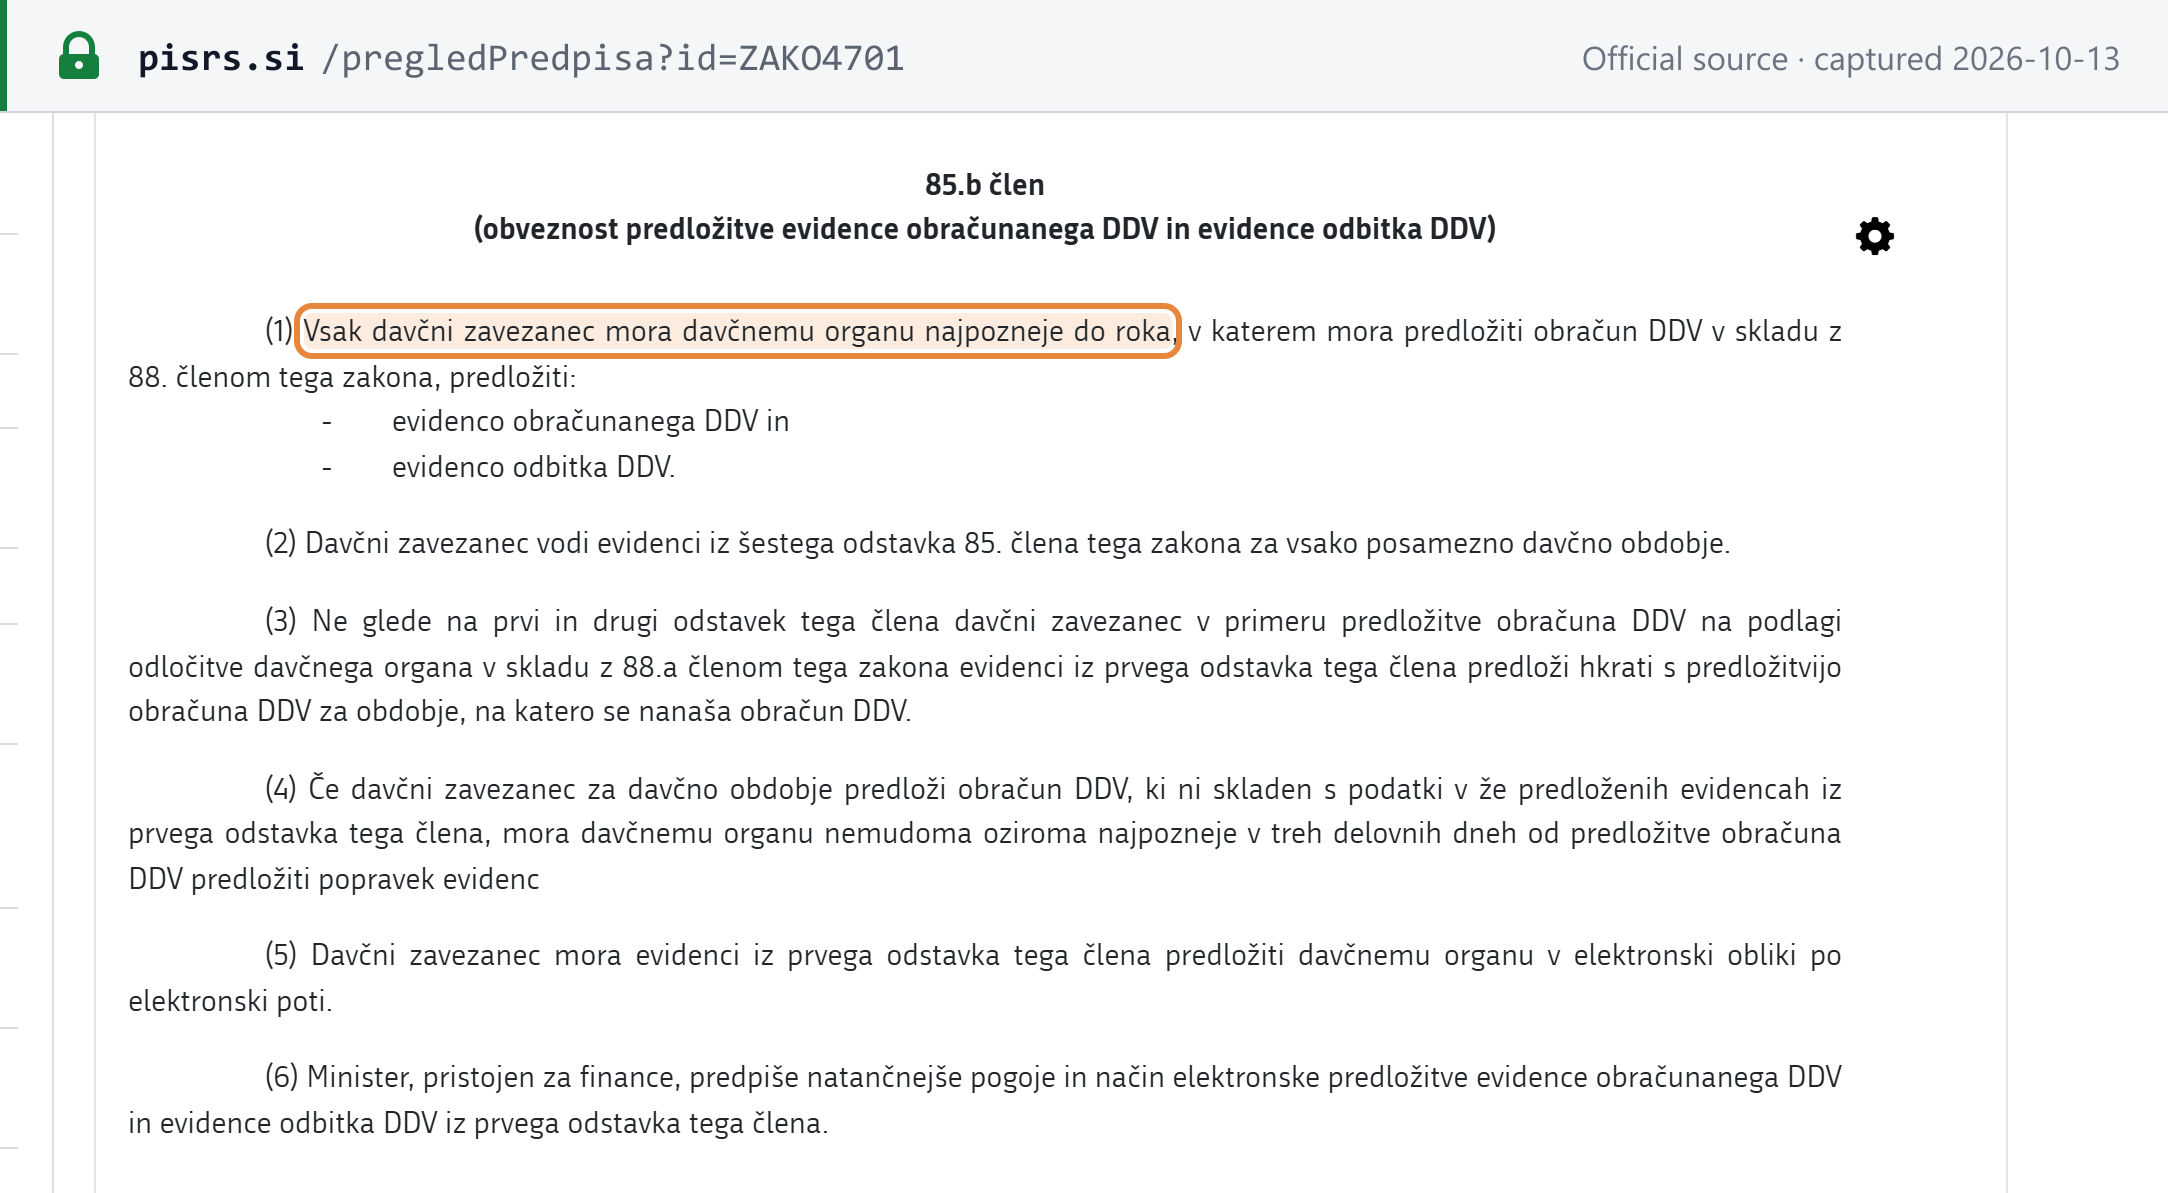
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 85.b člen (1) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Vsak davčni zavezanec mora davčnemu organu najpozneje do roka, v katerem mora predložiti obračun DDV v skladu z 88. členom tega zakona, predložiti:”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Evidenca obračunanega DDV in evidenca odbitka DDV (VAT records of output and input VAT) deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Rekapitulacijsko poročilo (RP-O) — recapitulative statement

Davek na dodano vrednost (DDV / VAT) · Monthly · report / listing

20th of the month after the month ends Verified 2026-10-13
Who files
Taxable persons identified for VAT making intra-EU supplies of goods, call-off-stock transfers or B2B services taxed in the customer's member state; filed only for months with such transactions or corrections
Notes
The EC Sales List is monthly for everyone, including businesses whose VAT return is otherwise quarterly, and is due by the 20th of the following month. You file it only for a month in which you made an intra-EU supply or must correct an earlier one. A 20th that falls on a weekend moves to the next working day: FURS set 22 June 2026 for the May statement.
Source
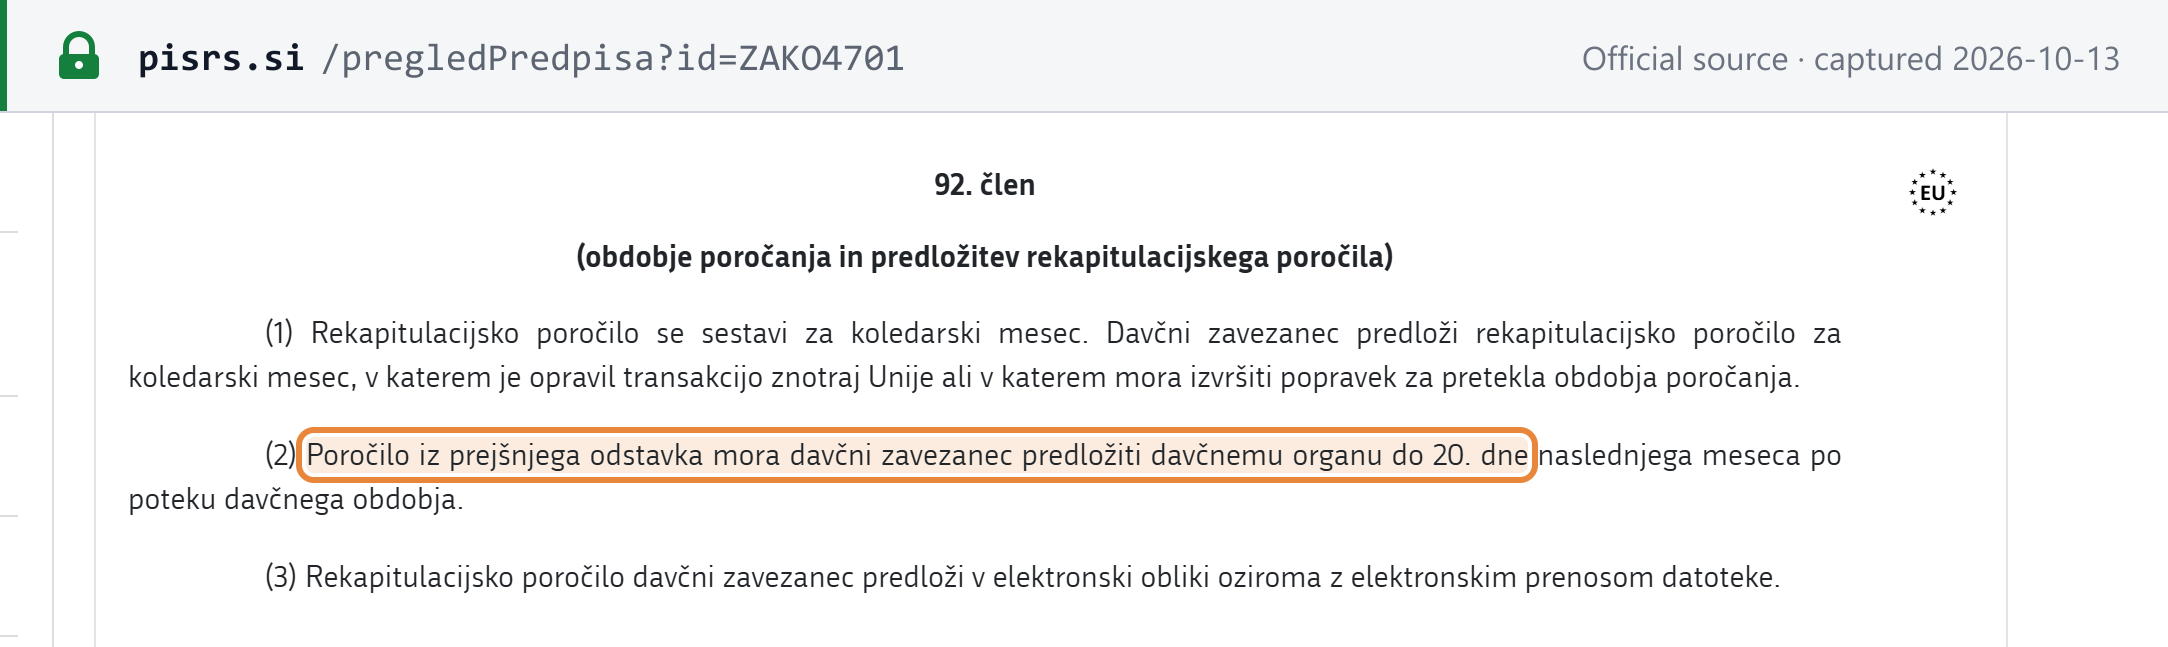
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 92. člen (1)-(2) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Poročilo iz prejšnjega odstavka mora davčni zavezanec predložiti davčnemu organu do 20. dne naslednjega meseca po poteku davčnega obdobja.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Rekapitulacijsko poročilo (RP-O) — recapitulative statement deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Poročilo o dobavah (PD-O) — domestic reverse-charge supplies

Davek na dodano vrednost (DDV / VAT) · Monthly · report / listing

last business day of the month after the month ends Verified 2026-10-13
Who files
Suppliers making domestic supplies on which the Slovenian customer accounts for the VAT under the domestic reverse charge (construction services, scrap and the other Art 76.a supplies); only for months with such supplies or corrections
Notes
A supplier of construction services, scrap or other goods and services on which the Slovenian customer self-assesses the VAT reports those supplies for each calendar month — even if its own VAT return is quarterly. It is due on the same last working day as the monthly return, so the September 2027 report is due Friday 29 October: the 31st is a Sunday and a holiday, and the 30th a Saturday.
Source
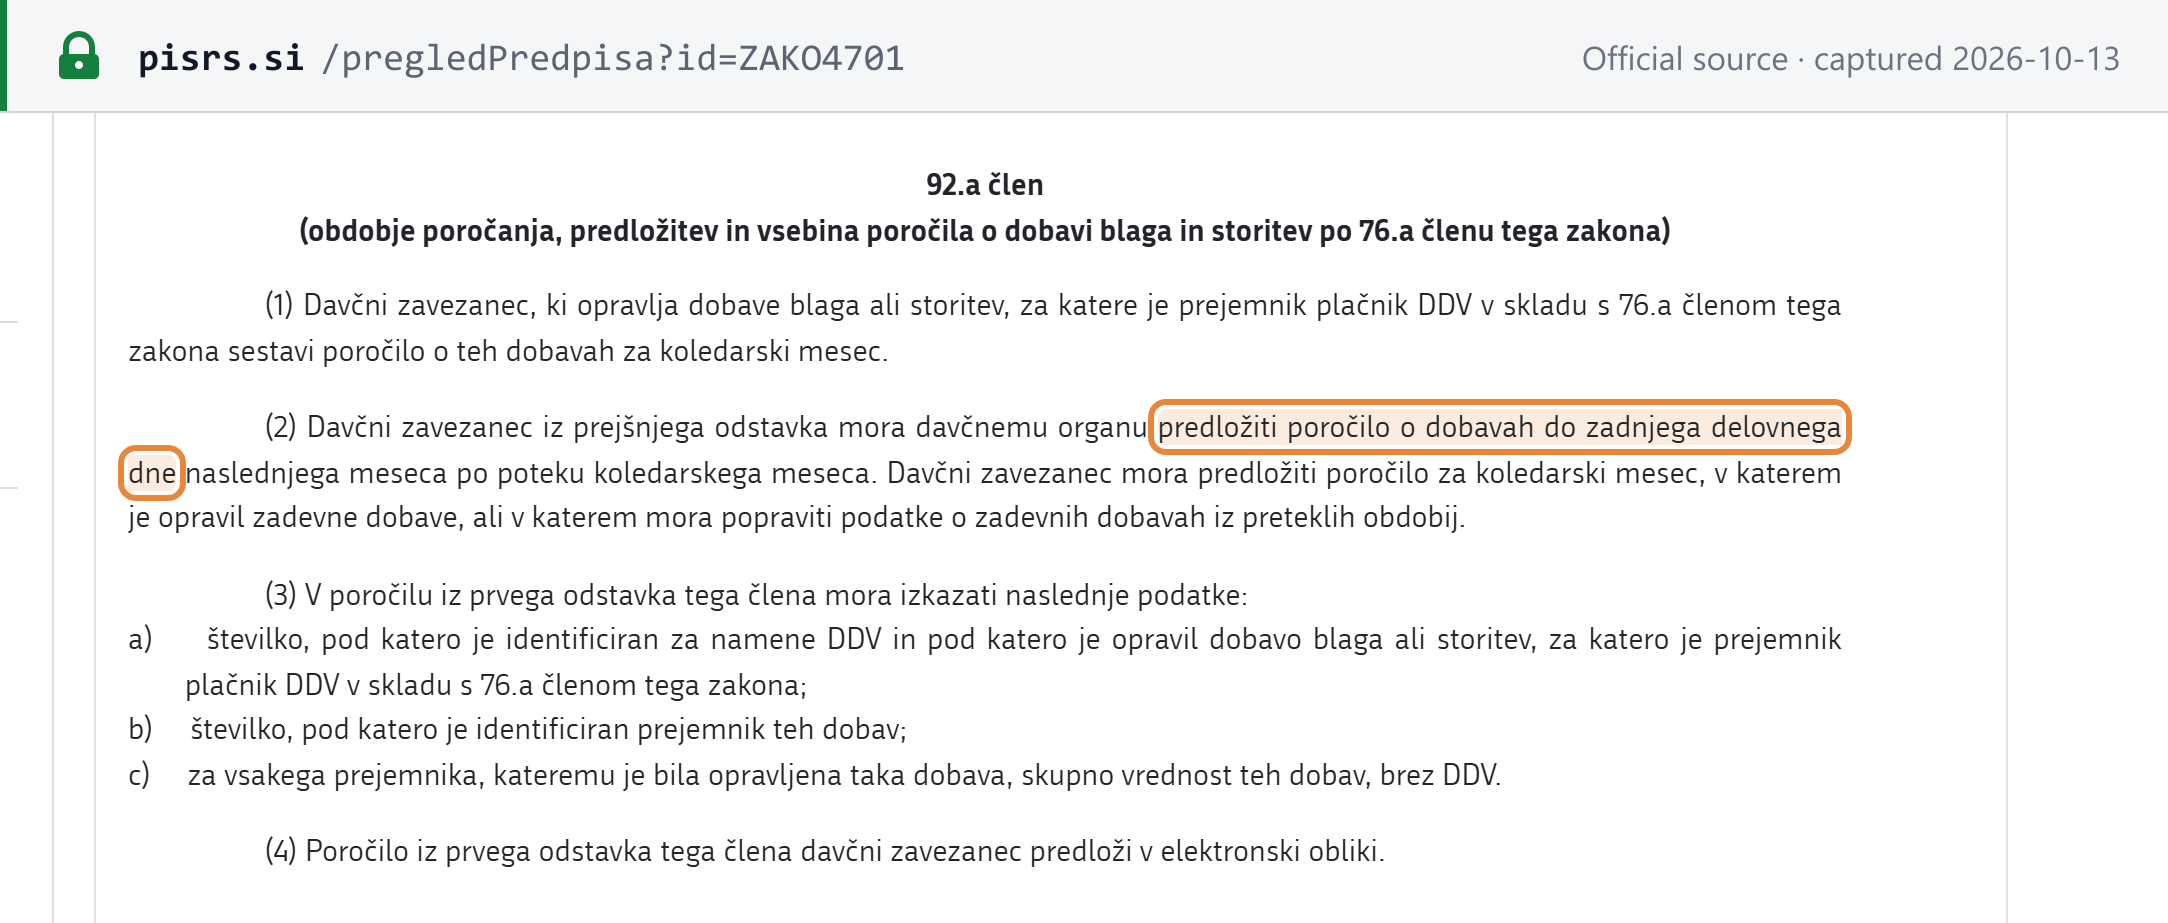
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 92.a člen (1)-(2) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Davčni zavezanec iz prejšnjega odstavka mora davčnemu organu predložiti poročilo o dobavah do zadnjega delovnega dne naslednjega meseca po poteku koledarskega meseca.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Poročilo o dobavah (PD-O) — domestic reverse-charge supplies deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Posebni obračun DDV — Union One Stop Shop (OSS)

DDV (VAT) — posebna ureditev, unijska ureditev (Union OSS) · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-13
Who files
Taxable persons registered in Slovenia for the Union scheme: intra-EU distance sales of goods and B2C services supplied in member states where the supplier is not established
Notes
A quarterly OSS return is due by the end of the month after each calendar quarter — 30 April, 31 July, 31 October and 31 January — and a nil return is required for a quarter with no sales. Payment is due no later than the same day. These dates are shown as stated and not moved off weekends, as the deadline is set by EU law; filing earlier when the last day is a weekend or holiday avoids the question.
Source
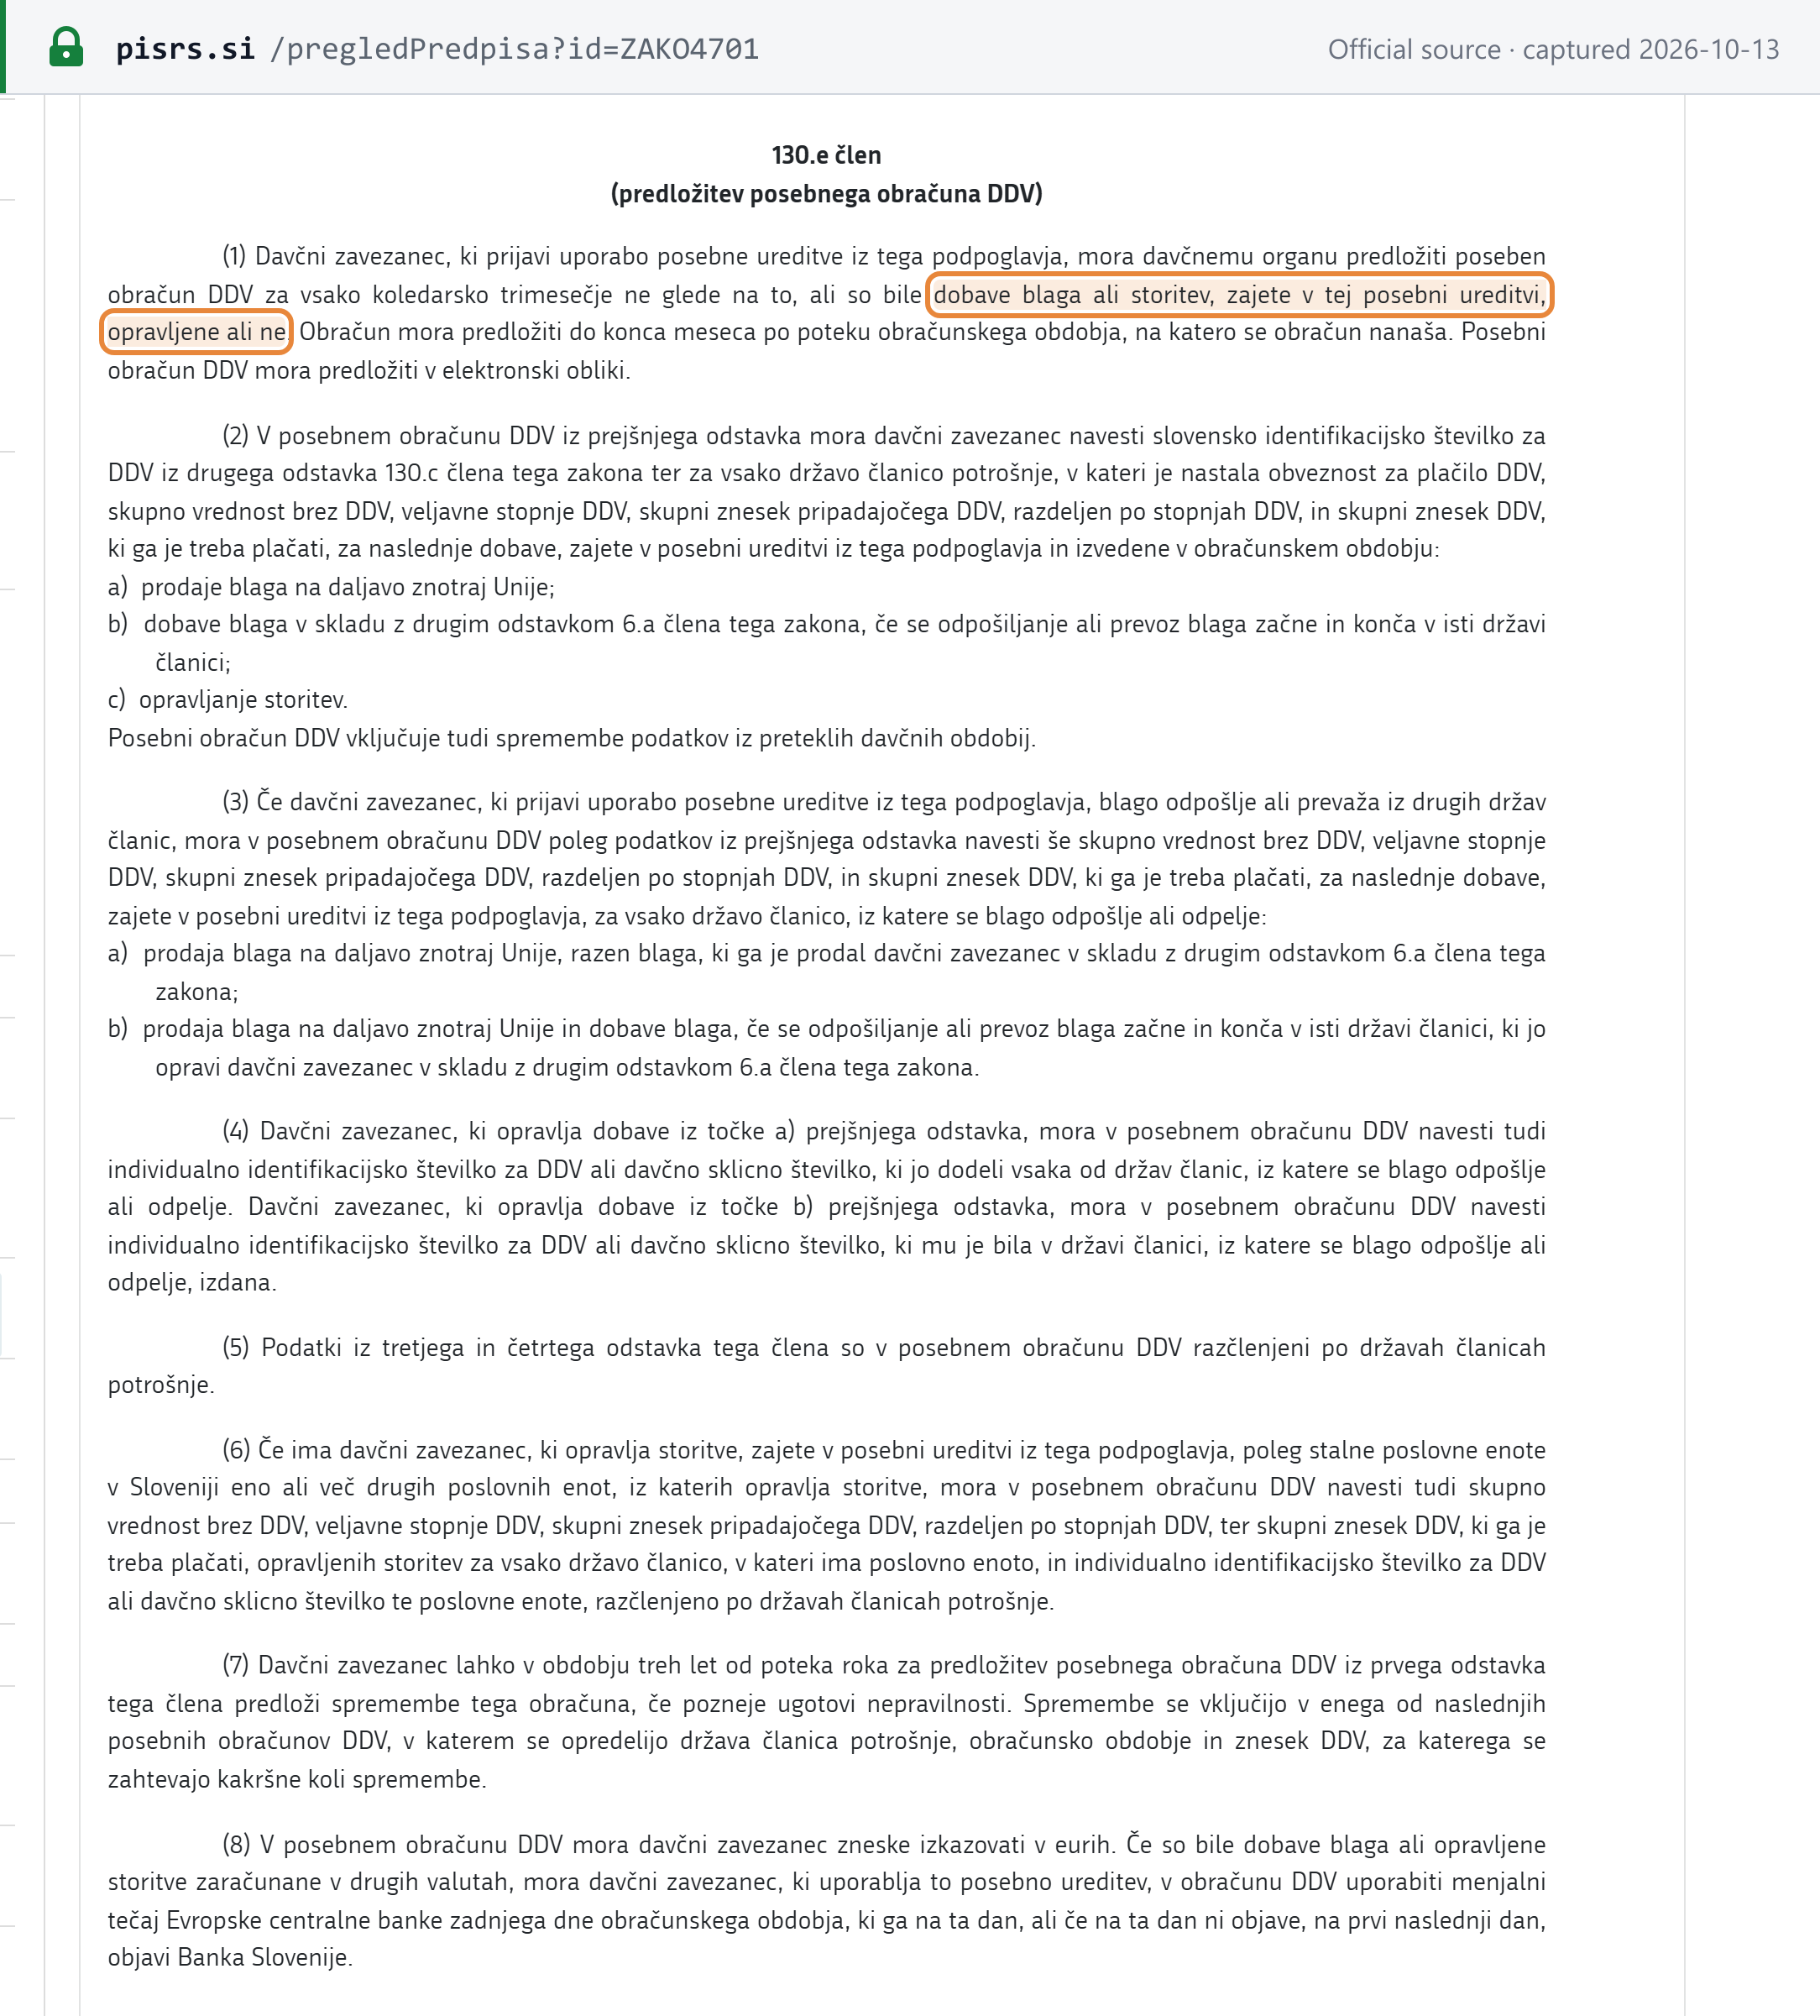
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 130.e člen (1), 130.f člen PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Davčni zavezanec, ki prijavi uporabo posebne ureditve iz tega podpoglavja, mora davčnemu organu predložiti poseben obračun DDV za vsako koledarsko trimesečje ne glede na to, ali so bile dobave blaga ali storitev, zajete v tej posebni ureditvi, opravljene ali ne. Obračun mora predložiti do konca meseca po poteku obračunskega obdobja, na katero se obračun nanaša.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Posebni obračun DDV — Union One Stop Shop (OSS) deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Posebni obračun DDV — non-Union One Stop Shop

DDV (VAT) — posebna ureditev za davčne zavezance, ki nimajo sedeža v Uniji (non-Union OSS) · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-13
Who files
Businesses established outside the EU, identified in Slovenia under the non-Union scheme, supplying services to consumers in EU member states
Notes
Non-EU suppliers of services to EU consumers using Slovenia as their OSS member state file one return per calendar quarter, by the last day of the following month, whether or not they made any supplies. The VAT must reach FURS by that same day at the latest.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 127. člen (1), 128. člen PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Davčni zavezanec, ki nima sedeža znotraj Unije, mora davčnemu organu predložiti posebni obračun DDV za vsako koledarsko trimesečje ne glede na to, ali so bile storitve, zajete v tej posebni ureditvi, opravljene ali ne. Posebni obračun DDV mora predložiti do konca meseca po poteku obračunskega obdobja, na katero se obračun nanaša.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Posebni obračun DDV — non-Union One Stop Shop deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Posebni obračun DDV — Import One Stop Shop (IOSS)

DDV (VAT) — posebna ureditev za prodajo na daljavo blaga, uvoženega iz tretjih držav (IOSS) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-13
Who files
Suppliers, or their intermediaries, registered in Slovenia for the import scheme for distance sales of imported goods in consignments of up to EUR 150
Notes
IOSS returns are monthly, nil returns included, and due by the end of the following month; the VAT is paid with the return or by that day at latest.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 130.n člen (1), 130.o člen PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“mora davčnemu organu predložiti poseben obračun DDV za vsak koledarski mesec ne glede na to, ali je bila prodaja na daljavo s tretjih ozemelj ali iz tretjih držav uvoženega blaga opravljena ali ne. Obračun mora predložiti do konca meseca po poteku obračunskega obdobja, na katerega se obračun nanaša.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Posebni obračun DDV — Import One Stop Shop (IOSS) deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Četrtletno poročilo — EU cross-border SME scheme quarterly report

DDV (VAT) — posebna ureditev za mala podjetja v drugih državah članicah (EU SME scheme) · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-13
Who files
Businesses established in Slovenia that use the VAT exemption for small enterprises in other EU member states (EX identification number)
Notes
A Slovenian small business exempt from VAT in other member states under the EU SME scheme reports its turnover in Slovenia and in each of those states every quarter, by the last day of the month after the quarter, including quarters with nothing to report. The law states a plain calendar day, so file early when it falls on a weekend.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 94.e člen (6) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Davčni zavezanec mora četrtletno poročilo iz tega člena predložiti davčnemu organu najpozneje zadnji dan meseca, ki sledi koledarskemu četrtletju, na katero se podatki nanašajo.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Četrtletno poročilo — EU cross-border SME scheme quarterly report deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Poročilo o preseganju letnega prometa v Uniji — SME scheme exceed report

DDV (VAT) — posebna ureditev za mala podjetja v drugih državah članicah (EU SME scheme) · One-off · registration

within 15 business days of the day annual Union turnover exceeded EUR 100,000 Verified 2026-10-13
Who files
Slovenian users of the EU cross-border SME scheme whose total turnover in the Union exceeds EUR 100,000
Notes
Once your turnover across the EU passes EUR 100,000 in a year, you must tell FURS within 15 working days, and the cross-border exemption stops applying from the day you crossed the threshold — so supplies from that day on are taxed in the member states where they are made.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 94.f člen (1) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Če davčni zavezanec preseže prag letnega prometa v Uniji iz točke a) prvega odstavka 94.b člena tega zakona, mora predložiti poročilo o preseganju letnega prometa v Uniji v 15 delovnih dneh od dneva, ko je bil presežen prag.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Poročilo o preseganju letnega prometa v Uniji — SME scheme exceed report deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
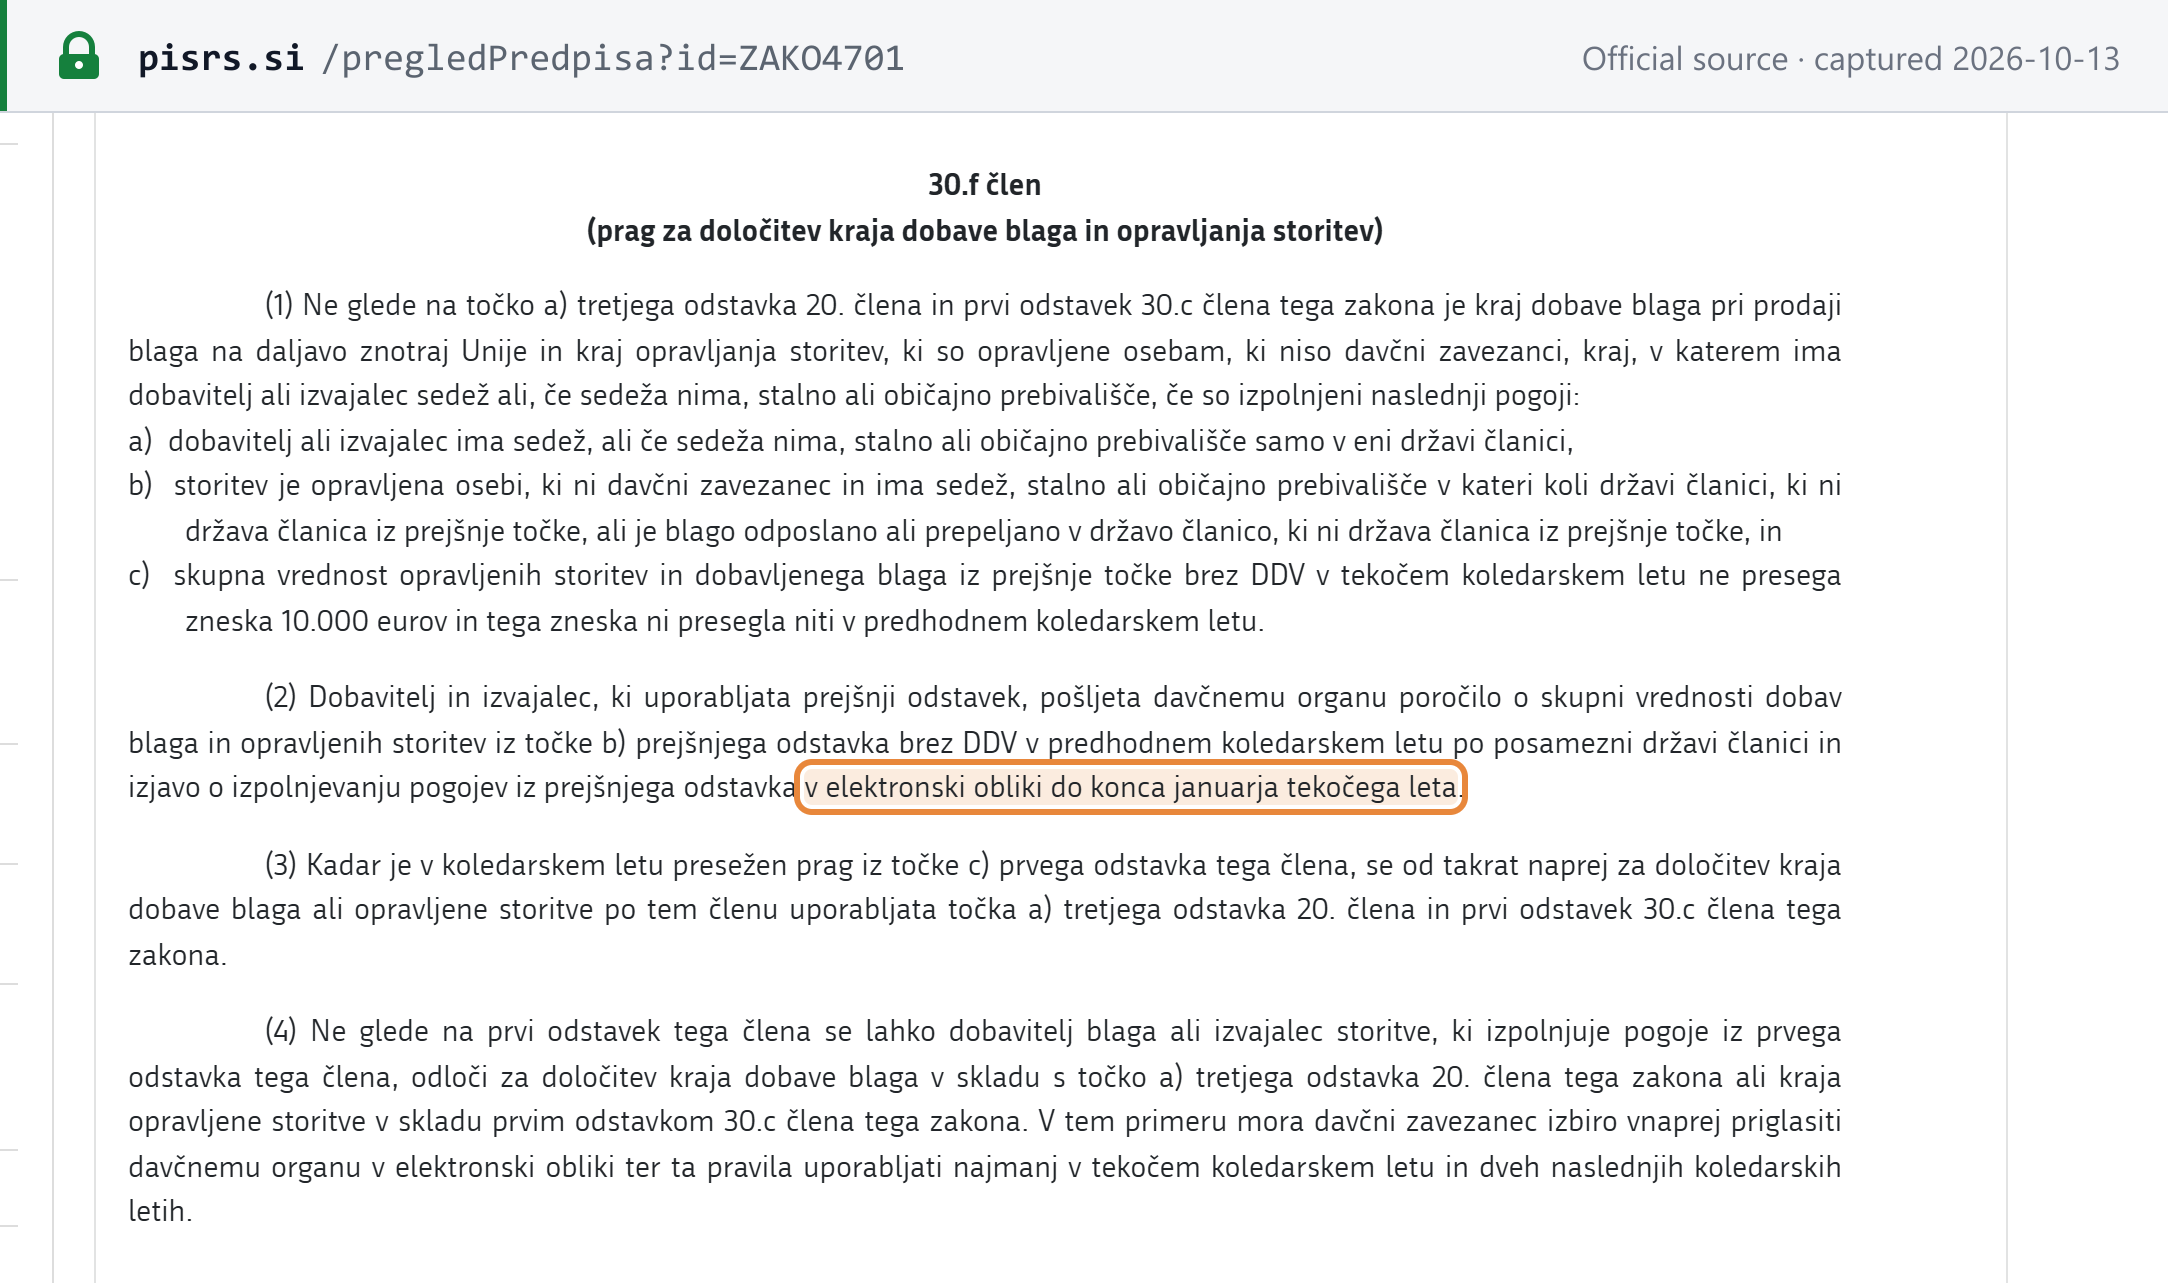
Obrazec DDV-TBE — annual report under the EUR 10,000 distance-sales threshold

Davek na dodano vrednost (DDV / VAT) · Annually · report / listing

31st January each year Verified 2026-10-13
Who files
Slovenian suppliers of intra-EU distance sales of goods and telecommunications, broadcasting and electronic services to consumers who stay under the EUR 10,000 EU-wide threshold and charge Slovenian VAT, whether or not VAT-registered in Slovenia
Notes
If you keep Slovenian VAT on cross-border sales to EU consumers because they stay below EUR 10,000 a year, you send FURS a report of last year's totals per member state, with a declaration that the conditions were met, by the end of January. FURS moved the 2026 deadline from Saturday 31 January to Monday 2 February; 31 January 2027 is a Sunday, so expect Monday 1 February.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 30.f člen (2) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Dobavitelj in izvajalec, ki uporabljata prejšnji odstavek, pošljeta davčnemu organu poročilo o skupni vrednosti dobav blaga in opravljenih storitev iz točke b) prejšnjega odstavka brez DDV v predhodnem koledarskem letu po posamezni državi članici in izjavo o izpolnjevanju pogojev iz prejšnjega odstavka v elektronski obliki do konca januarja tekočega leta.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Obrazec DDV-TBE — annual report under the EUR 10,000 distance-sales threshold deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Poročilo o prodaji blaga na daljavo v druge države članice — annual distance-sales report

Davek na dodano vrednost (DDV / VAT) · Annually · report / listing

31st January each year Verified 2026-10-13
Who files
Taxpayers whose intra-EU distance sales of goods are taxed in the member state of destination and who do not use the Union One Stop Shop
Notes
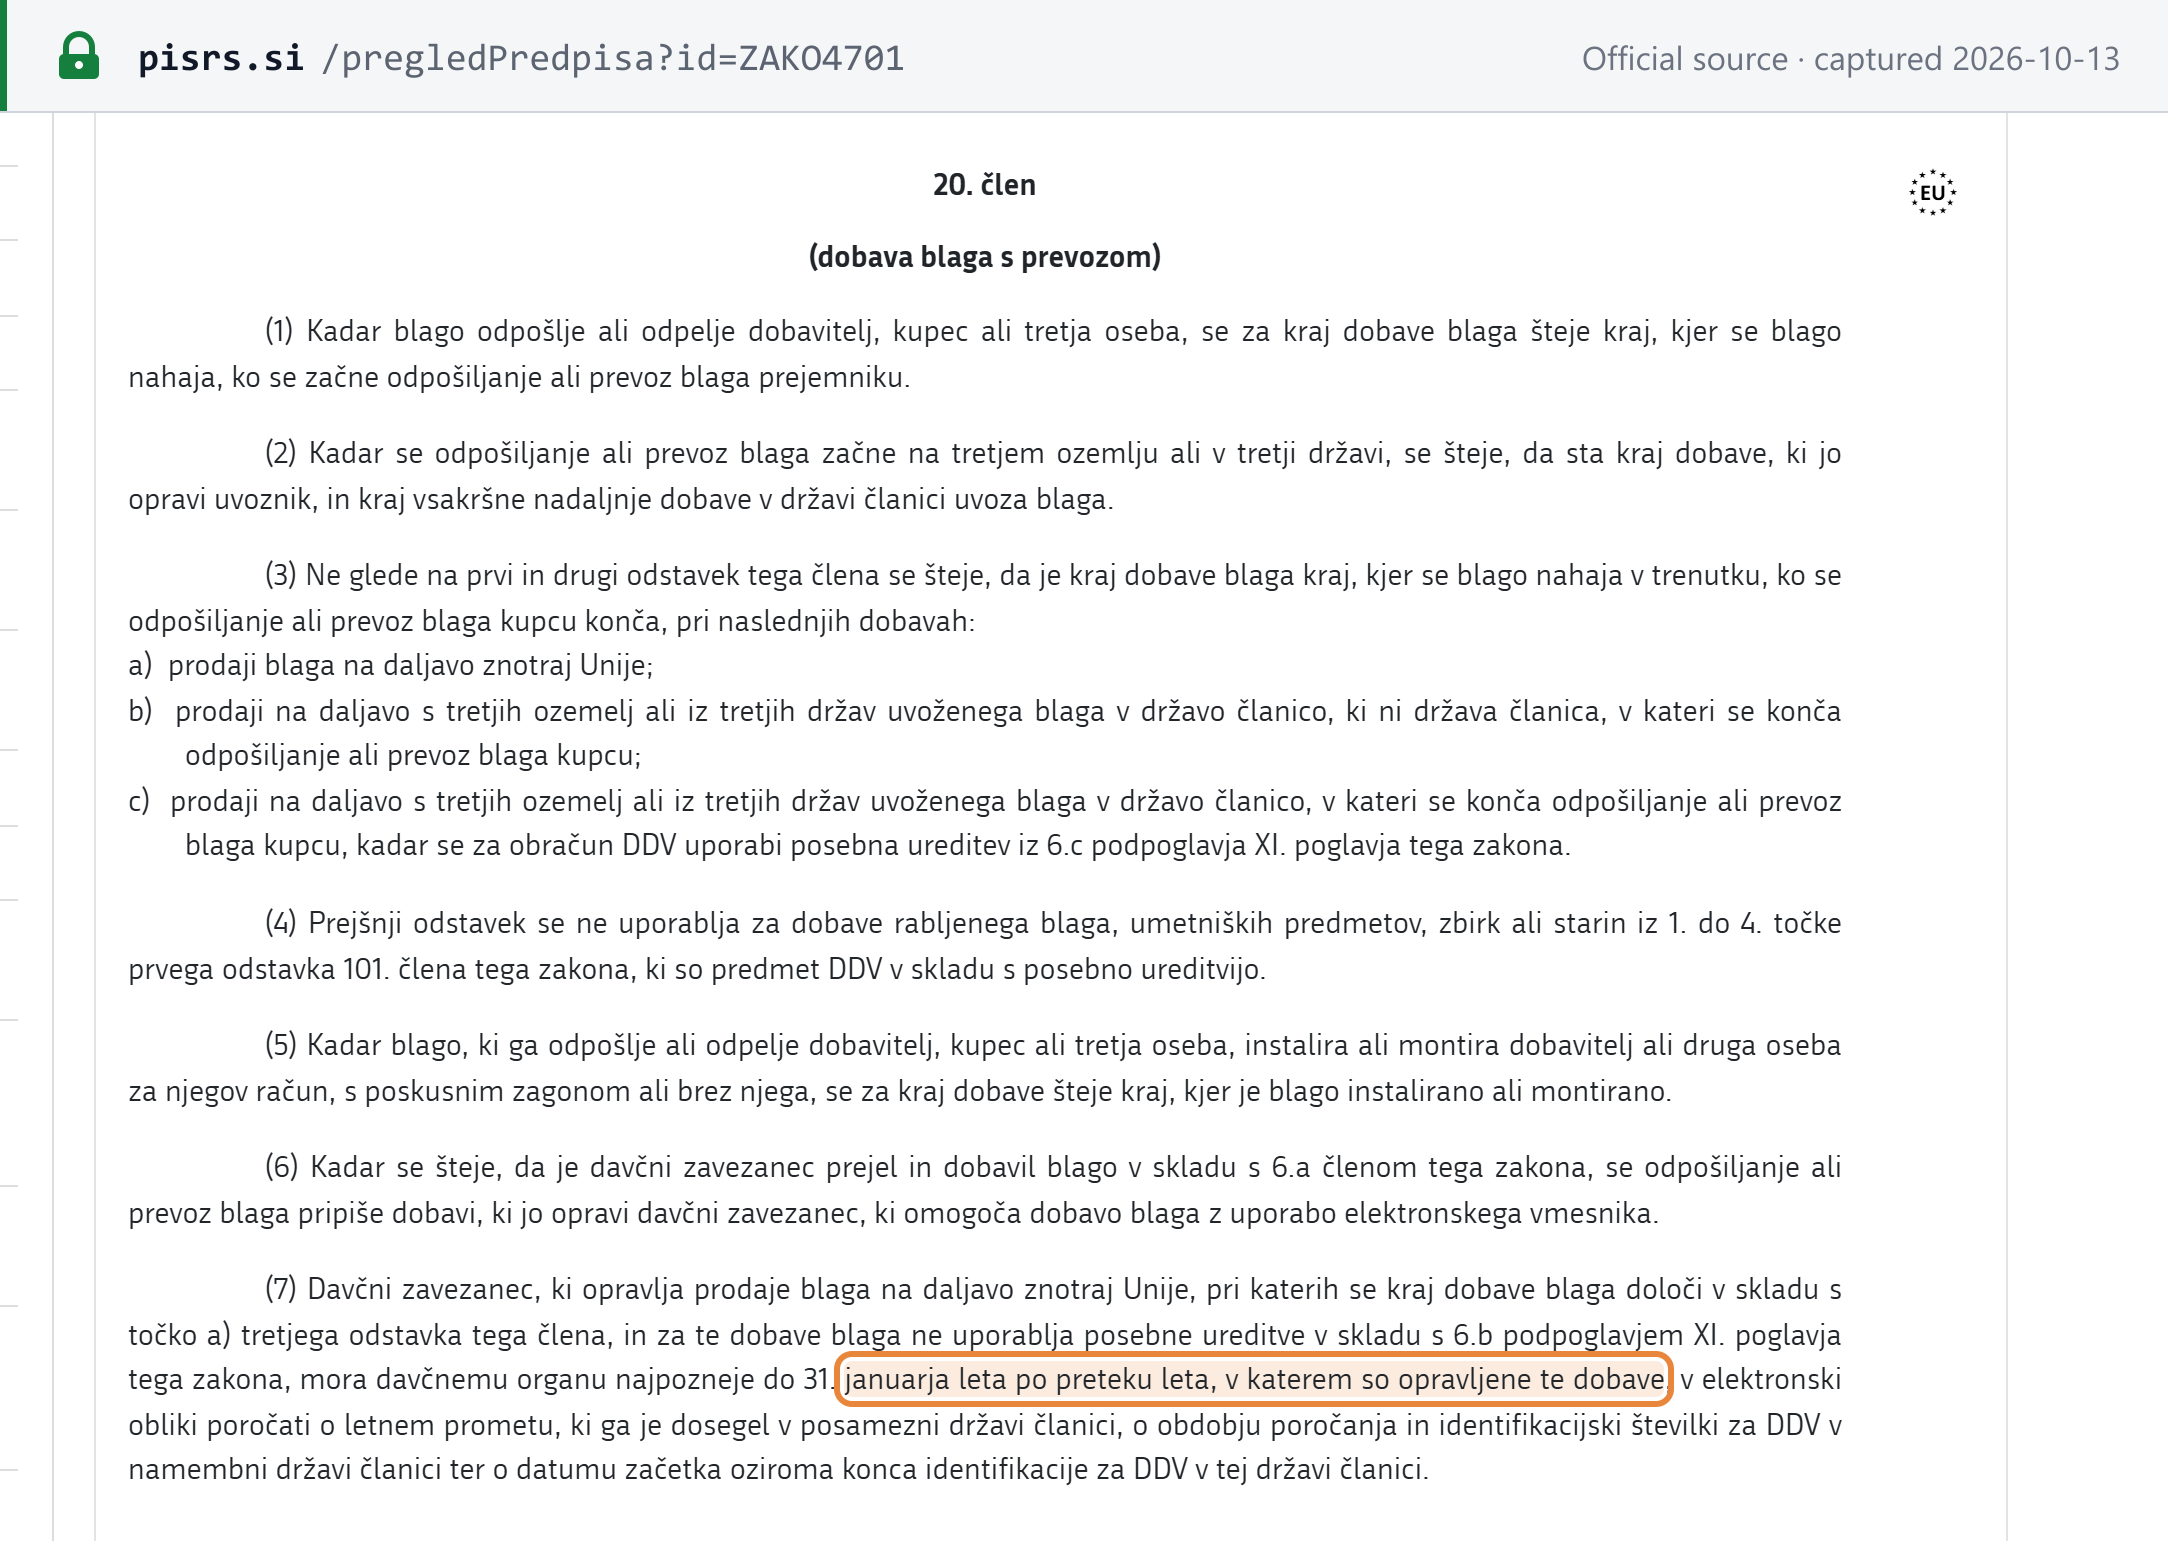
A business that pays VAT on its distance sales directly in other member states, rather than through the One Stop Shop, reports to FURS by 31 January the turnover it made in each of those states in the previous year. FURS's own calendar lists this report on 31 January even when that is a weekend — it did so for Saturday 31 January 2026 — so this calendar shows 31 January every year. Filing by then is always on time.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 20. člen (7) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“januarja leta po preteku leta, v katerem so opravljene te dobave, v elektronski obliki poročati o letnem prometu, ki ga je dosegel v posamezni državi članici”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Poročilo o prodaji blaga na daljavo v druge države članice — annual distance-sales report deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Seznam neplačanih računov (DDV-SEZPR) — cash-accounting scheme

DDV (VAT) — posebna ureditev po plačani realizaciji (cash accounting) · Annually · report / listing

31st January each year Verified 2026-10-13
Who files
Taxpayers using the cash-accounting scheme (posebna ureditev obdavčitve po plačani realizaciji)
Notes
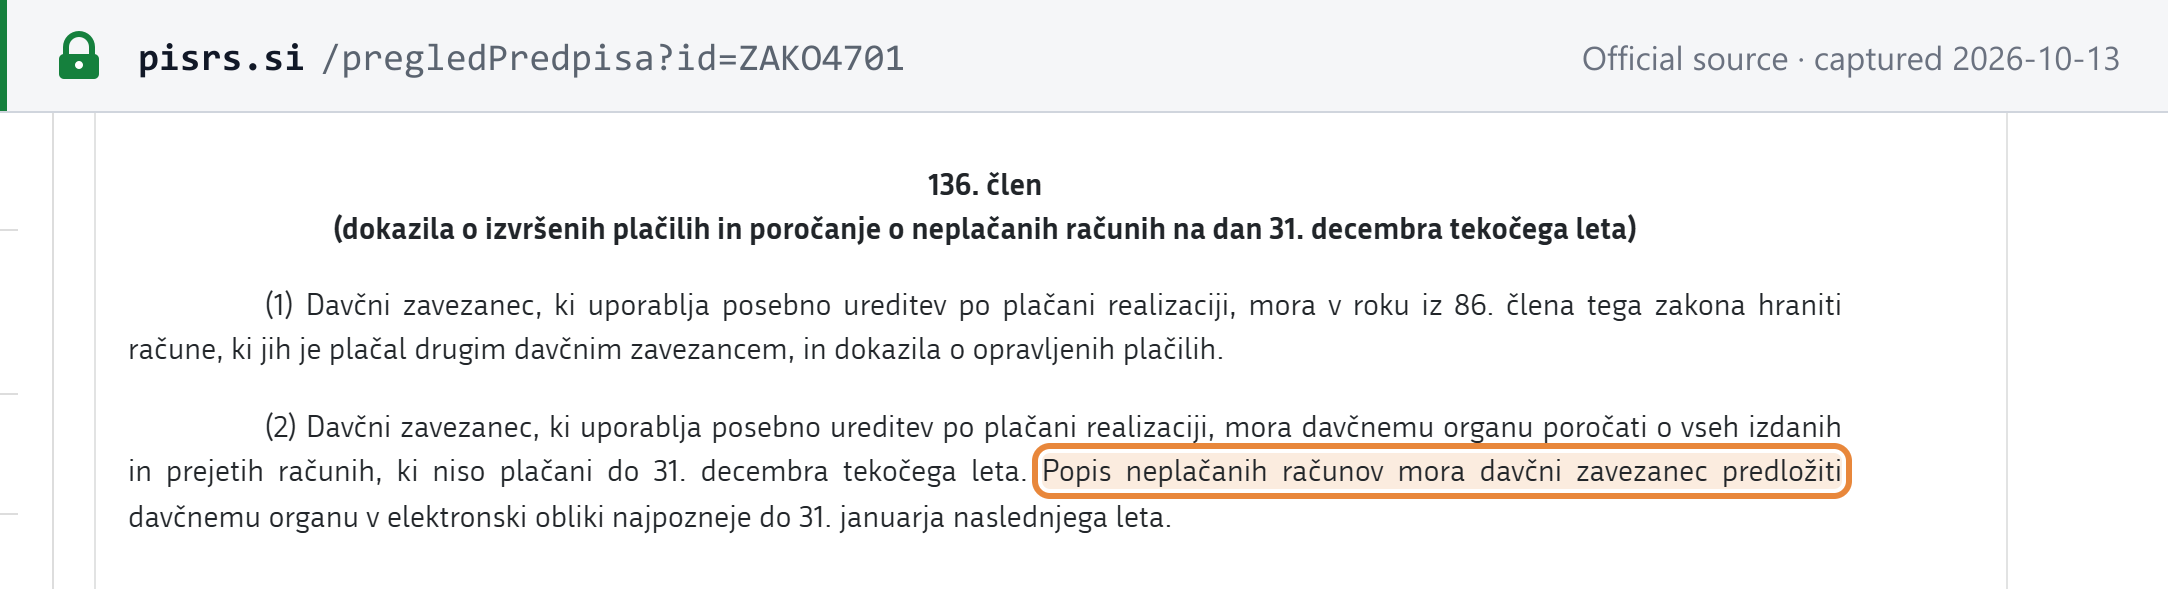
Businesses on cash accounting list the invoices they issued and received that were still unpaid on 31 December and file the list electronically by 31 January. FURS set 2 February for the 2025 list, as 31 January 2026 was a Saturday.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 136. člen (2) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Popis neplačanih računov mora davčni zavezanec predložiti davčnemu organu v elektronski obliki najpozneje do 31. januarja naslednjega leta.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Seznam neplačanih računov (DDV-SEZPR) — cash-accounting scheme deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Obračun pavšalnega nadomestila — flat-rate compensation return (farmers and foresters)

DDV (VAT) — pavšalno nadomestilo (flat-rate scheme for farmers) · Annually · return filing

31st January each year Verified 2026-10-13
Who files
Farmers and foresters holding a FURS permit to charge the flat-rate VAT compensation
Notes
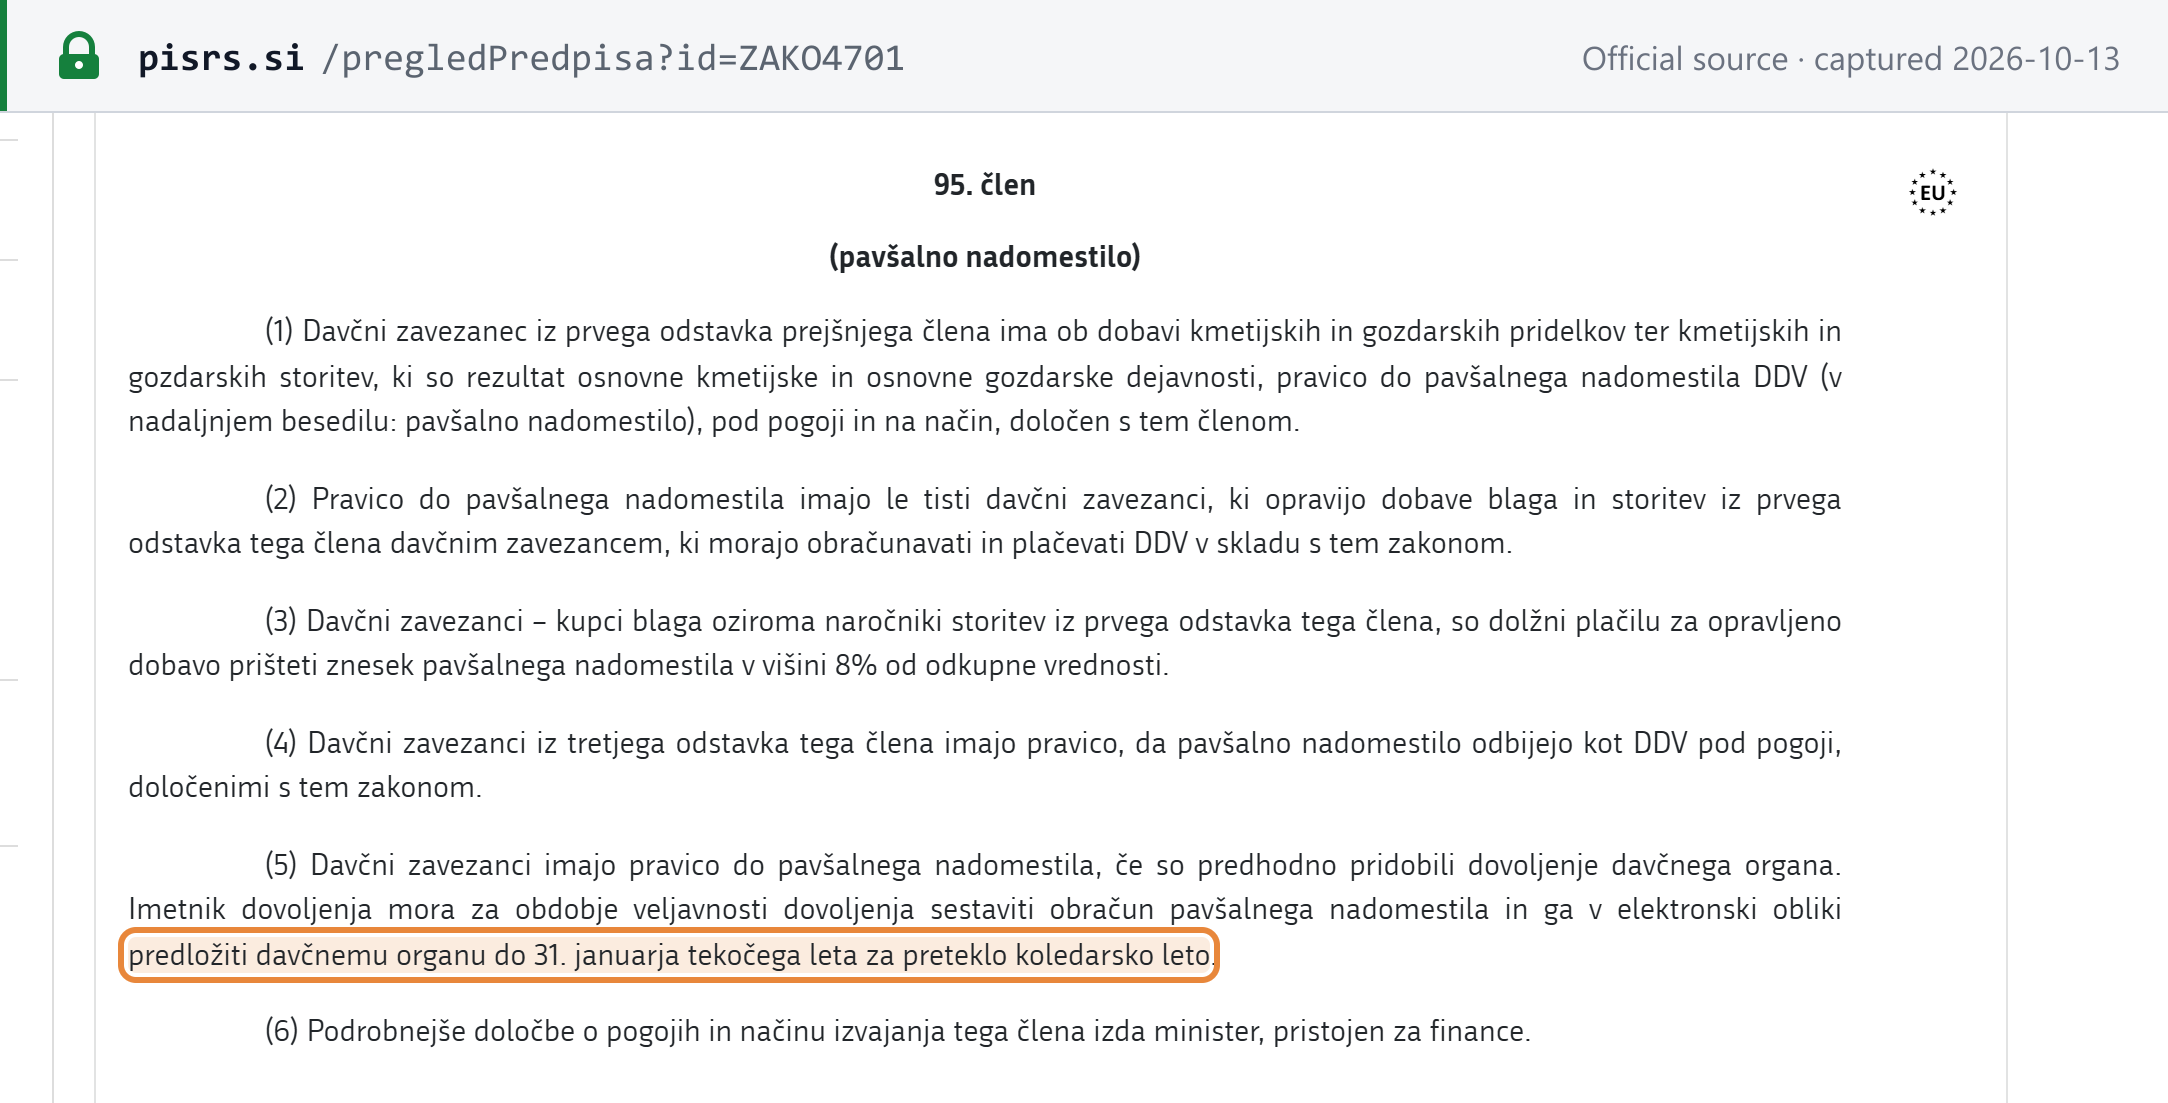
Farmers and foresters who hold a permit to add the 8% flat-rate compensation to their sales file an annual return of the compensation received for the previous calendar year, electronically, by 31 January; FURS lists 31 January as the date even when it falls on a weekend, as it did in 2026. The compensation itself is 8% of the purchase value, added by the VAT-registered buyer.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 95. člen (5) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Imetnik dovoljenja mora za obdobje veljavnosti dovoljenja sestaviti obračun pavšalnega nadomestila in ga v elektronski obliki predložiti davčnemu organu do 31. januarja tekočega leta za preteklo koledarsko leto.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Obračun pavšalnega nadomestila — flat-rate compensation return (farmers and foresters) deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13
Posebni obračun DDV — occasional international bus transport (annual)

DDV (VAT) — posebna ureditev za mednarodni občasni cestni prevoz potnikov · Annually · return filing

31st January each year Verified 2026-10-13
Who files
Carriers not established in Slovenia using the special arrangement for occasional international passenger transport by bus in Slovenia
Notes
Foreign coach operators using the special arrangement for occasional international passenger transport have a calendar-year tax period. Their special VAT return for the year is due electronically by the last working day of January, and the VAT is paid by the same day: Friday 29 January in 2027, because the 31st is a Sunday.
Source
Zakon o davku na dodano vrednost (ZDDV-1), neuradno prečiščeno besedilo NPB 20 — 137.e člen (1), (3); 137.f člen PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Davčni zavezanec iz prvega odstavka 137.a člena tega zakona mora davčnemu organu predložiti posebni obračun DDV do zadnjega delovnega dne naslednjega meseca po poteku davčnega obdobja.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Posebni obračun DDV — occasional international bus transport (annual) deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13

Zahtevek za identifikacijo za DDV (DDV-P2) — on exceeding EUR 66,000

Davek na dodano vrednost (DDV / VAT) · One-off · registration

no later than the day of the end of the month in which turnover is expected to exceed EUR 66,000 Verified 2026-10-13
Who files
Businesses established in Slovenia whose turnover in Slovenia exceeds EUR 66,000 during the current calendar year
Notes
Cross EUR 66,000 of turnover in Slovenia during the year and you need a VAT number already for that month, so the application on form DDV-P2 is due in that same month at the latest — apply in the month you expect to cross it. VAT is due from the supply that takes you over the limit. If you pass EUR 60,000 but stay under EUR 66,000, you remain exempt until the year ends but must apply in good time to hold a VAT number from 1 January; FURS has until the end of the month after your application to issue it.
Source
FURS — Identifikacija za namene DDV Finančna uprava Republike Slovenije (FURS)
See the source text
“Če davčni zavezanec v tekočem koledarskem letu preseže znesek 66.000 eurov letnega prometa na ozemlju Slovenije, pa mora zahtevek za izdajo identifikacijske številke za DDV predložiti najpozneje v mesecu, v katerem bo presegel navedeni znesek, saj mora pridobiti identifikacijsko številko za DDV že za mesec, v katerem bo presegel ta znesek.”
Screenshot of Finančna uprava Republike Slovenije (FURS) showing the Zahtevek za identifikacijo za DDV (DDV-P2) — on exceeding EUR 66,000 deadline Open full size Captured from Finančna uprava Republike Slovenije (FURS) on 2026-09-29

Zahtevek za identifikacijo za DDV (DDV-P3) — business not established in Slovenia

Davek na dodano vrednost (DDV / VAT) · One-off · registration

at least 15 days before the first taxable supply in Slovenia Verified 2026-10-13
Who files
Taxable persons not established in Slovenia that will make taxable supplies of goods or services in Slovenia on which they, not the customer, account for the VAT; no turnover threshold applies unless an EU-established business uses the cross-border SME scheme (exempt up to EUR 60,000)
Notes
A foreign business has no registration threshold in Slovenia unless it uses the EU cross-border SME scheme, under which a business established in another member state stays exempt in Slovenia up to EUR 60,000 a year. Otherwise, if it will make a supply there on which it must charge Slovenian VAT itself, it applies on form DDV-P3 at least 15 days before that first supply. Businesses from outside the EU generally also need a Slovenian tax representative.
Source
Pravilnik o izvajanju Zakona o davku na dodano vrednost — 131. člen (2) PISRS — Služba Vlade Republike Slovenije za zakonodajo
See the source text
“Če davčni zavezanec iz tega člena opravi obdavčljivo dobavo blaga oziroma storitev v Sloveniji, predloži zahtevek za izdajo identifikacijske številke najpozneje 15 dni, preden bo opravil obdavčljivo dobavo.”
Screenshot of PISRS — Služba Vlade Republike Slovenije za zakonodajo showing the Zahtevek za identifikacijo za DDV (DDV-P3) — business not established in Slovenia deadline Open full size Captured from PISRS — Služba Vlade Republike Slovenije za zakonodajo on 2026-10-13

Slovenian VAT deadlines move in two different directions. The VAT return, the payment, the VAT records and the domestic reverse-charge report are due on the last WORKING day of the month, so a month ending on a weekend or holiday brings them forward — 31 October is a public holiday every year, which makes the September and third-quarter returns due on the 30th or earlier. Deadlines on the 20th, and the DDV-TBE and unpaid-invoice reports due on 31 January, move the other way, to the next working day. One Stop Shop and SME-scheme dates, the distance-sales report and the farmers' flat-rate return are shown as stated. A holiday falling on a Sunday creates no substitute day. After VAT registration ends, a final return is due by the last working day of the month after the month it ended. Not shown: the monthly report under the special arrangement for import VAT and OSS registration timing. B2B e-invoicing becomes mandatory from 1 January 2028 without any reporting to FURS. Excise and other indirect taxes, income tax and payroll are out of scope.

“Če je zadnji dan zakonsko predpisanega roka nedelja, državni praznik ali kak drug dan, ko se pri organu ne dela, se izteče rok za izpolnitev obveznosti s pretekom prvega naslednjega delovnika, če ni s tem zakonom ali z zakonom o obdavčenju določeno drugače.”
Screenshot of the official source stating the rule that governs Slovenia's deadlines
Zakon o davčnem postopku (ZDavP-2) — 45. člen (materialni roki), odstavek (2) — PISRS — Služba Vlade Republike Slovenije za zakonodajo, captured 2026-10-13

What this calendar does not list

  • Not applicable Annual or reconciliation return — Slovenia has no annual VAT return. ZDDV-1 Art 88 requires monthly or quarterly returns only, and year-end figures are corrected in the periodic returns. A search of the full ZDDV-1 text (PISRS NPB 20, amendments through Uradni list RS 104/24) for "letni obračun", "letnega obračuna" and "obračun za koledarsko leto" found nothing, and FURS's 2026 VAT deadline calendar lists no annual return (checked 2026-10-13). The annual flat-rate compensation return and the annual bus-transport special return are scheme returns, not reconciliations.
  • Not applicable E-invoicing / e-reporting cycle — Slovenia's B2B e-invoicing act (ZIERDED, Uradni list RS 85/2025) applies from 1 January 2028 and requires e-invoices to be exchanged between businesses (Art 7) through e-route providers, PEPPOL or direct exchange; it sets no reporting of invoice data to FURS and no submission deadline separate from issuing the invoice (Arts 7, 9, 28; checked 2026-09-30, re-confirmed against the repo facts 2026-10-13). Implementing regulations due under Art 27 could in principle add a cadence and should be re-checked before 2028.

About this calendar

Which Slovenia tax deadlines does this calendar cover?

20 recurring indirect-tax obligations — Davek na dodano vrednost (DDV / VAT) and DDV (VAT) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-13). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.