South Korea compliance calendar

16 recurring 부가가치세 (VAT), 개별소비세 (Individual Consumption Tax) and 주세 (Liquor Tax) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new South Korea rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
26
27
28
29
30
31
1
2
3
4
5
6
Other Report / listing Return filing Payment

Dates already include the weekend and public-holiday shift where South Korea applies one — 13 of 16 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

부가가치세 예정신고 — preliminary VAT return (corporations)

부가가치세 (VAT) · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-14
Who files
Corporations whose supply value in the previous six-month taxable period was KRW 150 million or more; also individuals and smaller corporations that choose to file instead of paying the notice (sales fallen below one-third of the previous period, or claiming an early refund)
Notes
Covers January–March and July–September: the return is due by 25 April and 25 October, and the tax is paid by the same day. The July–September 2026 return is due Monday 26 October, because the 25th is a Sunday. The July and January final returns that follow then report only the remaining quarter. Zero-rated export sales count as reported only if the supporting export documents are attached to the return.
Source
부가가치세법 제48조제1항·제2항 (VAT Act, Art 48(1)–(2)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“사업자는 각 과세기간 중 다음 표에 따른 기간(이하 “예정신고기간”이라 한다)이 끝난 후 25일 이내에 대통령령으로 정하는 바에 따라 각 예정신고기간에 대한 과세표준과 납부세액 또는 환급세액을 납세지 관할 세무서장에게 신고하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 부가가치세 예정신고 — preliminary VAT return (corporations) deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

부가가치세 예정고지 — preliminary notice payment (individuals and small corporations)

부가가치세 (VAT) · Quarterly · payment

25th of the month after the quarter ends Verified 2026-10-14
Who files
Individual general taxpayers, and corporations whose supply value in the previous taxable period was under KRW 150 million; no notice is issued, and nothing is due, where the amount is under KRW 500,000 or the business switched from simplified to general at the start of the period
Notes
These businesses file no return in April or October. The tax office sends a notice in early April and early October for half of the VAT paid for the previous six months, payable by the 25th — Monday 26 October in 2026, as the 25th is a Sunday. What is paid is credited on the next final return. A business whose sales have fallen below a third of the previous period, or that wants an early refund, may file a preliminary return instead, and the notice is then cancelled.
Source
국세청 — 부가가치세 신고납부기한 (NTS: VAT filing and payment deadlines; restates VAT Act Art 48(3)) 국세청 (National Tax Service)
See the source text
“개인 일반사업자와 소규모 법인사업자(직전 과세기간 공급가액의 합계액이 1억 5천만원 미만)는 직전 과세기간(6개월) 납부세액의 50%를 예정고지서(4월·10월)에 의해 납부(예정신고의무 없음)하여야 하고, 예정고지된 세액은 다음 확정신고 시 기납부세액으로 차감됩니다.”
Screenshot of 국세청 (National Tax Service) showing the 부가가치세 예정고지 — preliminary notice payment (individuals and small corporations) deadline Open full size Captured from 국세청 (National Tax Service) on 2026-10-14

부가가치세 확정신고 — final VAT return (all general taxpayers)

부가가치세 (VAT) · Bi-annually · return filing

25th of the month after the half-year ends Verified 2026-10-14
Who files
Every general (non-simplified) taxpayer, corporate or individual, for each six-month taxable period: January–June and July–December
Notes
Due 25 July and 25 January, with payment the same day; the January–June 2027 return falls on Monday 26 July 2027 because the 25th is a Sunday. A corporation that filed in April or October reports only April–June or October–December, while an individual reports the whole six months and deducts the notice payment. A business that closes does not wait for the half-year: its last return and payment are due on the 25th of the month after the month in which it closed.
Source
부가가치세법 제49조제1항·제2항 (VAT Act, Art 49(1)–(2)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“사업자는 각 과세기간에 대한 과세표준과 납부세액 또는 환급세액을 그 과세기간이 끝난 후 25일(폐업하는 경우 제5조제3항에 따른 폐업일이 속한 달의 다음 달 25일) 이내에 대통령령으로 정하는 바에 따라 납세지 관할 세무서장에게 신고하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 부가가치세 확정신고 — final VAT return (all general taxpayers) deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

간이과세자 확정신고 — simplified taxpayer annual return

부가가치세 (VAT) — 간이과세 (simplified taxation) · Annually · return filing

25th January each year Verified 2026-10-14
Who files
Simplified taxpayers (간이과세자): individuals whose VAT-inclusive supplies in the previous calendar year were under KRW 104 million; corporations never qualify
Notes
A simplified taxpayer files one return for the calendar year and pays with it by 25 January — Monday 25 January 2027 for the 2026 year. Anything paid on the July notice is deducted. The KRW 104 million test counts sales including VAT, unlike the e-invoicing threshold. If the business closes, the return is due on the 25th of the month after the closing month rather than the following January.
Source
부가가치세법 제67조제1항 (VAT Act, Art 67(1)); taxable period Art 5(1)1 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“간이과세자는 과세기간의 과세표준과 납부세액을 그 과세기간이 끝난 후 25일(폐업하는 경우 제5조제3항에 따른 폐업일이 속한 달의 다음 달 25일) 이내에 대통령령으로 정하는 바에 따라 납세지 관할 세무서장에게 확정신고를 하고 납세지 관할 세무서장 또는 한국은행등에 납부하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 간이과세자 확정신고 — simplified taxpayer annual return deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

간이과세자 예정부과 — January–June notice payment (simplified taxpayers)

부가가치세 (VAT) — 간이과세 (simplified taxation) · Bi-annually · payment

25th of the month after the half-year ends Verified 2026-10-14
Who files
Simplified taxpayers; those that issued any tax invoices in January–June must file a January–June return and pay by the same date instead; no notice is issued where the amount is under KRW 500,000
Notes
In early July the tax office sends simplified taxpayers a notice for half of the previous year's VAT, payable by 25 July — Monday 26 July in 2027, because the 25th falls on a Sunday. A simplified taxpayer that issued tax invoices between January and June gets no notice: it must file its own return for those six months and pay by the same date. One whose sales have dropped below a third of the previous period may choose to file instead of paying the notice.
Source
부가가치세법 제66조제1항·제3항 (VAT Act, Art 66(1) and (3)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“예정부과기간이 끝난 후 25일 이내(이하 “예정부과기한”이라 한다)까지 징수한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 간이과세자 예정부과 — January–June notice payment (simplified taxpayers) deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

간편사업자 부가가치세 신고 — foreign e-service suppliers' quarterly return

부가가치세 (VAT) — electronic services by foreign suppliers · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-14
Who files
Foreign businesses with simplified registration that supply electronic services (games, audio, video, software, advertising, cloud computing, intermediation) to consumers in Korea, and platforms treated as the supplier; supplies to Korean-registered businesses are outside the scheme
Notes
Every quarter is a filing quarter for these suppliers: return and payment are due by 25 April, 25 July, 25 October and 25 January. Returns are filed online through the NTS system and the tax is paid into a Korean foreign-exchange bank account; sales received in foreign currency may be converted at the exchange rate on the last day of the period. Unlike domestic individuals, they never receive a notice in place of a return.
Source
부가가치세법 제53조의2제4항 (VAT Act, Art 53-2(4)), applying Arts 48(1)–(2) and 49 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“제52조에도 불구하고 간편사업자등록을 한 자는 대통령령으로 정하는 방법으로 제48조제1항ㆍ제2항 및 제49조에 따른 신고 및 납부를 하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 간편사업자 부가가치세 신고 — foreign e-service suppliers' quarterly return deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

대리납부 — proxy payment of VAT on services bought from foreign suppliers

부가가치세 (VAT) — 대리납부 (proxy payment) · Quarterly · payment

25th of the month after the quarter ends Verified 2026-10-14
Who files
Anyone in Korea who buys services or rights from a foreign supplier with no Korean place of business (or one not connected to the supply) and does not use them in a taxable business: individuals, exempt businesses, and taxable businesses for services whose input VAT is not deductible
Notes
When a Korean buyer pays a foreign supplier for services it will not use in a taxable business, it must collect the VAT out of the payment and pay it over with a proxy-payment return on the VAT payment dates: 25 April, 25 July, 25 October and 25 January. This catches exempt businesses such as financial, medical and educational providers, and taxable businesses buying services whose input VAT they cannot deduct. A business that uses the service in its taxable activity owes nothing here.
Source
부가가치세법 제52조제1항·제2항 (VAT Act, Art 52(1)–(2)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“제1항에 따라 부가가치세를 징수한 자는 대통령령으로 정하는 바에 따라 부가가치세 대리납부신고서를 제출하고, 제48조제2항 및 제49조제2항을 준용하여 부가가치세를 납부하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 대리납부 — proxy payment of VAT on services bought from foreign suppliers deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

매출·매입처별 세금계산서합계표 — summaries of tax invoices issued and received

부가가치세 (VAT) · Bi-annually · report / listing

25th of the month after the half-year ends Verified 2026-10-14
Who files
Businesses that issued or received paper tax invoices, or e-tax invoices whose details were not sent to the NTS by the 11th of the month after the period; e-tax invoices transmitted on time need no summary
Notes
Two lists, one of invoices by customer and one by supplier, filed with the VAT return. A corporation files them with its April or October preliminary return where it can, and otherwise may attach them to the July or January final return — the latest date allowed, which is the one shown here. Individuals paying the notice file them with the final return. Because invoices transmitted electronically on time are exempt, in practice the lists are needed only for paper invoices and late transmissions.
Source
부가가치세법 제54조제1항~제3항 (VAT Act, Art 54(1)–(3)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“해당 예정신고 또는 확정신고(제48조제3항 본문이 적용되는 경우는 해당 과세기간의 확정신고를 말한다)를 할 때 함께 제출하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 매출·매입처별 세금계산서합계표 — summaries of tax invoices issued and received deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

전자세금계산서 발급명세 전송 — e-tax invoice transmission to the NTS

부가가치세 (VAT) — 전자세금계산서 (electronic tax invoice) · One-off · report / listing

within 1 days of issuing an electronic tax invoice Verified 2026-10-14
Who files
Corporations, and individuals whose previous-year supplies at a place of business (taxable plus exempt) were KRW 80 million or more, from 1 July of the following year; also anyone who issues e-tax invoices voluntarily
Notes
The details of each e-tax invoice must reach the NTS by the day after it is issued. Invoices issued through Hometax are transmitted automatically; with private invoicing software, check that your provider sends them the next day. Late or missing transmission is penalised, and on-time transmission is also what spares a business from filing invoice summaries with its return. An individual that crosses KRW 80 million stays in the mandate even if sales later fall.
Source
부가가치세법 시행령 제68조제7항 (VAT Enforcement Decree, Art 68(7)); VAT Act Art 32(2)–(3) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“법 제32조제3항에서 “대통령령으로 정하는 기한”이란 전자세금계산서 발급일의 다음 날을 말한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 전자세금계산서 발급명세 전송 — e-tax invoice transmission to the NTS deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

월합계 세금계산서 — monthly consolidated tax invoice

부가가치세 (VAT) — 세금계산서 (tax invoice) · Monthly · other

10th of the month after the month ends Verified 2026-10-14
Who files
Any business that chooses to invoice a customer once for a calendar month, or a shorter span within it, instead of at the time of each supply
Notes
This is an invoicing deadline rather than a filing: a single tax invoice covering the month's supplies to a customer, dated the last day of that month, must be issued by the 10th of the following month. When the 10th is a Saturday, Sunday or public holiday the deadline moves to the next business day — Tuesday 12 October 2027 for September 2027, because the 10th is a Sunday and the 11th is the Hangul Day substitute holiday. Late issue is penalised, and the penalty doubles if the invoice is still not issued by the final-return deadline.
Source
국세청 — 세금계산서 발급시기 및 발급∙전송기한 (NTS: tax invoice issue and transmission deadlines; restates VAT Act Art 34(3)) 국세청 (National Tax Service)
See the source text
“(예외) 월합계 (세금)계산서 등의 경우 공급시기가 속하는 달의 다음달 10일까지 발급”
Screenshot of 국세청 (National Tax Service) showing the 월합계 세금계산서 — monthly consolidated tax invoice deadline Open full size Captured from 국세청 (National Tax Service) on 2026-10-14

사업자등록 — business registration

부가가치세 (VAT) · One-off · registration

within 20 days of commencing business at a place of business Verified 2026-10-14
Who files
Every business operator making taxable supplies, for each place of business; there is no turnover threshold
Notes
Apply to the tax office for each place of business within 20 days of starting business; a new business may also register before it starts. Registration does not depend on turnover. A foreign business with a fixed place of business in Korea registers the same way; one selling only electronic services to consumers uses the simplified registration instead.
Source
부가가치세법 제8조제1항 (VAT Act, Art 8(1)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“사업자는 사업장마다 대통령령으로 정하는 바에 따라 사업 개시일부터 20일 이내에 사업장 관할 세무서장에게 사업자등록을 신청하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 사업자등록 — business registration deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-09-30

간편사업자등록 — simplified registration for foreign e-service suppliers

부가가치세 (VAT) — electronic services by foreign suppliers · One-off · registration

within 20 days of starting to supply electronic services to consumers in Korea Verified 2026-10-14
Who files
Foreign businesses supplying electronic services to consumers in Korea, and platforms treated as the supplier; no threshold
Notes
Foreign suppliers of games, video, audio, software, advertising, cloud and intermediation services to Korean consumers register online through a simplified procedure within 20 days of starting that business. Sales to Korean-registered businesses are outside the scheme. A Korean business that uses such a service in its taxable activity owes no VAT on it; only where the service is used for exempt or non-deductible purposes does the buyer pay the VAT itself by proxy payment. Once registered, the supplier files every quarter.
Source
부가가치세법 제53조의2제1항 (VAT Act, Art 53-2(1)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“사업의 개시일부터 20일 이내에 대통령령으로 정하는 간편한 방법으로 사업자등록(이하 “간편사업자등록”이라 한다)을 하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 간편사업자등록 — simplified registration for foreign e-service suppliers deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-09-30

판매·결제 대행 자료제출 — platform and payment-agent data report

부가가치세 (VAT) — third-party data reporting · Quarterly · report / listing

15th of the month after the quarter ends Verified 2026-10-14
Who files
Online marketplace operators, payment-gateway and e-money businesses, specialised foreign-exchange businesses and similar intermediaries, including non-resident and foreign businesses, that handle sellers' sales or payments
Notes
A data report rather than a tax return: the intermediary submits the details of the sales and payments it handled for sellers by the 15th of the month after each quarter — 15 January, April, July and October. Foreign marketplaces and payment processors serving Korean sellers are caught too. Failing to submit can lead to a correction order and a fine of up to KRW 20 million.
Source
부가가치세법 제75조제1항 (VAT Act, Art 75(1)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“관련 명세를 매 분기 말일의 다음 달 15일까지 국세청장, 납세지 관할 지방국세청장 또는 납세지 관할 세무서장에게 제출하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 판매·결제 대행 자료제출 — platform and payment-agent data report deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

개별소비세 과세표준 신고 — Individual Consumption Tax quarterly return

개별소비세 (Individual Consumption Tax) · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-14
Who files
Manufacturers that remove goods subject to Individual Consumption Tax from their factory, other than fuels and tobacco (see the monthly row)
Notes
The return and the tax for each quarter's removals from the factory are due by the 25th of the following month. Racecourses, casinos and golf courses also file quarterly by the 25th, entertainment venues monthly by the 25th, and casino operators once a year by 31 March. Imported goods pay at customs. Education Tax and the Transportation-Energy-Environment Tax charged on some of these goods are separate taxes and are not covered here.
Source
개별소비세법 제9조제1항·제10조제1항 (Individual Consumption Tax Act, Arts 9(1) and 10(1)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“반출한 날이 속하는 분기의 다음 달 25일(제1조제2항제4호 또는 같은 항 제6호에 해당하는 물품은 반출한 날이 속하는 달의 다음 달 말일)까지 제조장 관할 세무서장에게 제출”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 개별소비세 과세표준 신고 — Individual Consumption Tax quarterly return deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

개별소비세 과세표준 신고 — monthly return for fuels and tobacco

개별소비세 (Individual Consumption Tax) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-14
Who files
Manufacturers removing fuels (petrol, diesel, kerosene, heavy oil, LPG, natural gas, bituminous coal and similar) or tobacco from their factory
Notes
Fuels and tobacco run on a monthly cycle with a later due day than other goods: each month's return and tax are due on the last day of the following month. A weekend or holiday pushes it to the next working day, so January 2027's return is due Tuesday 2 March 2027 — 28 February is a Sunday and 1 March is Independence Movement Day.
Source
개별소비세법 제9조제1항·제10조제1항 (Individual Consumption Tax Act, Arts 9(1) and 10(1)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“반출한 날이 속하는 분기의 다음 달 25일(제1조제2항제4호 또는 같은 항 제6호에 해당하는 물품은 반출한 날이 속하는 달의 다음 달 말일)까지 제조장 관할 세무서장에게 제출”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 개별소비세 과세표준 신고 — monthly return for fuels and tobacco deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

주세 과세표준 신고 — Liquor Tax quarterly return

주세 (Liquor Tax) · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-14
Who files
Manufacturers removing liquor from their manufacturing premises
Notes
The return for each quarter's removals is due by the 25th of the following month, and the tax is paid by the same day — Monday 26 October 2026 for July–September, as the 25th is a Sunday. Liquor treated as removed in other circumstances is reported by the last day of the following month, and imported liquor pays at customs.
Source
주세법 제9조제1항·제11조제1항 (Liquor Tax Act, Arts 9(1) and 11(1)) 국가법령정보센터 (Ministry of Government Legislation)
See the source text
“반출한 날이 속하는 분기의 다음 달 25일까지 관할 세무서장에게 제출하여야 한다.”
Screenshot of 국가법령정보센터 (Ministry of Government Legislation) showing the 주세 과세표준 신고 — Liquor Tax quarterly return deadline Open full size Captured from 국가법령정보센터 (Ministry of Government Legislation) on 2026-10-14

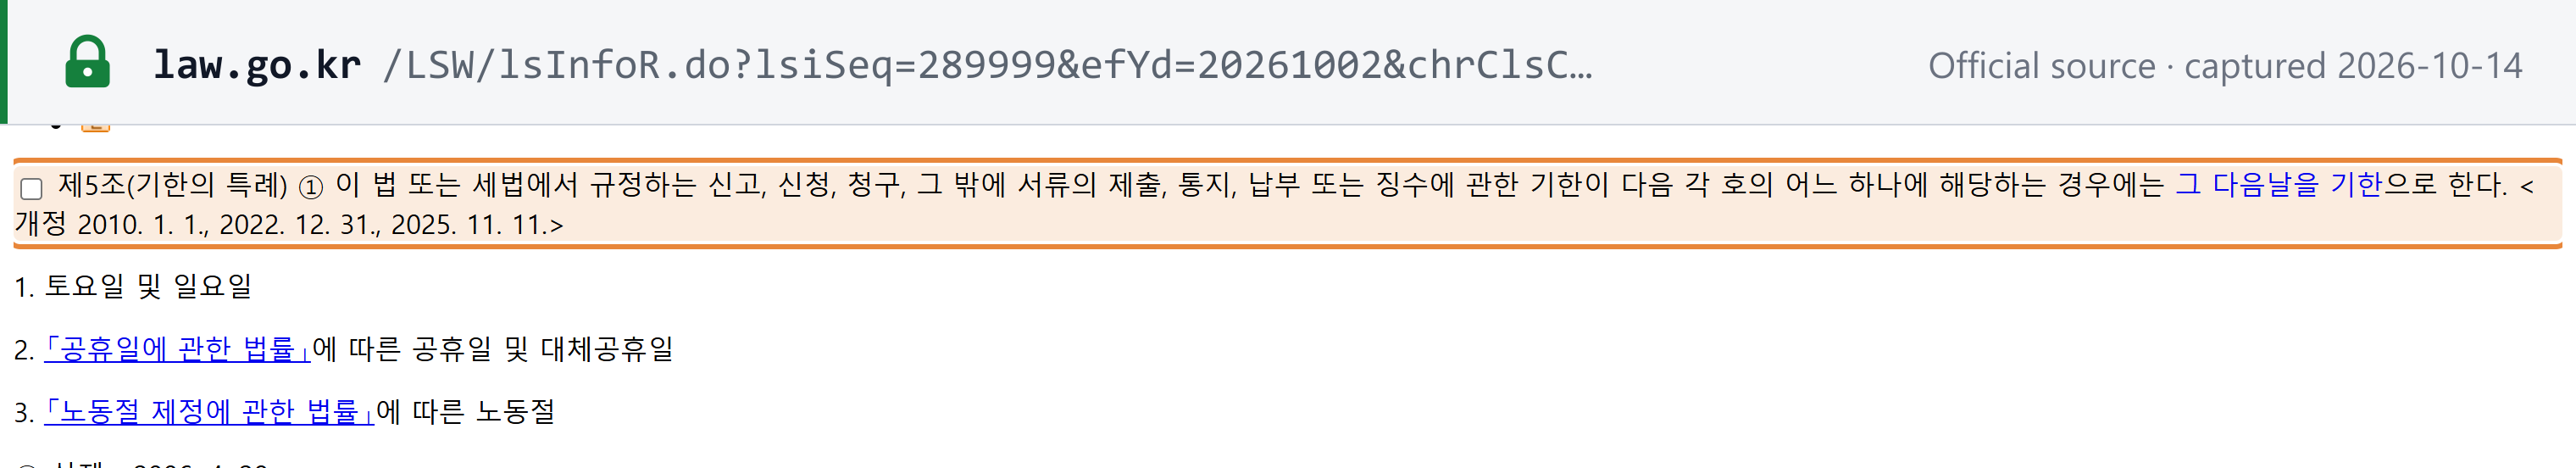
Korean VAT runs on two six-month taxable periods, each split by a three-month preliminary period. Corporations file four times a year, by 25 April, 25 July, 25 October and 25 January; individuals file twice, in July and January, and in April and October pay a notice sent by the tax office instead of filing. Simplified taxpayers file once a year, by 25 January. Payment is always due on the same day as the return. A deadline that falls on a Saturday, Sunday, public holiday, substitute holiday or Labour Day moves to the next day, and if the national tax network is down on the deadline day it moves to the day after service is restored. Import VAT is paid with customs duty at the border and is not listed here, except that eligible small and mid-sized businesses can defer it on approved imports of materials for manufacturing and settle it on their next VAT return. A Korean buyer that uses services from a foreign supplier outside a taxable business pays the VAT itself by proxy payment, on the VAT return dates; income tax and payroll deadlines are outside this calendar.

“이 법 또는 세법에서 규정하는 신고, 신청, 청구, 그 밖에 서류의 제출, 통지, 납부 또는 징수에 관한 기한이 다음 각 호의 어느 하나에 해당하는 경우에는 그 다음날을 기한으로 한다.”
Screenshot of the official source stating the rule that governs South Korea's deadlines
국세기본법 제5조제1항 (Framework Act on National Taxes, Art 5(1)) — 국가법령정보센터 (Ministry of Government Legislation), captured 2026-10-14

About this calendar

Which South Korea tax deadlines does this calendar cover?

16 recurring indirect-tax obligations — 부가가치세 (VAT), 개별소비세 (Individual Consumption Tax) and 주세 (Liquor Tax) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-14). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.