Argentina fixes the annual cap on VAT-credit refunds for subsidised public services at ARS 27.2 billion (Resolution 1759/2026)
This page records one dated change. For the rules in Argentina as they stand today, see the Argentina guide →
- Jurisdiction
- Argentina
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- FYI
- Announced
- 7 October 2026
- Authority
- Ministry of Economy, Argentina
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Public-service providers in Argentina whose tariffs are reduced by subsidies, in particular in energy and transport, claiming VAT-credit refunds under the second unnumbered article after Article 24 of the VAT Law.
No action - monitoring only.
Tax engineReporting
Argentina's Ministry of Economy (Resolución 1759/2026, dated 5 October 2026, published in the Boletín Oficial on 7 October 2026) fixed at ARS 27,200,000,000 the maximum annual amount for VAT-credit refunds under the second unnumbered article after Article 24 of the VAT Law (public-service providers whose tariffs are reduced by subsidies), for accumulated balances arising from input VAT whose right to credit arose during 2025 and earlier eligible balances not yet covered by annual caps. The cap is allocated ARS 24,500,000,000 to energy, ARS 2,500,000,000 to transport and ARS 200,000,000 to other sectors.
What changed in detail
Resolución 1759/2026 of the Ministry of Economy, dated 5 October 2026, was published in the Boletín Oficial on 7 October 2026. It fixes at ARS 27,200,000,000 the maximum annual amount available for VAT-credit refunds under the second unnumbered article after Article 24 of the VAT Law, the regime for public-service providers whose tariffs are reduced by subsidies.
The cap covers accumulated balances arising from input VAT whose right to credit arose during 2025, and earlier eligible balances not yet covered by annual caps. It is allocated ARS 24,500,000,000 to energy, ARS 2,500,000,000 to transport and ARS 200,000,000 to other sectors.
What it means
The figure is a ceiling on total refunds across all claimants in the year, not an entitlement for any one provider. Where claims exceed the sector allocation, a provider cannot assume its balance will be refunded in full.
Proof
Que, dadas las condiciones generales imperantes en materia de ingresos presupuestarios, corresponde fijar un límite máximo total de veintisiete mil doscientos millones de pesos ($ 27.200.000.000) para los saldos acumulados que tengan como origen créditos fiscales cuyo derecho a cómputo se hubiera generado durante el 2025 y para los anteriores que se encuentren en condiciones de ser recuperados y que no hayan sido objeto del mencionado régimen bajo los límites máximos aplicables a cada año.Given the general conditions prevailing in budgetary revenue, a total maximum limit of twenty-seven thousand two hundred million pesos (ARS 27,200,000,000) should be set for the accumulated balances arising from tax credits whose right to credit arose during 2025, and for earlier balances that are eligible for recovery and have not been covered by the regime under the maximum limits applicable to each year.
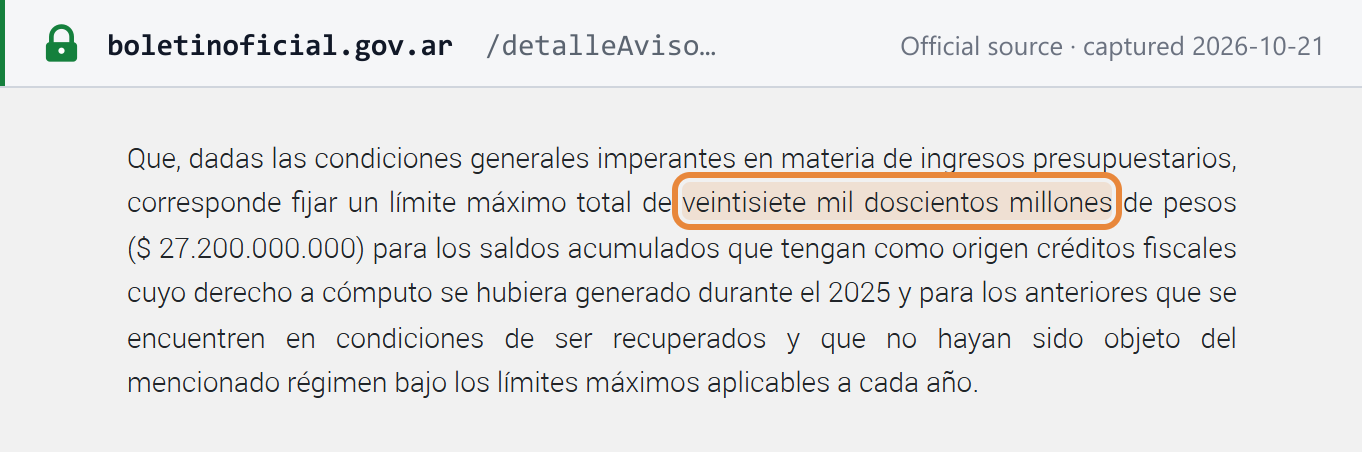 Source snapshot of the official page. Open full size ↗