Azerbaijan sets a USD 10,000 registration threshold for non-resident e-commerce suppliers (Resolution No. 295)
This page records one dated change. For the rules in Azerbaijan as they stand today, see the Azerbaijan guide →
- Jurisdiction
- Azerbaijan
- Tax
- VAT
- Change type
- Digital services
- Status
- Enacted
- Impact
- Action required
- Announced
- 14 September 2026
- Authority
- Cabinet of Ministers of the Republic of Azerbaijan
- Systems
- Tax engine, E-commerce, Invoicing, Reporting
- Verified
- Fetched from official source · high confidence
Non-resident suppliers of e-commerce services to persons in Azerbaijan not registered with the tax authorities.
Re-check whether services sold to Azerbaijan fall in the new 1.4-1 carve-outs and keep the USD 10,000 calendar-year registration trigger and 30-day deadline in the VAT engine.
Tax engineE-commerceInvoicingReporting
Cabinet of Ministers Resolution No. 295 of 14 September 2026 amends the Rules approved by Cabinet Resolution No. 387 of 30 October 2023 on electronic tax registration, VAT registration, VAT returns and VAT payment for non-residents carrying out e-commerce through internet resources. The Rules now apply to supplies to persons not registered with the tax authorities (replacing 'residents'). A non-resident whose turnover from supplies to buyers in Azerbaijan exceeds the AZN equivalent of USD 10,000 in a calendar year must register electronically within 30 days; below that turnover registration is voluntary. New point 1.4-1 provides that consulting, legal, financial, accounting, design and engineering services supplied by e-mail or other interactive means, real-time online teaching and training services, and online ordering of tickets for science, education, culture, sport and entertainment events are not treated as e-commerce services for the purposes of Tax Code article 33.8-1. The Resolution implements Law No. 355-VIIQD of 13 February 2026 and Presidential Decree No. 606 of 23 February 2026.
What changed in detail
Cabinet of Ministers Resolution No. 295 of 14 September 2026 amends the Rules approved by Cabinet Resolution No. 387 of 30 October 2023 on electronic tax registration, VAT registration, VAT returns and VAT payment for non-residents carrying out e-commerce through internet resources.
The Rules now apply to supplies to persons not registered with the tax authorities, replacing the earlier reference to “residents”. A non-resident whose turnover from supplies to buyers in Azerbaijan exceeds the AZN equivalent of USD 10,000 in a calendar year must register electronically within 30 days; below that turnover registration is voluntary.
A new point 1.4-1 provides that consulting, legal, financial, accounting, design and engineering services supplied by e-mail or other interactive means, real-time online teaching and training services, and online ordering of tickets for science, education, culture, sport and entertainment events are not treated as e-commerce services for the purposes of Tax Code article 33.8-1.
The Resolution implements Law No. 355-VIIQD of 13 February 2026 and Presidential Decree No. 606 of 23 February 2026.
What it means
Two points are easy to misread. The USD 10,000 figure is a mandatory-registration trigger, not a VAT-free allowance, and voluntary registration below it remains possible. And the new point 1.4-1 carves out a defined list of services delivered by e-mail or in real time; suppliers of professional or training services should check whether their offer falls inside that list before concluding they are outside the e-commerce rules.
Proof
dövriyyəsi təqvim ili ərzində 10 000 ABŞ dollarının manat ekvivalentini keçdikdən sonra 30 gün müddətində elektron qaydada vergi uçotunaafter turnover exceeds the manat equivalent of USD 10,000 in a calendar year, within 30 days, electronically for tax registration
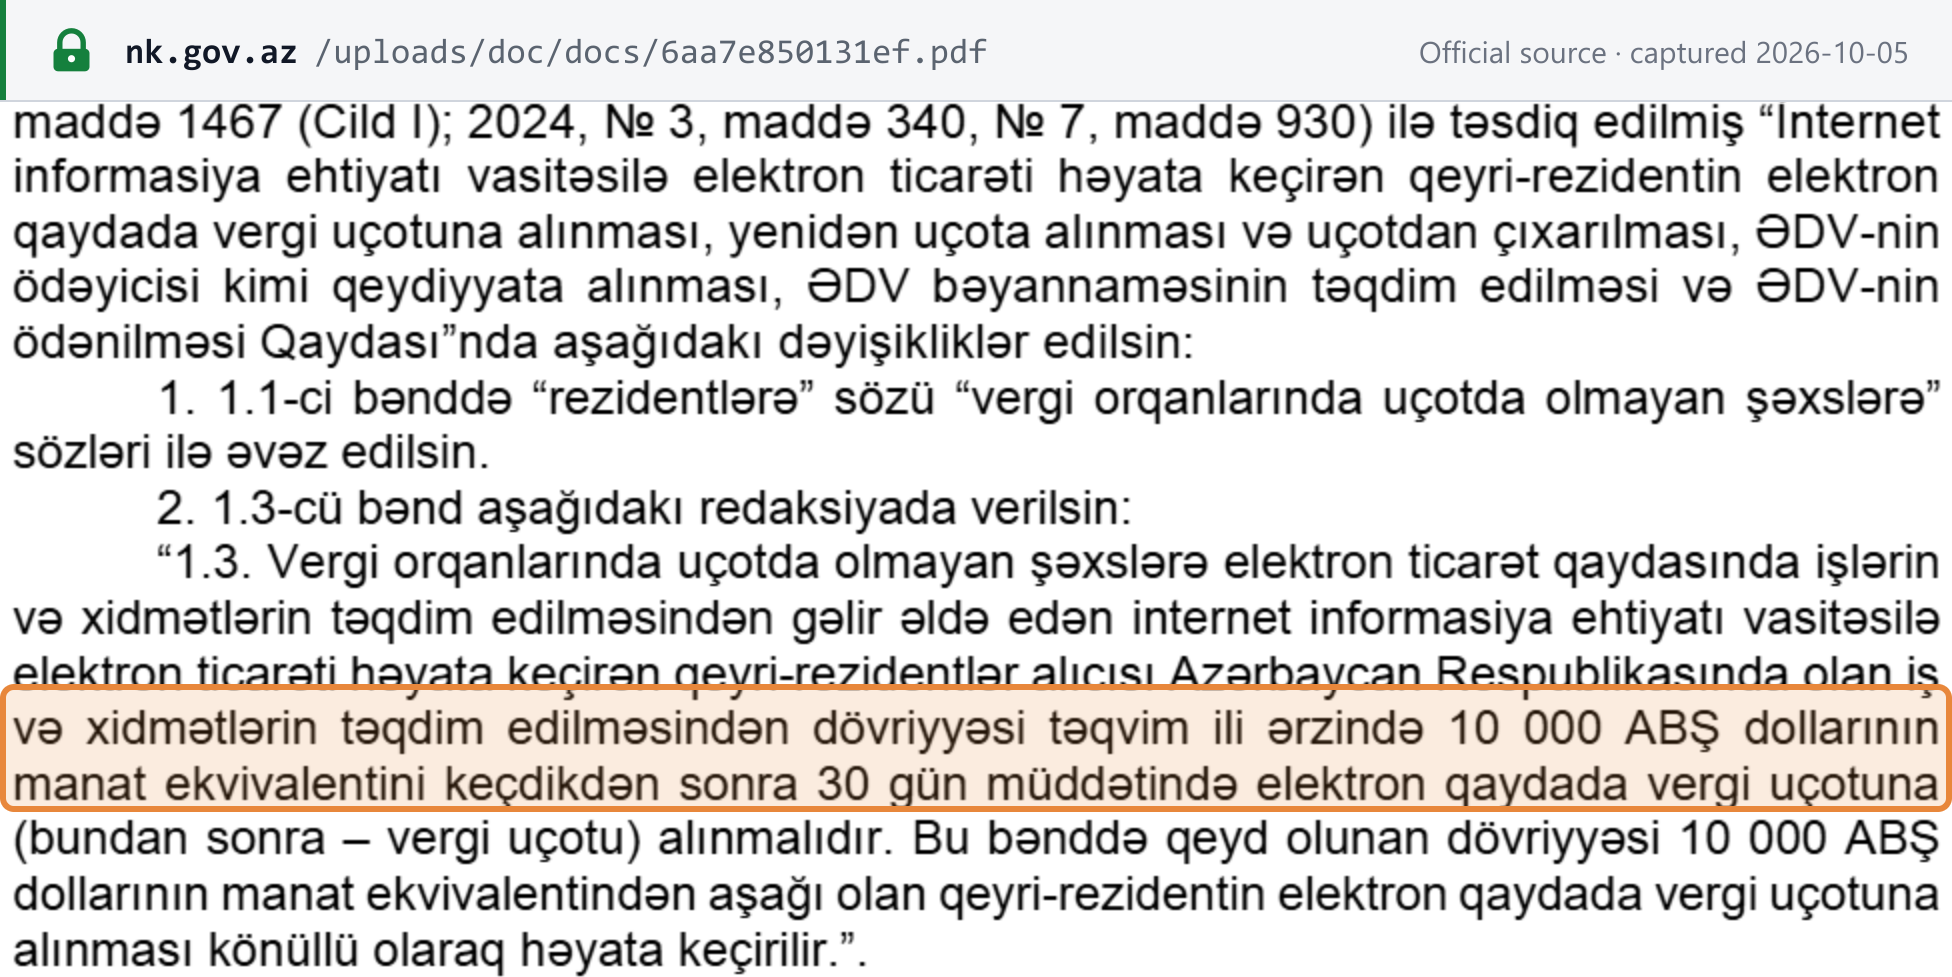 Source snapshot of the official page. Open full size ↗