Azerbaijan amends the VAT and customs-duty import relief lists for the liberated territories (Resolution No. 264)
This page records one dated change. For the rules in Azerbaijan as they stand today, see the Azerbaijan guide →
- Jurisdiction
- Azerbaijan
- Tax
- VAT
- Change type
- Update
- Status
- Enacted
- Impact
- FYI
- Announced
- 8 September 2026
- Authority
- Cabinet of Ministers of the Republic of Azerbaijan
- Systems
- Customs, Tax engine
- Verified
- Fetched from official source · high confidence
Investors and businesses importing machinery, equipment and materials for projects in the liberated territories of Azerbaijan.
No action — monitoring only. Importers into the liberated territories re-map goods to the amended lists.
CustomsTax engine
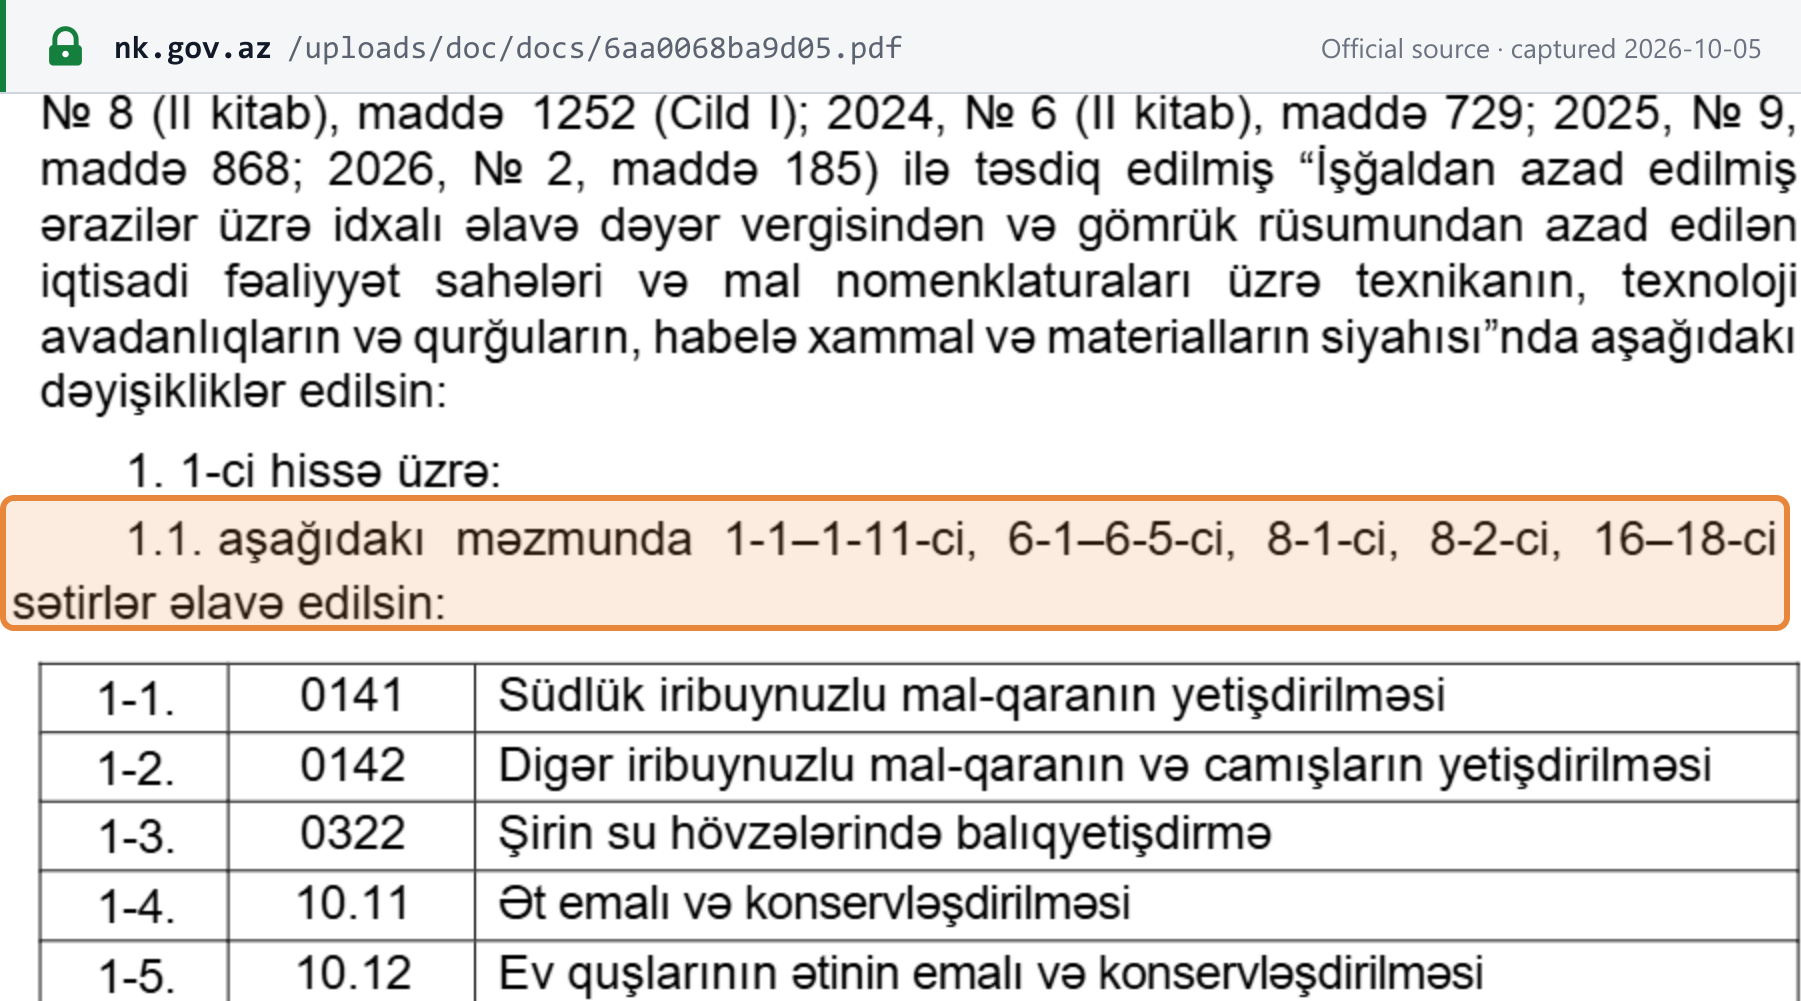
Cabinet of Ministers Resolution No. 264 of 8 September 2026 amends the list approved by Cabinet Resolution No. 269 of 5 August 2023 of economic-activity areas and commodity nomenclatures (machinery, technological equipment, installations, raw materials and materials) whose import into the liberated territories is exempt from VAT and customs duty. It adds activity lines (including cattle and buffalo breeding, freshwater fish farming, meat, fish, fats, dairy, animal-feed and wine processing, pharmaceutical products, selected plastics, glass and metal manufacturing, renewable electricity, research and development) and amends the eligible-goods lists. Relief for the added investment-project activity lines 1-1 to 1-11 applies only to imports of machinery, technological equipment and installations.
What changed in detail
Cabinet of Ministers Resolution No. 264 of 8 September 2026 amends the list approved by Cabinet Resolution No. 269 of 5 August 2023 of economic-activity areas and commodity nomenclatures (machinery, technological equipment, installations, raw materials and materials) whose import into the liberated territories is exempt from VAT and customs duty.
It adds activity lines including cattle and buffalo breeding, freshwater fish farming, meat, fish, fats, dairy, animal-feed and wine processing, pharmaceutical products, selected plastics, glass and metal manufacturing, renewable electricity, and research and development (renewable electricity excludes entities 50% or more owned by the state). It also amends the eligible-goods lists: it deletes rows 120–122 and 243, and adds note 3, under which goods on the second and third lists qualify only where their production is set up under an activity on the first list.
Relief for the added investment-project activity lines 1-1 to 1-11 applies only to imports of machinery, technological equipment and installations.
What it means
The scope differs by line. For investment-project lines 1-1 to 1-11 the relief covers machinery, technological equipment and installations only, so raw materials and materials imported for those lines are not covered. Importers should match both their activity and each commodity code against the amended list before claiming the relief.
Proof
aşağıdakı məzmunda 1-1–1-11-ci, 6-1–6-5-ci, 8-1-ci, 8-2-ci, 16–18-ci sətirlər əlavə edilsinrows 1-1 to 1-11, 6-1 to 6-5, 8-1, 8-2 and 16 to 18 shall be added with the following content
 Source snapshot of the official page. Open full size ↗