Barbados: approved rental car companies charge 10% VAT and a 2.5% Product Development Levy from 1 October 2026
- Jurisdiction
- Barbados
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 30 September 2026
- Effective
- 1 October 2026
- Authority
- Barbados Revenue Authority
- Systems
- Invoicing, POS, Tax engine, ERP
- Verified
- Fetched from official source · high confidence
Rental car companies approved as Direct Tourism Services providers under the Tourism Levy Act; their customers.
Rental car operators should confirm BTPA/BRA approval and apply 10% VAT plus the 2.5% levy on eligible rentals from 1 October 2026.
InvoicingPOSTax engineERP
The Barbados Revenue Authority issued Policy Note OGC No. 004/2026 (dated 30 September 2026, posted on the BRA site on 15 October 2026) stating that from 1 October 2026 approved rental car companies are designated Direct Tourism Services providers under section 3(1) of the Tourism Levy Act, 2019-57, implementing the 2026/2027 Budgetary Proposals announcement of 16 March 2026. Taxable supplies by approved rental car companies are subject to 10% VAT from 1 October 2026 and a 2.5% Product Development Levy on the amount paid. Approval requires registration with the BTPA, BRA and Customs, VAT/NIS/tax compliance, and evidence that at least 60% of revenue for the past three income years was foreign-sourced and deposited in the domestic banking system.
What changed in detail
Policy Note OGC No. 004/2026 of the Barbados Revenue Authority is dated 30 September 2026 and was posted on the BRA site on 15 October 2026. It states that from 1 October 2026 approved rental car companies are designated Direct Tourism Services providers under section 3(1) of the Tourism Levy Act, 2019-57, implementing the announcement in the 2026/2027 Budgetary Proposals of 16 March 2026.
Taxable supplies by approved rental car companies are subject to 10% VAT from 1 October 2026, and a 2.5% Product Development Levy applies to the amount paid for the Direct Tourism Service.
Approval requires registration with the BTPA, the BRA and Customs, VAT, NIS and tax compliance, and evidence that at least 60% of revenue for the past three income years was foreign-sourced and deposited in the domestic banking system.
What it means
The 10% rate applies only to companies that are approved, so the practical question for a rental business is whether it meets the 60% foreign-revenue test and has completed the three registrations. The note was posted on the BRA site two weeks after the date it takes effect, so companies should check whether they have charged tax correctly since 1 October 2026.
Proof
Taxable Supplies made by approved rental car companies will be subject to 10% VAT effective October 1, 2026.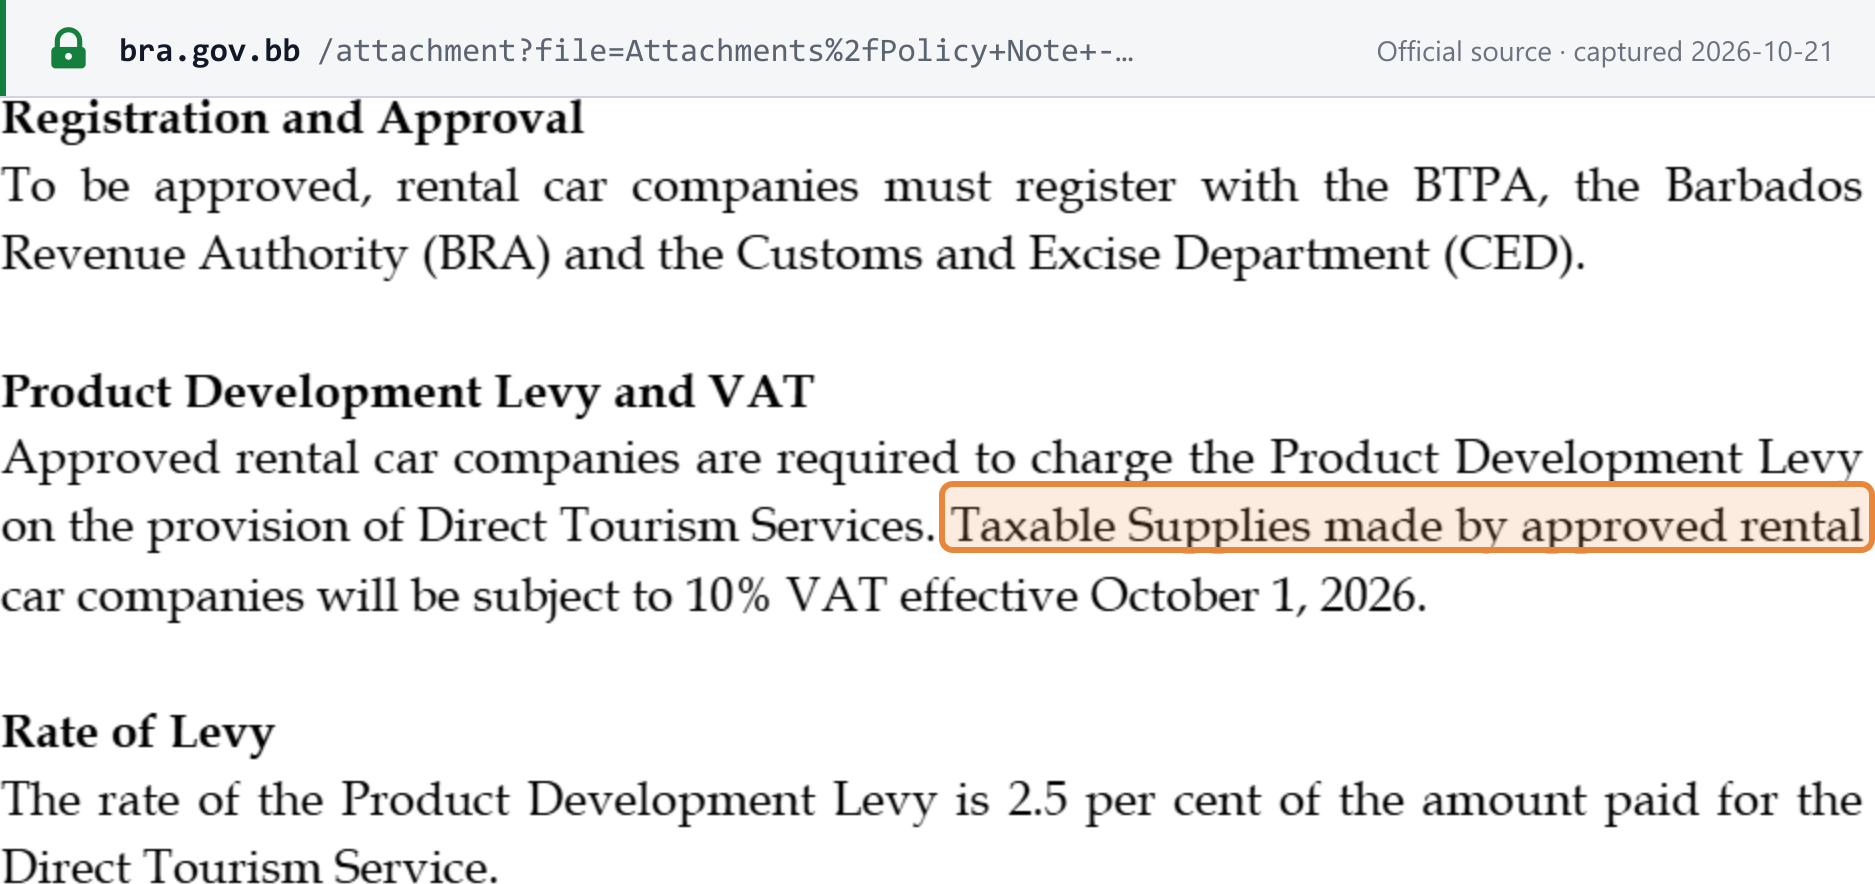 Source snapshot of the official page. Open full size ↗