Belarus confirms the VAT-exclusive price is what counts when a vehicle bought from an individual is resold below residual value
- Jurisdiction
- Belarus
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- FYI
- Announced
- 2 September 2026
- Effective
- 1 January 2026
- Authority
- Министерство по налогам и сборам Республики Беларусь (Ministry of Taxes and Duties)
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Belarusian businesses reselling a fixed asset that is a vehicle within Annex 25 to the Tax Code, acquired from an individual less than five years earlier, at a price below its residual value.
Businesses reselling vehicles previously bought from individuals within the last five years should use the VAT-exclusive sale price, not the VAT-inclusive price, when comparing against appraised/residual value under Tax Code Art. 120(42)(42.3).
Tax engine
Belarus's Ministry of Taxes and Duties (MNS) published guidance on 2 September 2026 (extract of Letter No. 2-1-12/Ro-01085 of 1 September 2026) clarifying application of Tax Code Art. 120, para 42, subpara 42.3, part 3 (effective from 2026): when a vehicle bought from an individual less than five years earlier is resold below residual value, the sale price used to compare against the vehicle's appraised value and/or residual value must be net of VAT (not VAT-inclusive), with a worked numeric example.
What changed in detail
The Ministry of Taxes and Duties of the Republic of Belarus published an extract of Letter No. 2-1-12/Ро-01085 of 1 September 2026 on its clarifications page on 2 September 2026, on how the VAT base is determined when a vehicle previously acquired from an individual is resold.
The letter works through a case. A passenger car held as a fixed asset, bought from an individual in 2023 — less than five years earlier — for BYN 150,000, is sold in 2026 for BYN 95,000. Its residual value at the date of sale is BYN 91,716.51. The appraised value determined by an authorised valuer is BYN 95,040 including VAT of BYN 15,840, that is BYN 79,200 excluding VAT.
Under point 40 of article 120 of the Tax Code, a sale below residual value of such a vehicle is taxed under subpoint 42.3 of point 42 of article 120, whose part two bases the tax on the sale price where it is at or above the appraised value, and on the appraised value where it is below.
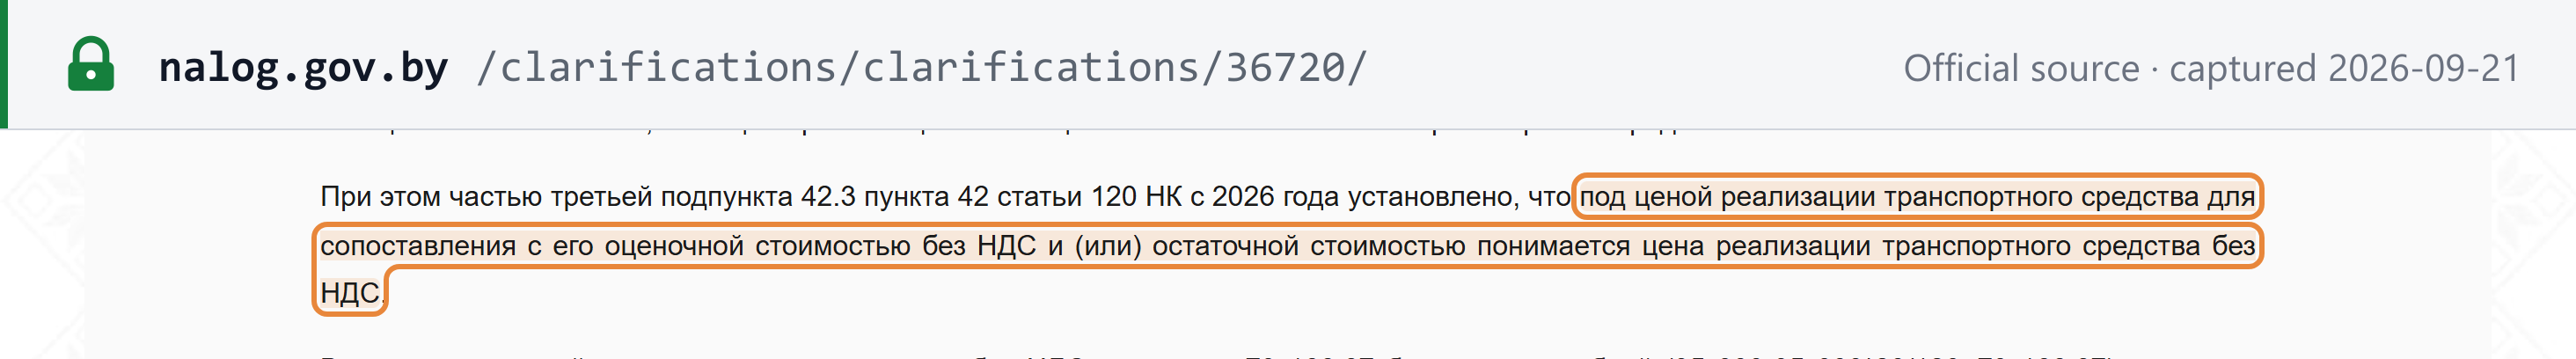
Part three of subpoint 42.3, established from 2026, provides that the sale price to be compared with the appraised value excluding VAT and/or the residual value means the sale price excluding VAT. In the example, that price is BYN 79,166.67 — below both — so the base is the VAT-exclusive appraised value of BYN 79,200, and BYN 95,040 is reported in column 2 of line 1 of section I of the VAT return.
What it means
The arithmetic in the worked example is the whole point. The VAT-inclusive price of BYN 95,000 sits above the VAT-exclusive appraised value; the VAT-exclusive price of BYN 79,166.67 sits below it, by BYN 33. Comparing the wrong figure flips the base from the appraised value to the sale price, and the error lands straight in the declared amount.
Two practical consequences. The comparison is now like-for-like — an ex-VAT price against an ex-VAT valuation — which is what makes the test readable rather than arbitrary. And it depends on the valuer’s report stating the VAT split: with no BYN 15,840 line there is no ex-VAT appraised value to compare against. That is something to ask for at the valuation stage, not when the return is being prepared.
Proof
При этом частью третьей подпункта 42.3 пункта 42 статьи 120 НК с 2026 года установлено, что под ценой реализации транспортного средства для сопоставления с его оценочной стоимостью без НДС и (или) остаточной стоимостью понимается цена реализации транспортного средства без НДС.At the same time, part three of subpoint 42.3 of point 42 of article 120 of the Tax Code establishes, from 2026, that the sale price of a vehicle for comparison with its appraised value excluding VAT and/or its residual value means the sale price of the vehicle excluding VAT.
 Source snapshot of the official page. Open full size ↗