Belgium: Finance Committee adopts the VAT in the Digital Age bill (DOC 56 1718) for 2027 and 2029
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Belgium as they stand today, see the Belgium guide →
- Jurisdiction
- Belgium
- Tax
- VAT
- Change type
- Registration
- Status
- Proposed
- Impact
- Watch
- Announced
- 2 October 2026
- Effective
- 1 January 2027
- Authority
- Belgian Chamber of Representatives
- Systems
- Tax engine, E-commerce, Reporting
- Verified
- Fetched from official source · high confidence
Businesses using call-off stock, EU online platforms and the One Stop Shop (OSS), and small-business-franchise users of the import scheme (IOSS).
Cross-border B2C sellers, platforms and OSS users: review OSS place-of-supply, deemed-supplier and own-goods-transfer processes ahead of 1 January 2027.
Tax engineE-commerceReporting
The Chamber of Representatives Finance and Budget Committee adopted on 23 September 2026 (11 votes in favour, 2 abstentions; committee report DOC 56 1718/002 and adopted text 003 published 2 October 2026) bill DOC 56 1718 amending the VAT Code to apply the VAT in the Digital Age rules effective 1 January 2027 and 1 July 2029, partially transposing Directive (EU) 2025/516. Measures reported by the Minister include: phase-out of the call-off stock simplification (transfers after 30 June 2028 no longer qualify, transitional rules end 30 June 2029); extension of the deemed-supplier rule for electronic platforms facilitating supplies by non-EU sellers to further categories of buyers; clarification that the EUR 10,000 cross-border threshold counts only supplies from the single Member State of establishment; a taxable person registered in the OSS is deemed to have exercised the option for the general place-of-supply rules; and exclusion of small-business-franchise users from the import scheme (IOSS, article 58quinquies of the VAT Code). The bill remains pending in the Chamber.
What changed in detail
This is a bill that has passed committee, not yet law. The Chamber of Representatives Finance and Budget Committee adopted bill DOC 56 1718 on 23 September 2026 (11 votes in favour, 2 abstentions); its report (DOC 56 1718/002) and the adopted text (003) were published on 2 October 2026. It amends the VAT Code to apply the VAT in the Digital Age rules from 1 January 2027 and 1 July 2029, partially transposing Directive (EU) 2025/516. The bill remains pending in the Chamber.
Measures reported by the Minister include:
- phase-out of the call-off stock simplification: transfers after 30 June 2028 no longer qualify, and transitional rules end on 30 June 2029;
- extension of the deemed-supplier rule for electronic platforms facilitating supplies by non-EU sellers to further categories of buyers;
- clarification that the EUR 10,000 cross-border threshold counts only supplies from the single Member State of establishment;
- a taxable person registered in the OSS is deemed to have exercised the option for the general place-of-supply rules;
- exclusion of small-business-franchise users from the import scheme (IOSS, article 58quinquies of the VAT Code).
What it means
The text can still change at plenary and does not bind anyone yet. The practical timing is the call-off stock phase-out, which gives businesses until 30 June 2028 for new transfers and until 30 June 2029 for existing arrangements. Platforms and OSS users should read the platform and place-of-supply measures closely, and franchise-scheme businesses that sell imported goods through the IOSS should note that they would be excluded from that scheme, as those are the points most likely to change their obligations.
Proof
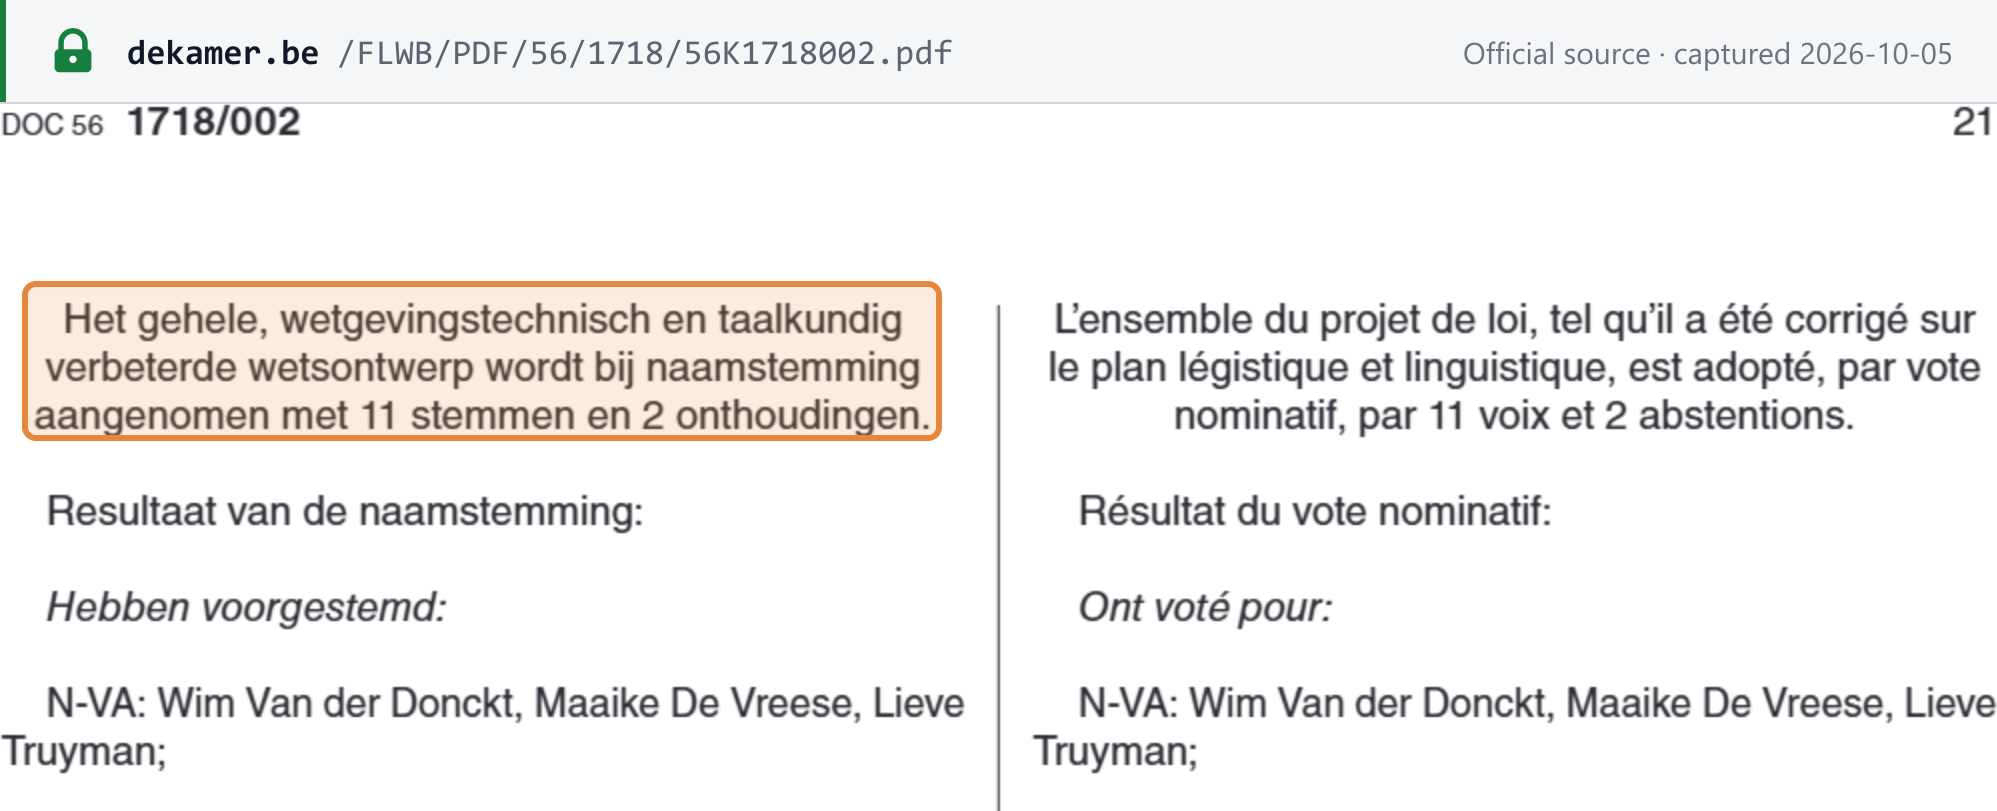
Het gehele, wetgevingstechnisch en taalkundig verbeterde wetsontwerp wordt bij naamstemming aangenomen met 11 stemmen en 2 onthoudingen.The whole bill, as improved legislatively and linguistically, is adopted by roll-call vote with 11 votes in favour and 2 abstentions.
 Source snapshot of the official page. Open full size ↗