Bolivia abrogates the online-invoicing implementation deadlines for the ninth to twelfth taxpayer groups (RND 102600000038)
This page records one dated change. For the rules in Bolivia as they stand today, see the Bolivia guide →
- Jurisdiction
- Bolivia
- Tax
- VAT (IVA)
- Change type
- E-invoicing
- Status
- In force
- Impact
- Action required
- Announced
- 30 September 2026
- Effective
- 30 September 2026
- Authority
- Servicio de Impuestos Nacionales (SIN), Bolivia
- Systems
- Invoicing, POS
- Verified
- Fetched from official source · high confidence
IVA taxpayers in Bolivia that had not implemented any online invoicing modality at the date of publication.
Taxpayers in groups 9-12: stop working to the old fixed deadlines; expect SIN to assign an online invoicing modality and prepare the invoicing system for it.
InvoicingPOS
Resolución Normativa de Directorio No. 102600000038 of the Servicio de Impuestos Nacionales (La Paz, 30 September 2026) abrogates RND 102400000004, 102400000005, 102400000012 and 102400000025 and their amendments, which designated the ninth, tenth, eleventh and twelfth taxpayer groups to implement an online invoicing modality; its preamble recites the 2025-2026 transitional RNDs on that implementation, including RND 102600000007 of 23 March 2026, which had set the deadline at 30 September 2026. The SIN will instead assign an online invoicing modality periodically to IVA taxpayers that had not implemented any online modality at the date of publication. The stated reason is the application of Ley 1733 of 27 May 2026 (IVA computed on the net sale price and shown separately on the tax document).
What changed in detail
Resolución Normativa de Directorio No. 102600000038 of the Servicio de Impuestos Nacionales (La Paz, 30 September 2026) abrogates RND 102400000004, 102400000005, 102400000012 and 102400000025 and their amendments. Those RNDs designated the ninth, tenth, eleventh and twelfth taxpayer groups to implement an online invoicing modality. Its preamble recites the 2025-2026 transitional RNDs on that implementation, including RND 102600000007 of 23 March 2026, which had set the deadline at 30 September 2026; the operative article abrogates only the four designation RNDs and their amendments.
In their place, the SIN will assign an online invoicing modality periodically to IVA taxpayers that had not implemented any online modality at the date of publication.
The stated reason is the application of Ley 1733 of 27 May 2026, under which IVA is computed on the net sale price and shown separately on the tax document.
What it means
The fixed group-by-group deadlines no longer exist, so taxpayers in the four affected groups are not bound by those dates. That is not an exemption: the SIN will assign a modality to taxpayers who have not yet adopted one, with timing still to be announced. Taxpayers should watch for their assignment rather than assume they are out of scope.
Proof
asignará periódicamente una modalidad de facturación en línea a aquellos contribuyentes sujetos pasivos del IVA que, a la fecha de publicación de la presente Resolución Normativa de Directorio, aún no hayan implementado ninguna modalidad en línea.will periodically assign an online invoicing modality to those VAT taxpayers who, at the date of publication of this Resolution, have not yet implemented any online modality.
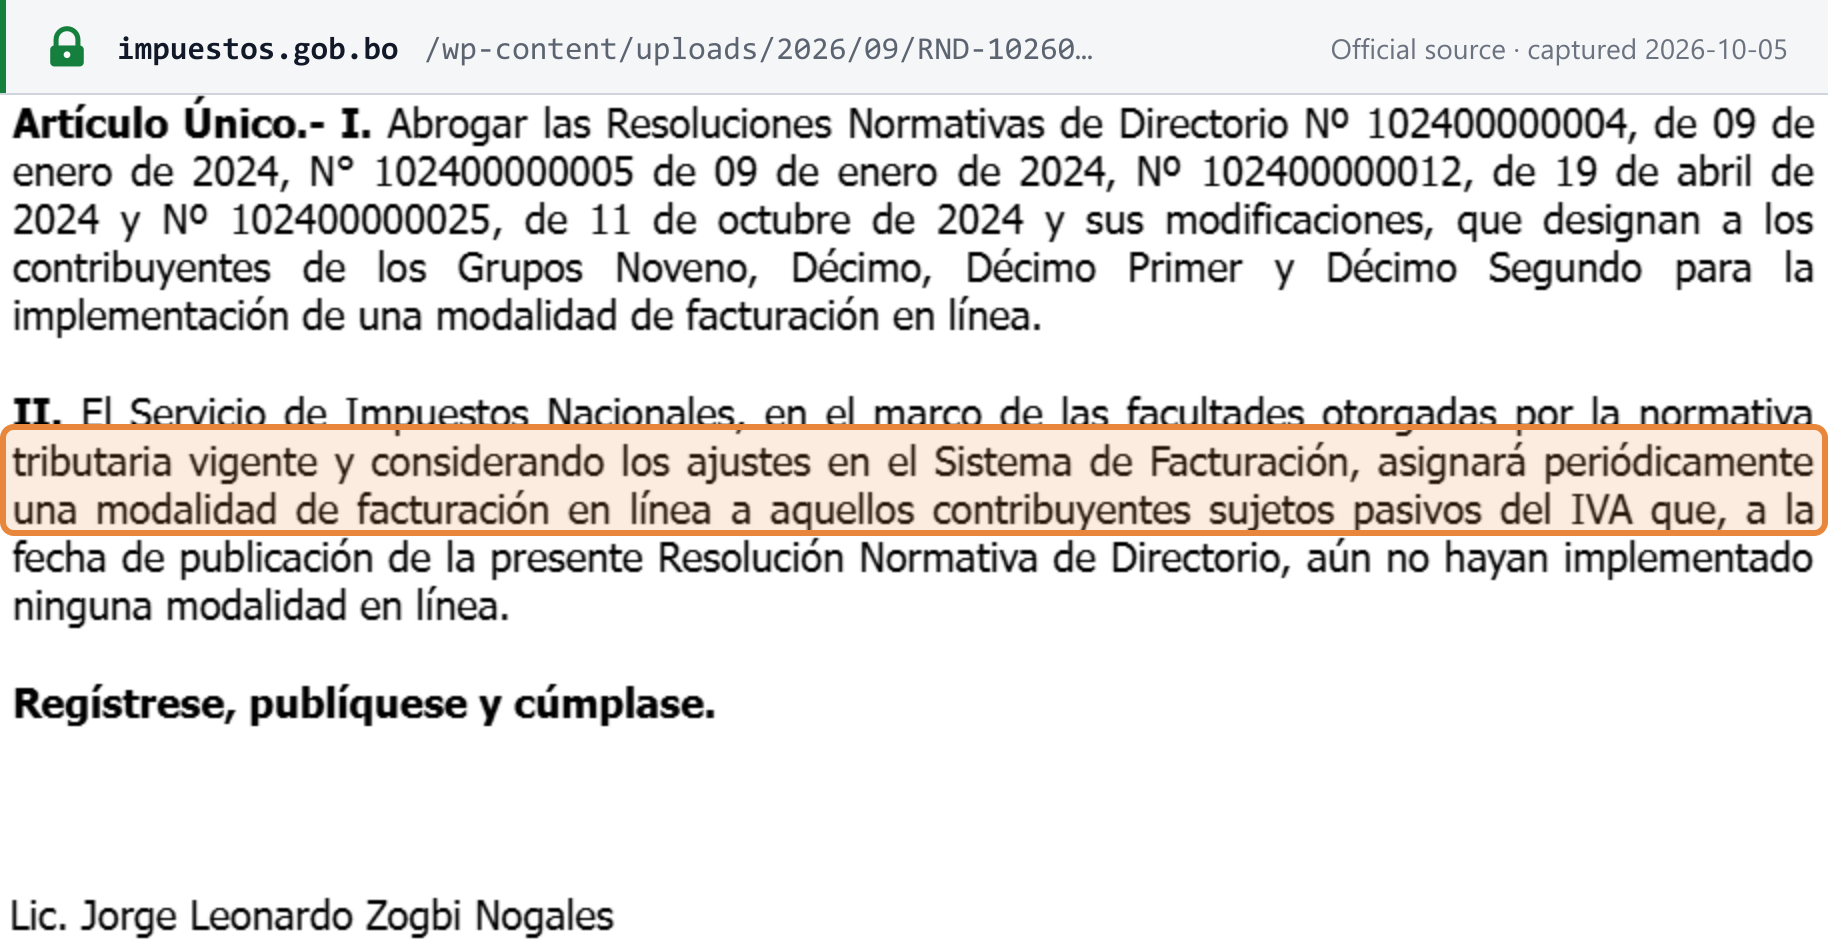 Source snapshot of the official page. Open full size ↗