British Columbia exempts accounting, architectural, engineering, real estate and security services from PST from 1 October 2026
This page records one dated change. For the rules in Canada as they stand today, see the Canada guide →
- Jurisdiction
- Canada (British Columbia)
- Tax
- PST
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 21 September 2026
- Effective
- 1 October 2026
- Authority
- BC Ministry of Finance
- Systems
- Tax engine, Invoicing, ERP
- Verified
- Fetched from official source · high confidence
Buyers of accounting, architectural, engineering, non-residential real estate and security services in British Columbia.
Do not charge 7% PST on BC accounting, architectural, engineering, non-residential real estate or security services from 1 October 2026; revert any tax-engine rules configured for the expansion.
Tax engineInvoicingERP
British Columbia Order in Council No. 408/2026, approved 21 September 2026 under the Provincial Sales Tax Act ss. 236 and 241, (a) effective 30 September 2026 amends B.C. Reg. 114/2026 by repealing section 4 of Schedule 1 and section 4 of Schedule 2, and (b) effective 1 October 2026 adds Divisions 4.1-4.5 to Part 4 of the Provincial Sales Tax Exemption and Refund Regulation (B.C. Reg. 97/2013), exempting accounting services, architectural services, engineering services, non-residential real estate services and security services from the tax imposed under Divisions 4.1-4.5 of Part 5 of the Act. The order states no end date.
What changed in detail
British Columbia Order in Council No. 408/2026, approved on 21 September 2026 under sections 236 and 241 of the Provincial Sales Tax Act, does two things.
Effective 30 September 2026, it amends B.C. Reg. 114/2026 by repealing section 4 of Schedule 1 and section 4 of Schedule 2.
Effective 1 October 2026, it adds Divisions 4.1 to 4.5 to Part 4 of the Provincial Sales Tax Exemption and Refund Regulation (B.C. Reg. 97/2013). These exempt accounting services, architectural services, engineering services, non-residential real estate services and security services from the tax imposed under Divisions 4.1 to 4.5 of Part 5 of the Act.
The order states no end date.
What it means
The exemption removes PST from five named service categories from 1 October 2026 with no stated expiry. Service providers and their customers should check invoices and systems so tax is no longer charged on the exempted services from that date. The repeal of the two Schedule provisions takes effect a day earlier, on 30 September 2026, so the two dates are not the same.
Proof
82.1 Accounting services are exempt from tax imposed under Division 4.1 of Part 5 of the Act.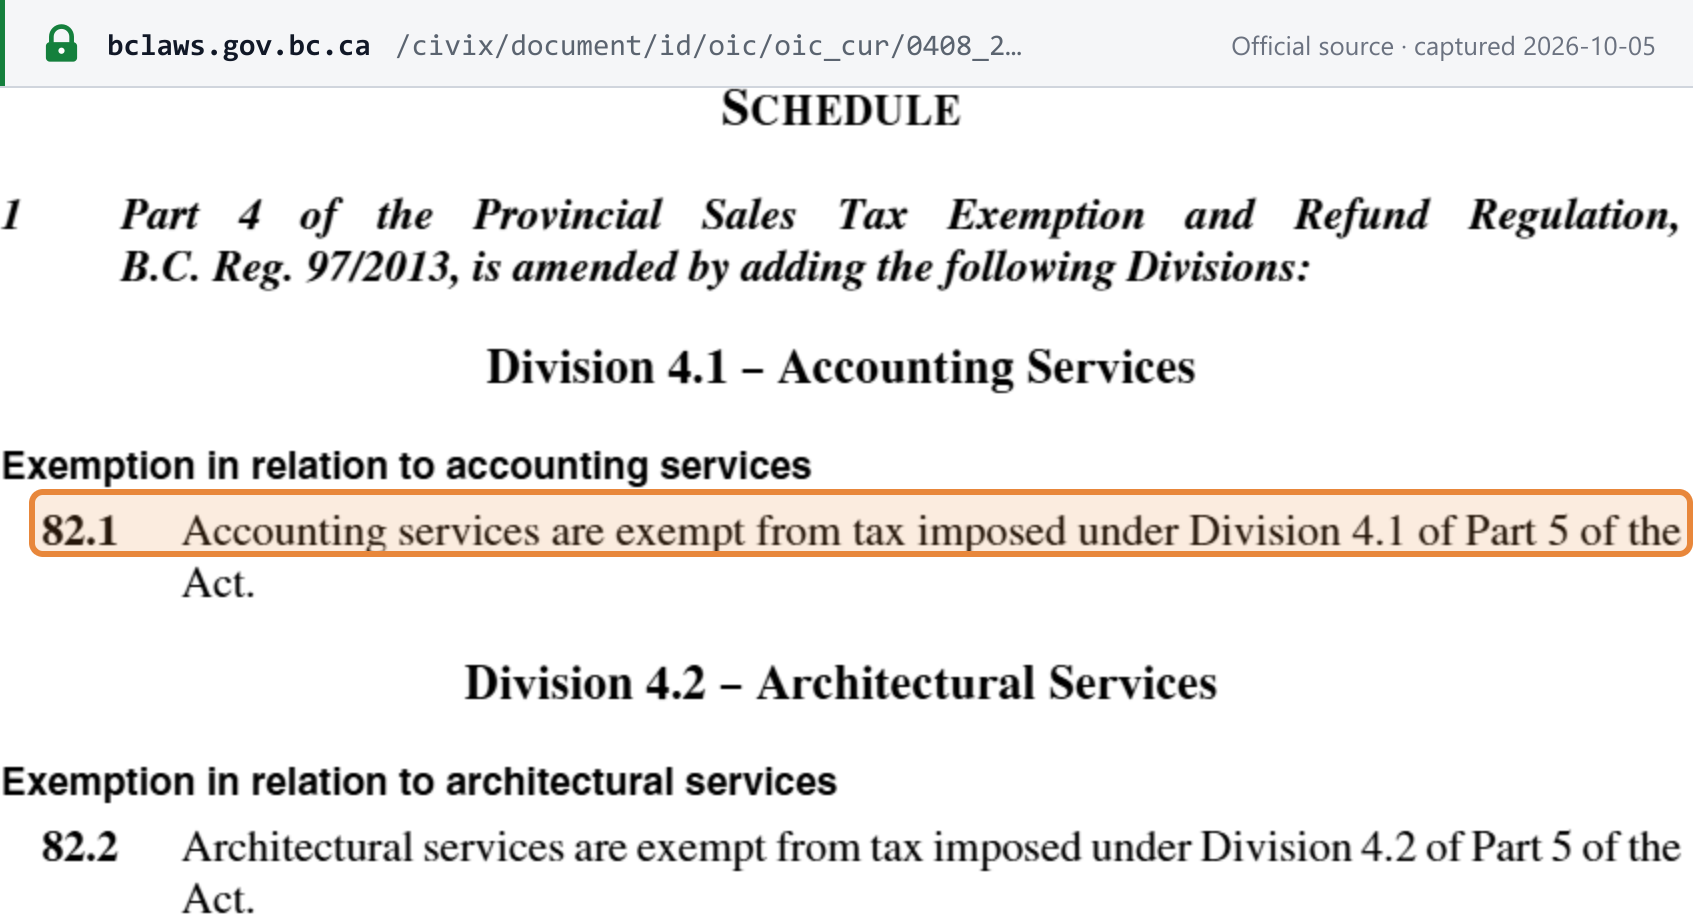 Source snapshot of the official page. Open full size ↗