Colombia exempts musical works from IVA and excludes instruments and related items owned by non-mass artists under Ley 2615 of 2026
- Jurisdiction
- Colombia
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- FYI
- Announced
- 29 July 2026
- Effective
- 29 July 2026
- Authority
- Congreso de la República de Colombia
- Systems
- Tax engine, Invoicing
- Verified
- Fetched from official source · high confidence
Composers, publishers and producers of musical works, non-mass artists (as the Government will define them) and sellers of their instruments and equipment, and instrument makers registered in Simus.
No action — monitoring only (music-sector sellers: check the qualification rules the Government is to issue).
Tax engineInvoicing
Colombia's Ley 2615 of 29 July 2026 (Ley de la música, Diario Oficial No. 53.568), article 16, rewrites article 478 of the Estatuto Tributario: musical works (compositions, scores, arrangements, original phonograms, physical or digital) are exempt from IVA, musical instruments, specialised sound-editing software/hardware and phonogram licensing intermediation services owned by non-mass artists, as qualified by the Government, are excluded from IVA; and inputs used exclusively by instrument makers registered in Simus are also excluded.
What changed in detail
Ley 2615 of 29 July 2026 (Ley de la música, Diario Oficial No. 53.568) rewrites article 478 of the Estatuto Tributario through its article 16.
Musical works are exempt from IVA. This covers compositions, scores, arrangements and original phonograms, in physical or digital format.
Musical instruments, specialised software and hardware for sound editing and creation, and licensing intermediation services for phonograms online are excluded from IVA where they are owned by non-mass artists, as qualified by the Government.
Raw materials, inputs, parts and specialised tools used exclusively to make, repair, maintain or assemble musical instruments are also excluded when used by makers registered in Simus. This exclusion depends on that exclusive use and registration, not on Government qualification.
What it means
Exempt and excluded are different treatments in Colombian IVA. They differ in whether input tax can be recovered, so the label attached to each item matters for pricing and for the VAT position of the supplier.
The exclusion for instruments, equipment and licensing services turns on ownership by non-mass artists, a category the Government still has to qualify, so sellers should not assume every instrument or tool falls in automatically. Check which category each product line falls into before changing invoicing.
Proof
se entenderán igualmente exentas las obras musicales, incluidas las composiciones, partituras, arreglos, fonogramas originales y demás expresiones creativas musicales, en formato físico o digital, por considerarse productos culturales equiparables a los libros y revistas.musical works, including compositions, scores, arrangements, original phonograms and other creative musical expressions, in physical or digital format, will likewise be understood as exempt, as they are cultural products comparable to books and magazines.
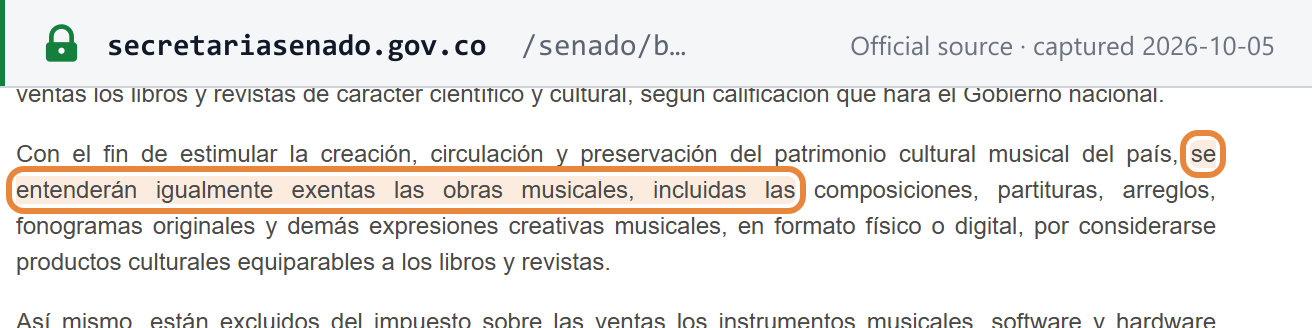 Source snapshot of the official page. Open full size ↗