Croatia moves fiscalisation signing onto eIDAS trust-service digital certificates from 1 January 2027
- Jurisdiction
- Croatia
- Tax
- VAT
- Change type
- E-invoicing
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 2 September 2026
- Effective
- 1 January 2027
- Authority
- Narodne novine (Official Gazette of the Republic of Croatia)
- Systems
- Invoicing, POS
- Verified
- Fetched from official source · medium confidence
Obligors of receipt fiscalisation under article 6 of the Zakon o fiskalizaciji, including operators of self-service devices, and anyone testing the fiscalisation procedure under article 14(4).
Businesses in scope of Croatia's Fiskalizacija 2.0 regime should review the amended Rulebook (NN 97/26) for changes to fiscalization/e-invoicing procedure once the full text is confirmed.
InvoicingPOS
Croatia's Tax Administration (Porezna uprava) confirmed publication, in Narodne novine (Official Gazette) issue 97/26 of 3 September 2026, of a Pravilnik o izmjenama i dopunama Pravilnika o fiskalizaciji računa u krajnjoj potrošnji (Rulebook amending the Rulebook on Fiscalization of Receipts in Final Consumption) under the Fiskalizacija 2.0 e-invoicing/fiscalization regime.
What changed in detail
The Pravilnik o izmjenama i dopunama Pravilnika o fiskalizaciji računa u krajnjoj potrošnji was made by the Minister of Finance under article 32 of the Zakon o fiskalizaciji (NN 89/25), signed in Zagreb on 27 August 2026 (Klasa 011-01/26-02/10, Urbroj 513-07-21-01-26-15) and published as NN 97/2026-1181, ELI /eli/sluzbeni/2026/97/1181. Article 13 brings it into force on 1 January 2027.
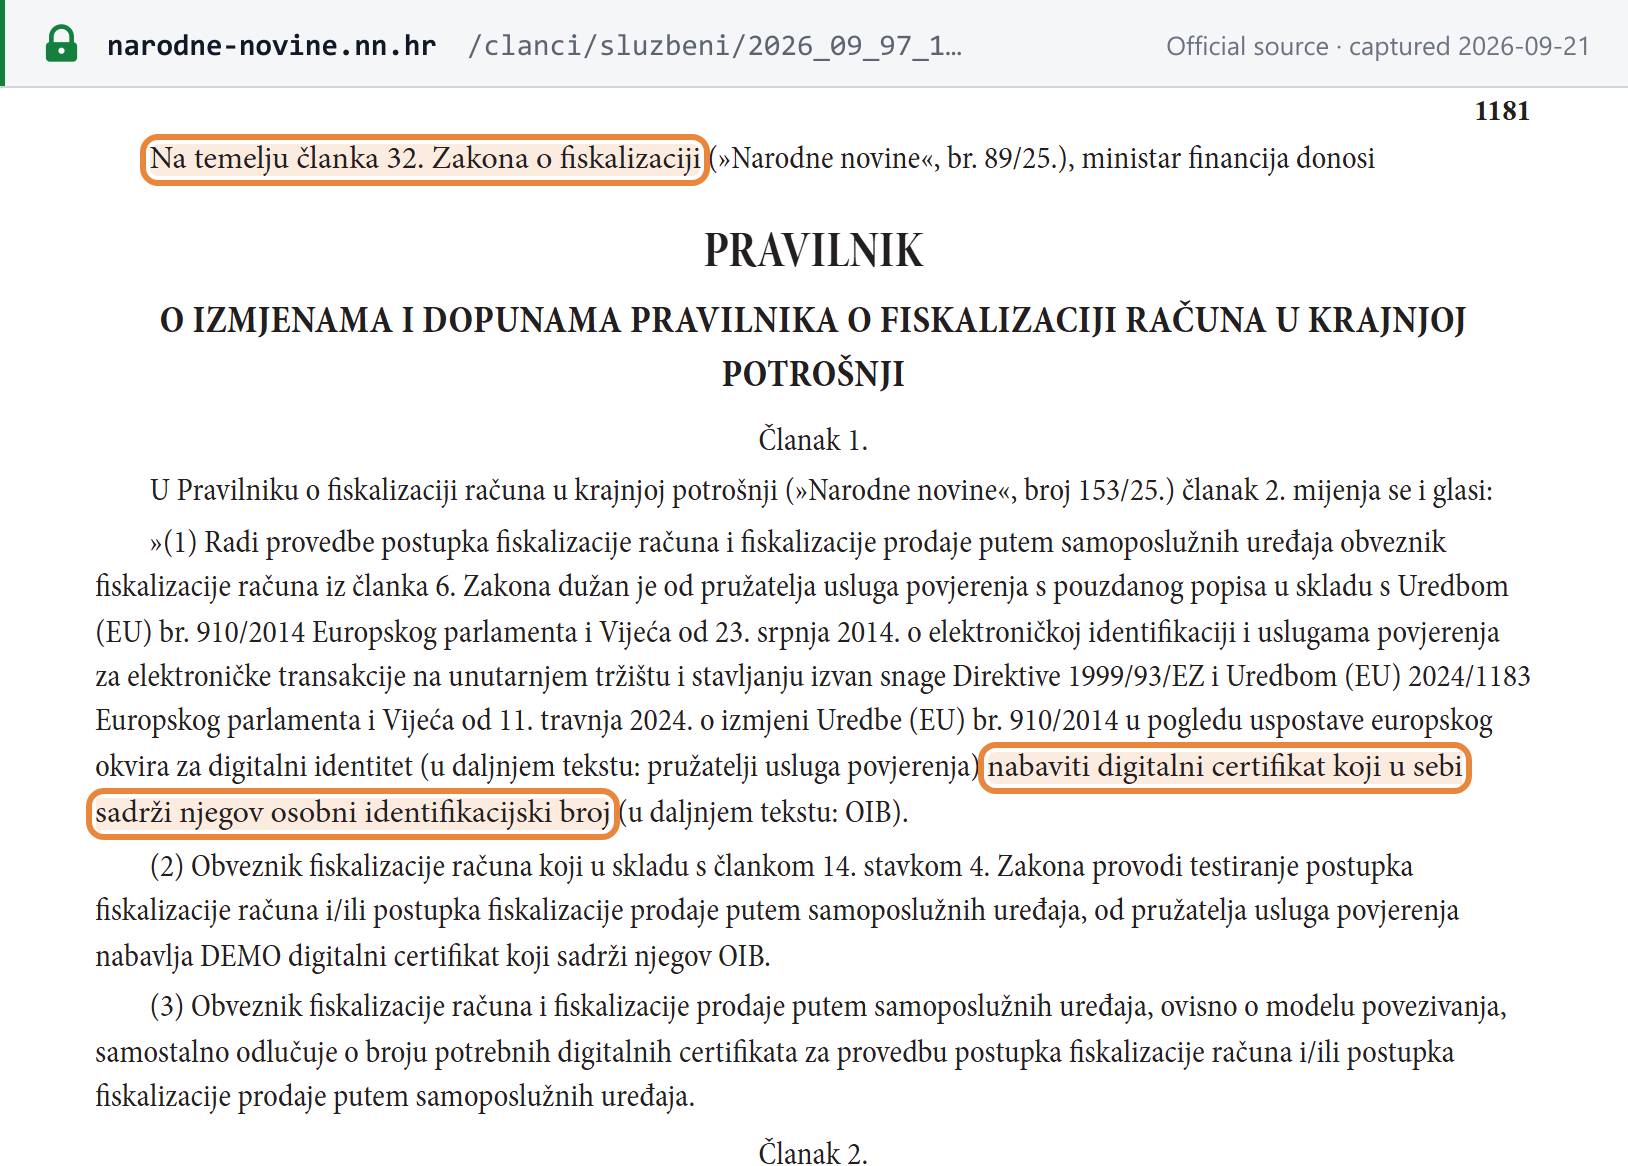
Article 1 replaces article 2 of the base Rulebook (NN 153/25). A fiscalisation obligor under article 6 of the Act must obtain, from a trust service provider on the eIDAS trusted list — under Regulation (EU) No 910/2014 as amended by Regulation (EU) 2024/1183 — a digital certificate carrying its OIB. Obligors testing the procedure under article 14(4) obtain a DEMO certificate carrying the same OIB, and each obligor decides for itself how many certificates its connection model requires.
The rest follows from that. Article 11 replaces “aplikacijski certifikat” and “produkcijski aplikacijski certifikat” with “digitalni certifikat” throughout, and drops the restriction to trust service providers established in Croatia. Article 5 ties electronic signing to a valid trust-service digital certificate under the methods set in the Tehnička specifikacija published on the Porezna uprava website, and fixes the hash output as a 32-character hexadecimal string printed on the receipt. Article 2 deletes article 4; articles 6, 7 and 10 strip paragraphs from articles 23 and 47. Article 8 adds card, mobile-application and similar payment methods to article 27(2). Article 12 lets certificates issued before commencement run to expiry.
What it means
The headline is not the certificate — it is the removal of “u Republici Hrvatskoj” from the issuer requirement. Any provider on the EU trusted list now qualifies, so a group with one certificate authority across several member states no longer needs a separate Croatian issuer for fiscalisation.
The transitional in article 12 is generous and easy to misread. Existing certificates stay valid to their own expiry, which means the practical migration date is not 1 January 2027 but whenever each certificate lapses — and a fleet bought at different times will lapse at different times. Build the inventory now rather than at renewal.
One smaller item is worth a ticket: article 5 pushes the signing methods and the hash format into the Tehnička specifikacija, so the Porezna uprava can change them without another gazette entry. Track that document, not just this one.
Proof
(1) Radi provedbe postupka fiskalizacije računa i fiskalizacije prodaje putem samoposlužnih uređaja obveznik fiskalizacije računa iz članka 6. Zakona dužan je od pružatelja usluga povjerenja s pouzdanog popisa u skladu s Uredbom (EU) br. 910/2014 Europskog parlamenta i Vijeća od 23. srpnja 2014. o elektroničkoj identifikaciji i uslugama povjerenja za elektroničke transakcije na unutarnjem tržištu i stavljanju izvan snage Direktive 1999/93/EZ i Uredbom (EU) 2024/1183 Europskog parlamenta i Vijeća od 11. travnja 2024. o izmjeni Uredbe (EU) br. 910/2014 u pogledu uspostave europskog okvira za digitalni identitet (u daljnjem tekstu: pružatelji usluga povjerenja) nabaviti digitalni certifikat koji u sebi sadrži njegov osobni identifikacijski broj (u daljnjem tekstu: OIB).(1) In order to carry out the receipt fiscalisation procedure and the fiscalisation of sales through self-service devices, an obligor of receipt fiscalisation under article 6 of the Act is required to obtain, from a trust service provider on the trusted list in accordance with Regulation (EU) No 910/2014 of the European Parliament and of the Council of 23 July 2014 on electronic identification and trust services for electronic transactions in the internal market and repealing Directive 1999/93/EC and Regulation (EU) 2024/1183 of the European Parliament and of the Council of 11 April 2024 amending Regulation (EU) No 910/2014 as regards establishing the European Digital Identity Framework (hereinafter: trust service providers), a digital certificate containing its personal identification number (hereinafter: OIB).
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · NN 97/2026-1181, ELI /eli/sluzbeni/2026/97/1181 — Pravilnik o izmjenama i dopunama Pravilnika o fiskalizaciji računa u krajnjoj potrošnji, članak 1. · narodne-novine.nn.hr
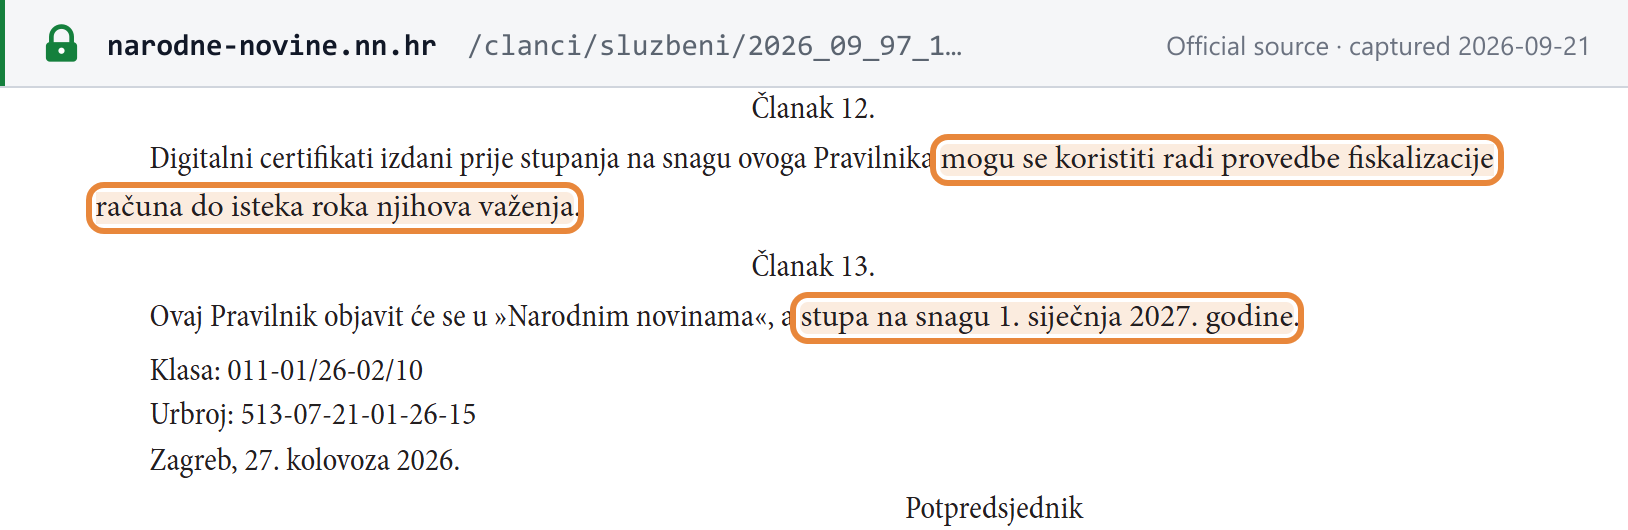
Digitalni certifikati izdani prije stupanja na snagu ovoga Pravilnika mogu se koristiti radi provedbe fiskalizacije računa do isteka roka njihova važenja. Članak 13. Ovaj Pravilnik objavit će se u »Narodnim novinama«, a stupa na snagu 1. siječnja 2027. godine.Digital certificates issued before the entry into force of this Rulebook may be used to carry out receipt fiscalisation until their period of validity expires. Article 13. This Rulebook shall be published in the "Narodne novine" and shall enter into force on 1 January 2027.
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · NN 97/2026-1181 — članci 12. i 13., transitional rule and entry into force · narodne-novine.nn.hr