Cyprus's zero VAT rate on fresh meat and fish expires on 30 September 2026
This page records one dated change. For the rules in Cyprus as they stand today, see the Cyprus guide →
- Jurisdiction
- Cyprus
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 31 March 2026
- Effective
- 30 September 2026
- Authority
- Τμήμα Φορολογίας / Cyprus Tax Department (gov.cy)
- Systems
- POS, ERP, Invoicing
- Verified
- Fetched from official source · high confidence
Cyprus retailers, wholesalers and importers supplying fresh, simply chilled or frozen meat and fish in the listed CN codes.
Revert POS, invoicing and pricing systems to the standard/previously-applicable VAT rate on fresh/chilled/frozen meat and fish supplies made on or after 1 October 2026.
POSERPInvoicing
Under Decree K.D.P. 168/2026 (published in the Official Gazette, Annex III(I), No. 6012, 27 March 2026), Cyprus's VAT Law was amended to impose a zero VAT rate on supplies of fresh, simply chilled or frozen meat and fish (specified CN tariff codes) from 6 April 2026 to 30 September 2026, after which the zero rate expires and the previously applicable VAT rate resumes for these products. Prepared meat/fish products (marinated, smoked, sausages, canned fish, etc.) remain at the reduced 5% rate throughout.
What changed in detail
Under Decree K.D.P. 168/2026, published in the Official Gazette of the Republic (Ε.Ε.Παρ. ΙΙΙ(Ι), Αρ. 6012) on 27 March 2026 by decision of the Council of Ministers, the VAT Law was amended to impose a zero VAT rate on supplies of meat and fish from 6 April 2026 until 30 September 2026. The Tax Department announced it on 31 March 2026.
The relief is defined by tariff classification rather than by description. It covers:
- Fresh, simply chilled or frozen meat — bovine (CN 0201, 0202), pig (CN 0203), sheep and goat (CN 0204), edible offal of those animals (CN ex 0206), poultry meat and edible offal of heading 0105 birds (CN 0207), and rabbit and hare meat and edible offal (CN ex 0208).
- Fresh, simply chilled or frozen fish — fish (CN 0302, 0303, 0304) and cuttlefish, squid and octopus (CN 0307).
The Tax Department notes that preparations of meat and fish continue to carry the reduced 5% VAT rate throughout — marinated, smoked and wine-cured meats, sieftalia, burgers, chicken nuggets, sausages, lountza, roasts, gyros and polony, as well as canned fish, smoked fish, marinated and breaded fish.
The decree fixes its own end date. On 1 October 2026 the zero rate ceases to apply to these supplies and the previously applicable rate resumes.
What it means
The date that matters is the one nobody gets a reminder for. The zero rate arrived with an announcement; its expiry arrives with nothing, because it was written into the decree back in March. Systems configured in April with an open-ended zero rate will keep applying it on 1 October unless someone goes back and puts the end date in.
The classification split is the second risk. Zero-rating attaches to CN codes for fresh, chilled and frozen product; anything prepared stays at 5%. A product master that groups “meat” or “fish” as a single category cannot express that, and after 30 September it has to express something harder still: two rates that changed on different dates for lines sitting next to each other on the same shelf.
Proof
με βάση το Διάταγμα Κ.Δ.Π. 168/2026, το οποίο δημοσιεύτηκε στην Επίσημη Εφημερίδα της Δημοκρατίας (Ε.Ε.Παρ.ΙΙΙ (Ι), Αρ. 6012, 27.3.2026) με απόφαση του Υπουργικού Συμβουλίου, τροποποιείται ο περί Φόρου Προστιθέμενης Αξίας (ΦΠΑ) Νόμος, ώστε να επιβάλλεται μηδενικός συντελεστής ΦΠΑ σε παραδόσεις κρεάτων και ψαριών από 6 Απριλίου 2026 μέχρι 30 Σεπτεμβρίου 2026on the basis of Decree K.D.P. 168/2026, which was published in the Official Gazette of the Republic (Ε.Ε.Παρ. ΙΙΙ(Ι), No. 6012, 27.3.2026) by decision of the Council of Ministers, the Value Added Tax (VAT) Law is amended so that a zero VAT rate is imposed on supplies of meat and fish from 6 April 2026 until 30 September 2026
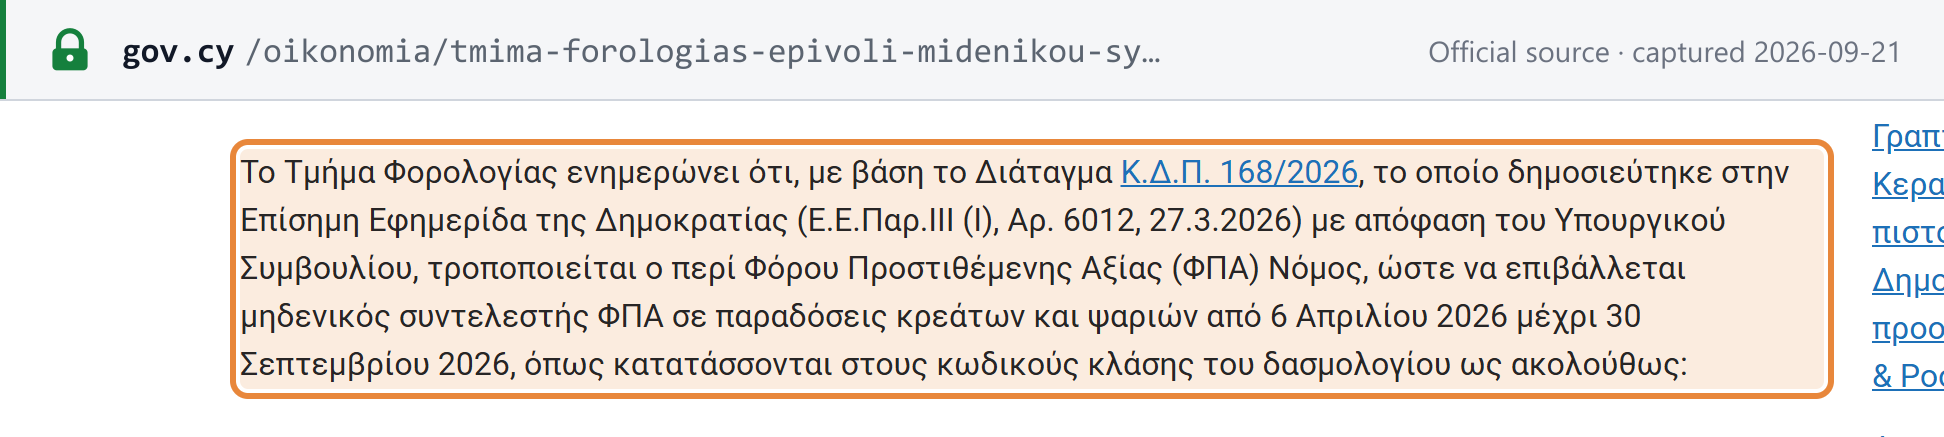 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Τμήμα Φορολογίας announcement of 31 March 2026 on Διάταγμα Κ.Δ.Π. 168/2026 (Ε.Ε.Παρ. ΙΙΙ(Ι), Αρ. 6012, 27.3.2026) · www.gov.cy