Czech Republic: a government bill, not yet law, would move kratom from the 12% reduced VAT rate to the 21% standard rate from 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Czech Republic as they stand today, see the Czech Republic guide →
- Jurisdiction
- Czech Republic
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 29 September 2026
- Effective
- 1 January 2027
- Authority
- Poslanecká sněmovna Parlamentu České republiky
- Systems
- Tax engine, POS, E-commerce
- Verified
- Fetched from official source · high confidence
Czech sellers, importers and exporters of kratom and kratom extract, and travellers bringing kratom into the Czech Republic.
No action — monitoring only.
Tax enginePOSE-commerce
The Czech government bill amending the Addictive Substances Act (Sněmovní tisk 321, 'Novela z. o návykových látkách - EU', submitted to the Chamber of Deputies on 29 September 2026; placed on the agenda of the 34th session from 13 October 2026, first reading not yet concluded at 21 October) would, in Article X, amend the VAT Act: items 01-05, 07-23, 25 and 07-12 of Annex 3 (reduced-rate goods) would exclude psychomodulatory substances under the Addictive Substances Act, which the explanatory report states currently means only kratom and kratom extract and which would thereby move from the 12% reduced rate to the 21% standard rate; export of such substances would be excluded from the section 66(4) zero-rating; and a new section 71ba would exempt import by travellers of up to 50 g (non-liquid) or 10 ml (liquid) of kratom, not for travellers under 21. The bill also introduces a kratom excise duty. Proposed effective date 1 January 2027. Bill stage; text may change in the Chamber.
What changed in detail
This is a government bill, not law. The Czech government bill amending the Addictive Substances Act (Sněmovní tisk 321, ‘Novela z. o návykových látkách - EU’) was submitted to the Chamber of Deputies on 29 September 2026. It was placed on the agenda of the 34th session from 13 October 2026, and first reading had not concluded at 21 October.
In Article X the bill amends the VAT Act. Items 01-05, 07-23, 25 and 07-12 of Annex 3 (reduced-rate goods) would exclude psychomodulatory substances under the Addictive Substances Act. The explanatory report states that this currently means only kratom and kratom extract, which would move from the 12% reduced rate to the 21% standard rate. Export of such substances would be excluded from the section 66(4) zero-rating. A new section 71ba would exempt import by travellers of up to 50 g (non-liquid) or 10 ml (liquid) of kratom, not for travellers under 21. The bill also introduces a kratom excise duty. The proposed effective date is 1 January 2027.
What it means
The text may change in the Chamber. If it passes as drafted, kratom sellers would face a nine-point higher VAT rate and lose zero-rating on exports from 1 January 2027, alongside the new excise duty.
Proof
3. V příloze č. 3 se na konci položky 01-05, 07-23, 25 a na konci položky 07-12 na samostatný řádek doplňuje věta: „Mimo psychomodulační látky podle zákona upravujícího návykové látky.“.3. In Annex 3, at the end of items 01-05, 07-23, 25 and at the end of item 07-12, the following sentence is added on a separate line: "Excluding psychomodulatory substances under the law governing addictive substances."
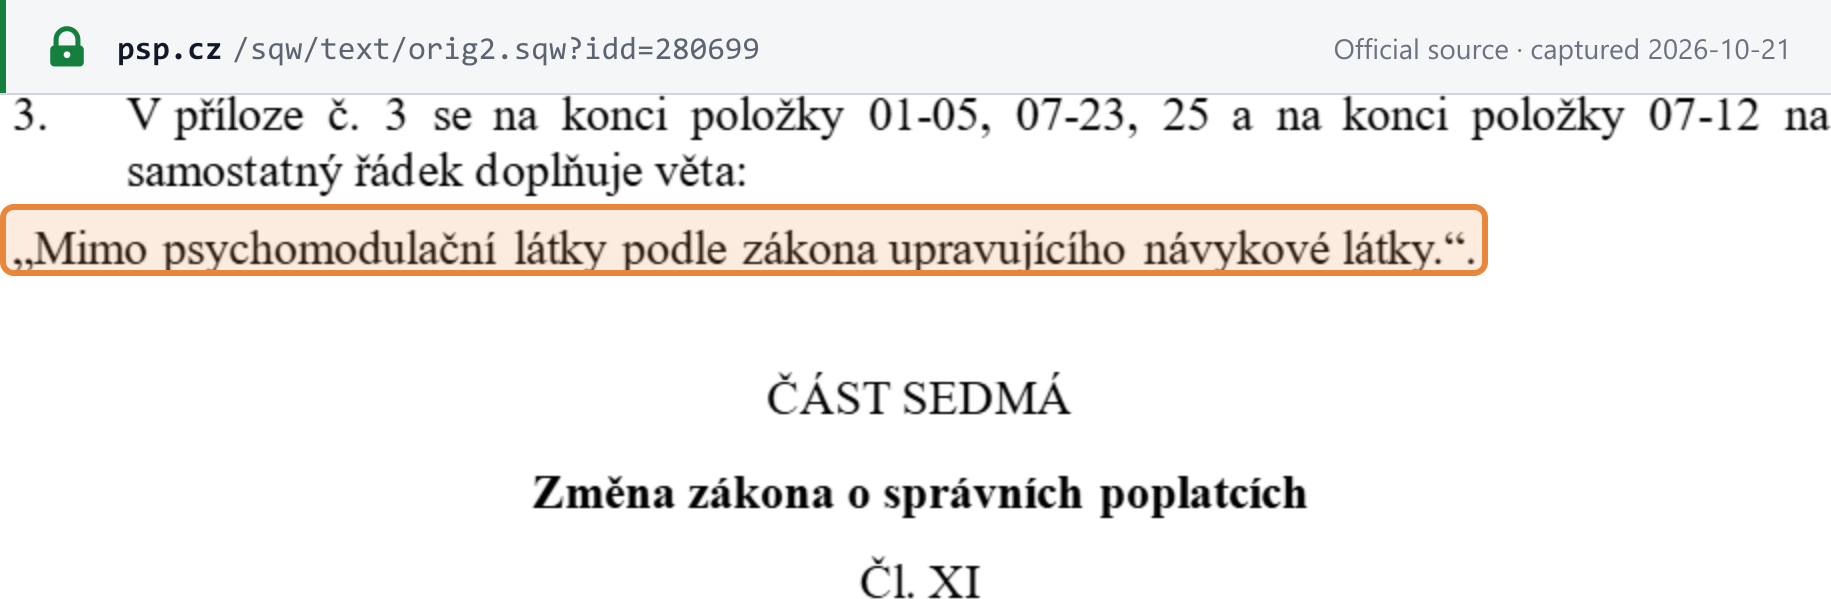 Source snapshot of the official page. Open full size ↗