Denmark proposes narrowing VAT exemptions for supplies in direct competition with taxable businesses from 1 January 2027 (draft)
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Denmark as they stand today, see the Denmark guide →
- Jurisdiction
- Denmark
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- Watch
- Announced
- 28 August 2026
- Effective
- 1 January 2027
- Authority
- Skatte- og Vækstministeriet (Danish Ministry of Taxation and Growth)
- Systems
- Tax engine, Invoicing
- Verified
- Fetched from official source · high confidence
Danish bodies supplying goods and services closely connected with VAT-exempt activities, and dealers who buy works of art with VAT for resale.
Exempt-sector suppliers (education, culture, sport, healthcare): review ancillary supplies that compete with taxable businesses.
Tax engineInvoicing
The same Danish consultation draft would narrow several VAT exemptions: goods and services supplied in close connection with an exempt activity would no longer be exempt where the supply is in direct competition with VAT-liable businesses. The draft also extends the second-hand goods margin scheme to works of art purchased with VAT. The bill is proposed to enter into force on 1 January 2027.
What changed in detail
This is a consultation draft, not law. The same Danish draft bill, published for consultation on 28 August 2026, would narrow several VAT exemptions.
Goods and services supplied in close connection with an exempt activity would no longer be exempt where the supply is in direct competition with VAT-liable businesses.
The draft would also extend the second-hand goods margin scheme to works of art purchased with VAT.
The bill is proposed to enter into force on 1 January 2027.
What it means
The draft does not name the affected supplies in the summary-level text, so exempt bodies cannot yet tell which of their ancillary activities would lose the exemption. The test is competition with taxable businesses, which is a fact-specific question.
Because this is a proposal, the practical step is to monitor the tabled bill rather than change pricing. Art dealers should note the margin-scheme extension separately, as it is a different measure in the same draft.
Proof
Ændringen indskrænker anvendelsesområdet for de berørte momsfritagelser, så varer og ydelser, der leveres i nær tilknytning til det momsfritagne område, ikke er omfattet af momsfritagelsen, hvis leveringen er i direkte konkurrence med momspligtige virksomheder.The change narrows the scope of the affected VAT exemptions, so that goods and services supplied in close connection with the VAT-exempt area are not covered by the VAT exemption if the supply is in direct competition with VAT-liable businesses.
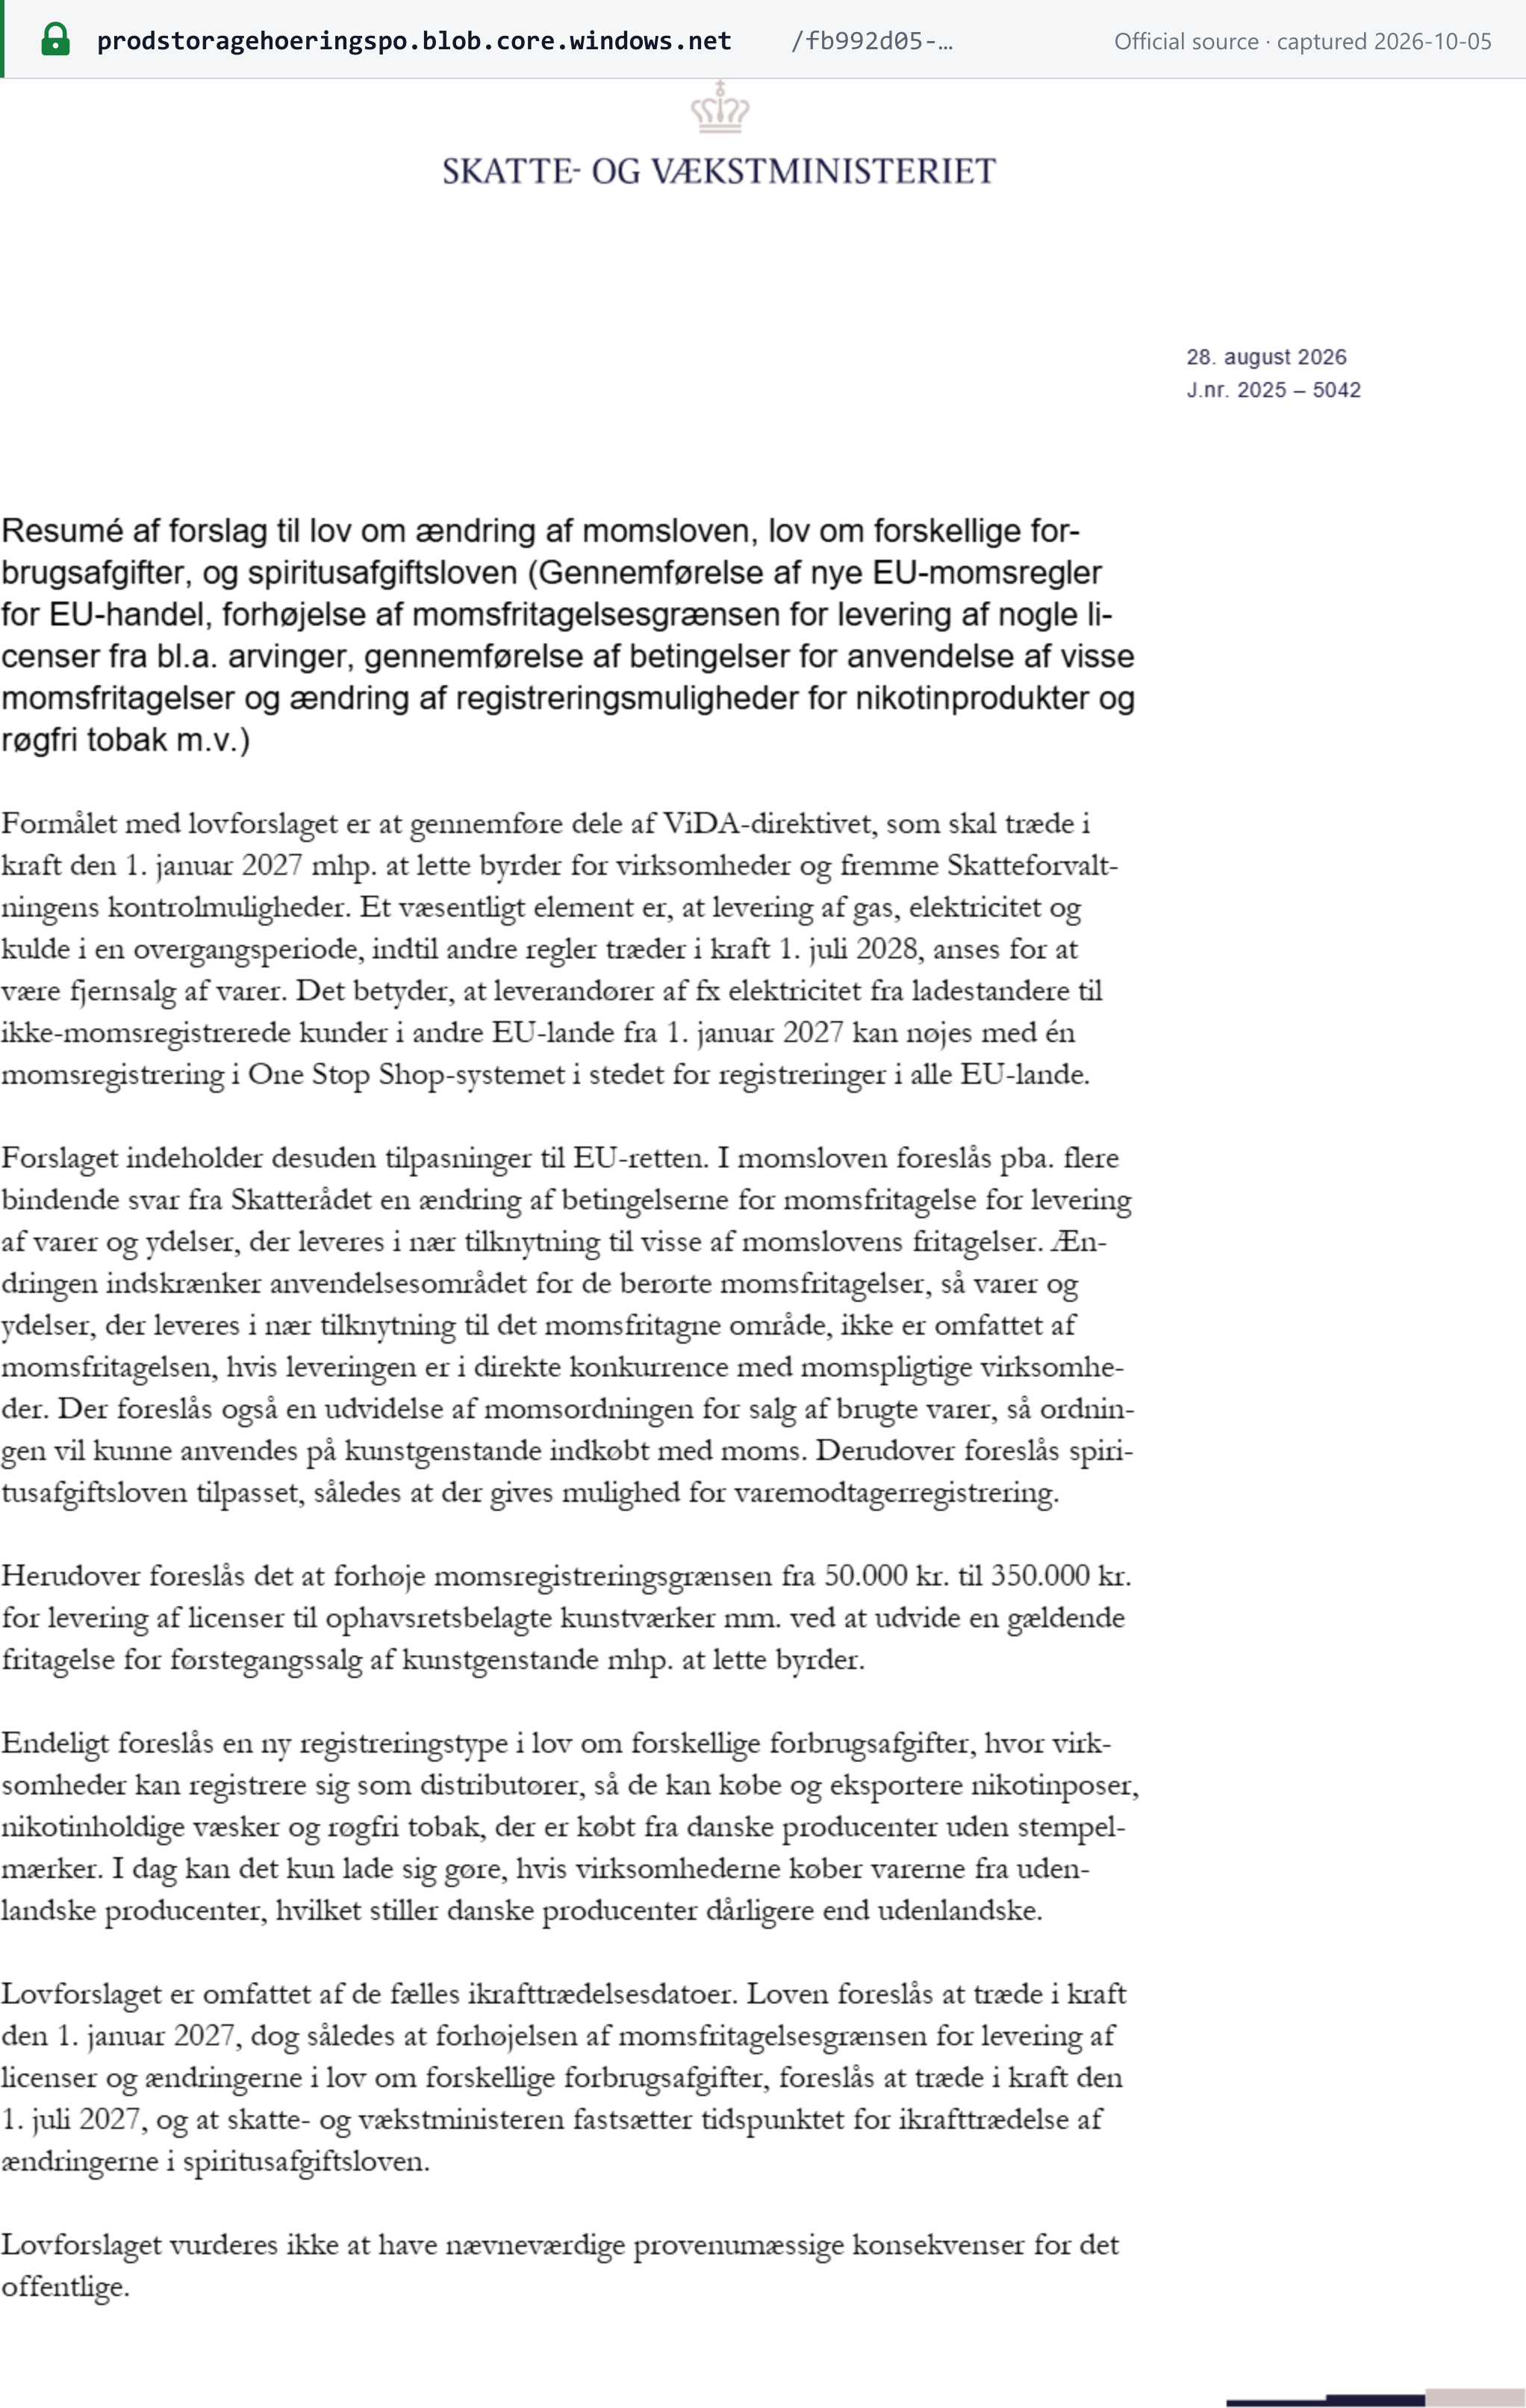 Source snapshot of the official page. Open full size ↗