Ecuador makes e-invoicing software providers register a dedicated RUC activity, and issuers name their provider on every voucher
- Jurisdiction
- Ecuador
- Tax
- VAT (IVA)
- Change type
- Registration
- Status
- In force
- Impact
- Action required
- Announced
- 28 July 2026
- Effective
- 27 August 2026
- Authority
- Servicio de Rentas Internas (SRI), Ecuador
- Systems
- Invoicing, Tax engine
- Verified
- Corroborated against official id · medium confidence
Developers and licence owners of electronic-invoicing software domiciled or permanently established in Ecuador, and every Ecuadorian taxpayer that issues electronic vouchers through a third party's system.
E-invoicing software developers/resellers domiciled in Ecuador: register the new CIIU activity code (J62021002 or J62021003) in your RUC by 27 August 2026. Businesses using a third-party e-invoicing provider: add the provider's RUC number to the additional-information field of every electronic voucher by 26 September 2026.
InvoicingTax engine
SRI Resolution NAC-DGERCGC26-00000027 (signed 27 July 2026 by the Director General, published in the Fifth Supplement of Registro Oficial No. 335 of 28 July 2026) creates a mandatory RUC registration category for providers of electronic-invoicing software/systems domiciled or permanently established in Ecuador: developers/owners of e-invoicing source code (CIIU J62021002) and resellers of third-party-developed e-invoicing systems (CIIU J62021003) must register or update this economic activity in their RUC within 30 days of publication (deadline 27 August 2026). Separately, taxpayers that issue electronic vouchers via a third-party system must add the provider's 13-digit RUC number in the additional-information field of every electronic voucher, within 60 calendar days of publication (deadline 26 September 2026). SRI will publish the resulting provider list on its website starting October 2026.
What changed in detail
Resolución NAC-DGERCGC26-00000027, signed on 27 July 2026 by the Director General of the Servicio de Rentas Internas and published in the Quinto Suplemento del Registro Oficial N° 335 of 28 July 2026, sets the rules for registering providers of electronic-invoicing software and services.
Article 2 treats as providers the taxpayers domiciled in Ecuador, or with a permanent establishment there, who are either developers and owners of the source code of systems for issuing, signing, transmitting and storing electronic vouchers with a view to commercialisation, or owners of the licences and source code of e-invoicing systems developed by third parties.
Article 3 obliges them to register in the RUC an exclusive establishment carrying one of two economic activities: CIIU J62021002 for the planning, design and development of such systems, or CIIU J62021003 for the commercialisation of systems developed by third parties.
Article 4 requires the SRI to publish the list of registered providers on its institutional web portal, updated within the first 10 business days of each month with a cut-off at the end of the previous month. Article 5 requires issuers of electronic vouchers to include, in the additional-information section, the RUC number of the provider of the software or e-invoicing service, as set out in the Ficha Técnica de Comprobantes Electrónicos.
The transitional provisions allow 30 days from publication to register or update the RUC, set October 2026 as the start of publication of the provider list, and allow 60 calendar days to implement the article 5 requirement. The resolution entered into force on publication.
What it means
Both deadlines run from publication on 28 July 2026: the RUC registration fell due at the end of August, and the article 5 voucher field at the end of September. Neither is a planning item any more — they are remediation items.
Article 5 is the one with reach. It does not land on software vendors; it lands on every taxpayer issuing electronic vouchers through someone else’s system, and it is a change to what each voucher carries rather than to a registration form. If your provider has not shipped the additional-information field, there is nothing you can fill in to comply.
The monthly provider list is the enforcement handle worth watching. Once the SRI publishes it, a provider whose RUC is not on it is visibly unregistered — which makes the list a supplier-diligence document as much as a transparency one.
Proof
5.- Requisito adicional en comprobantes electrónicos.- Los sujetos pasivos emisores de comprobantes electrónicos deberán incluir, en la sección de información adicional, el número de RUC del proveedor del sistema informático o servicios de facturación electrónica, conforme lo señalado en la Ficha Técnica de Comprobantes Electrónicos.5.- Additional requirement on electronic vouchers.- Taxpayers issuing electronic vouchers must include, in the additional information section, the RUC number of the provider of the software system or electronic invoicing services, in accordance with the Technical Specification for Electronic Vouchers.
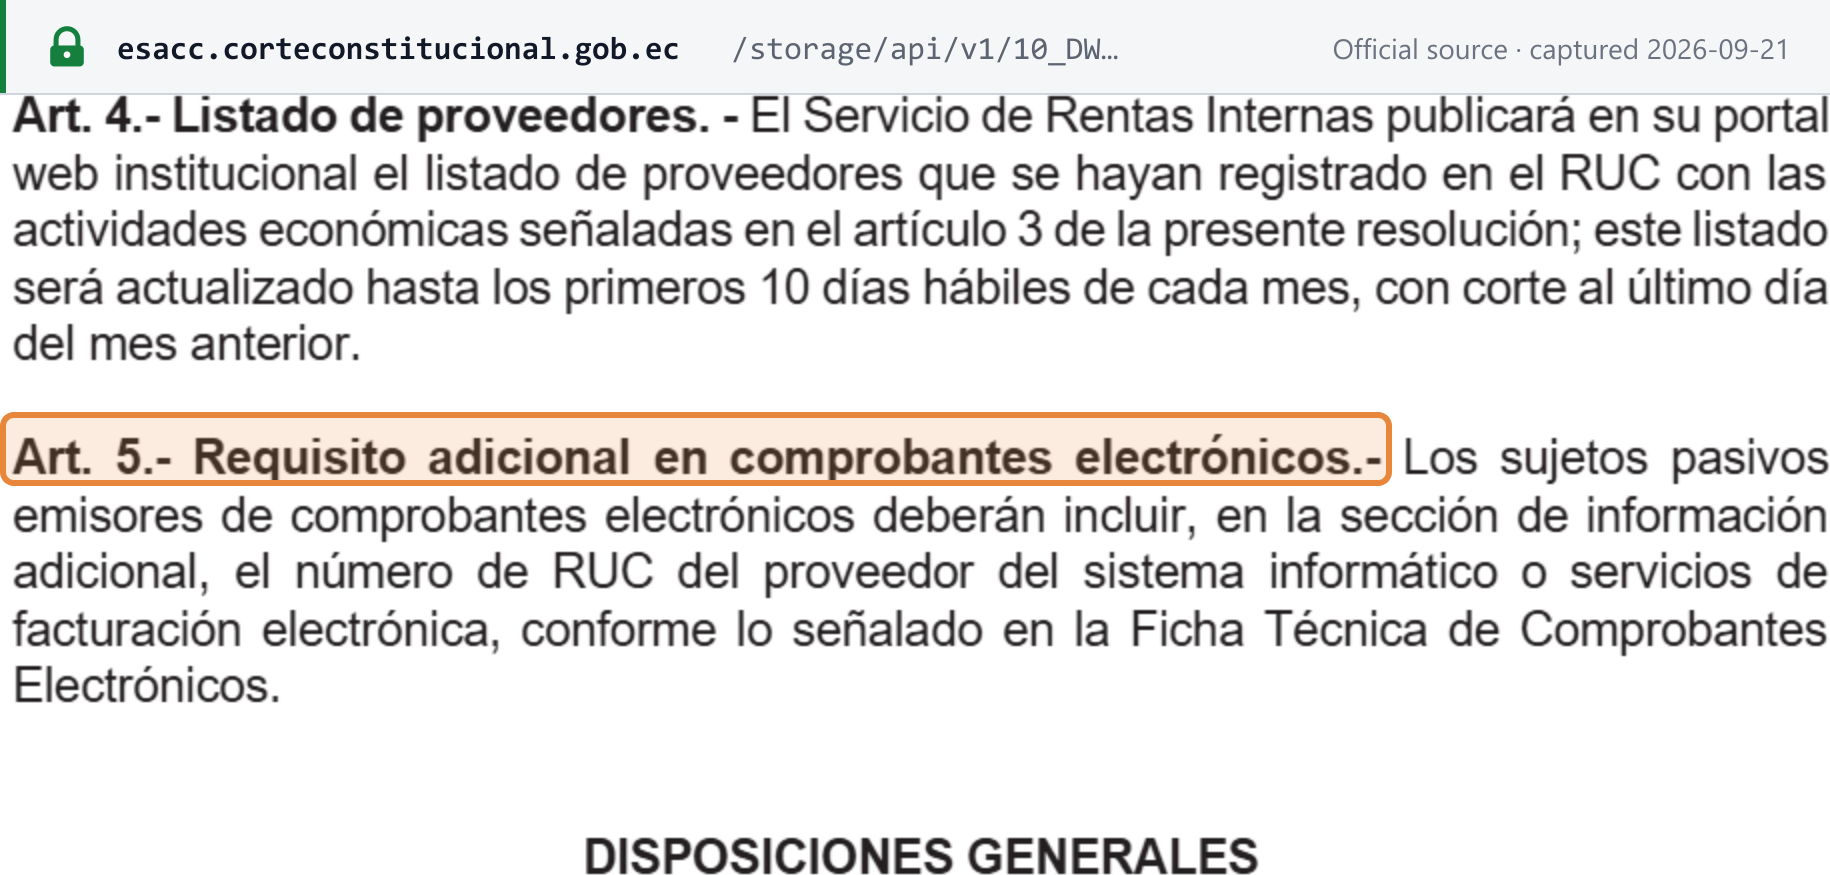 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Registro Oficial, Quinto Suplemento, Año II – N° 335, Quito, martes 28 de julio de 2026, 35 páginas — Resolución SRI NAC-DGERCGC26-00000027, art. 5 (p. 5) · esacc.corteconstitucional.gob.ec
DISPOSICIONES TRANSITORIAS Primera.- Los sujetos pasivos que deban registrar las actividades señaladas en esta resolución, deberán inscribirse o actualizar su RUC, en el plazo de 30 días, contados a partir de la publicación de la presente resolución en el Registro Oficial. Segunda.- El Servicio de Rentas Internas publicará el listado señalado en el artículo 4 de la presente resolución, a partir del mes de octubre de 2026. Tercera.- Los sujetos pasivos emisores de comprobantes electrónicos deberán implementar el requisito establecido en el artículo 5 la presente resolución en el plazo de 60 días calendario, contados a partir de su publicación en el Registro Oficial.First.- Taxpayers required to register the activities set out in this resolution must register or update their RUC within 30 days, counted from the publication of this resolution in the Registro Oficial. Second.- The Servicio de Rentas Internas will publish the list referred to in article 4 of this resolution from October 2026. Third.- Taxpayers issuing electronic vouchers must implement the requirement established in article 5 of this resolution within 60 calendar days, counted from its publication in the Registro Oficial.
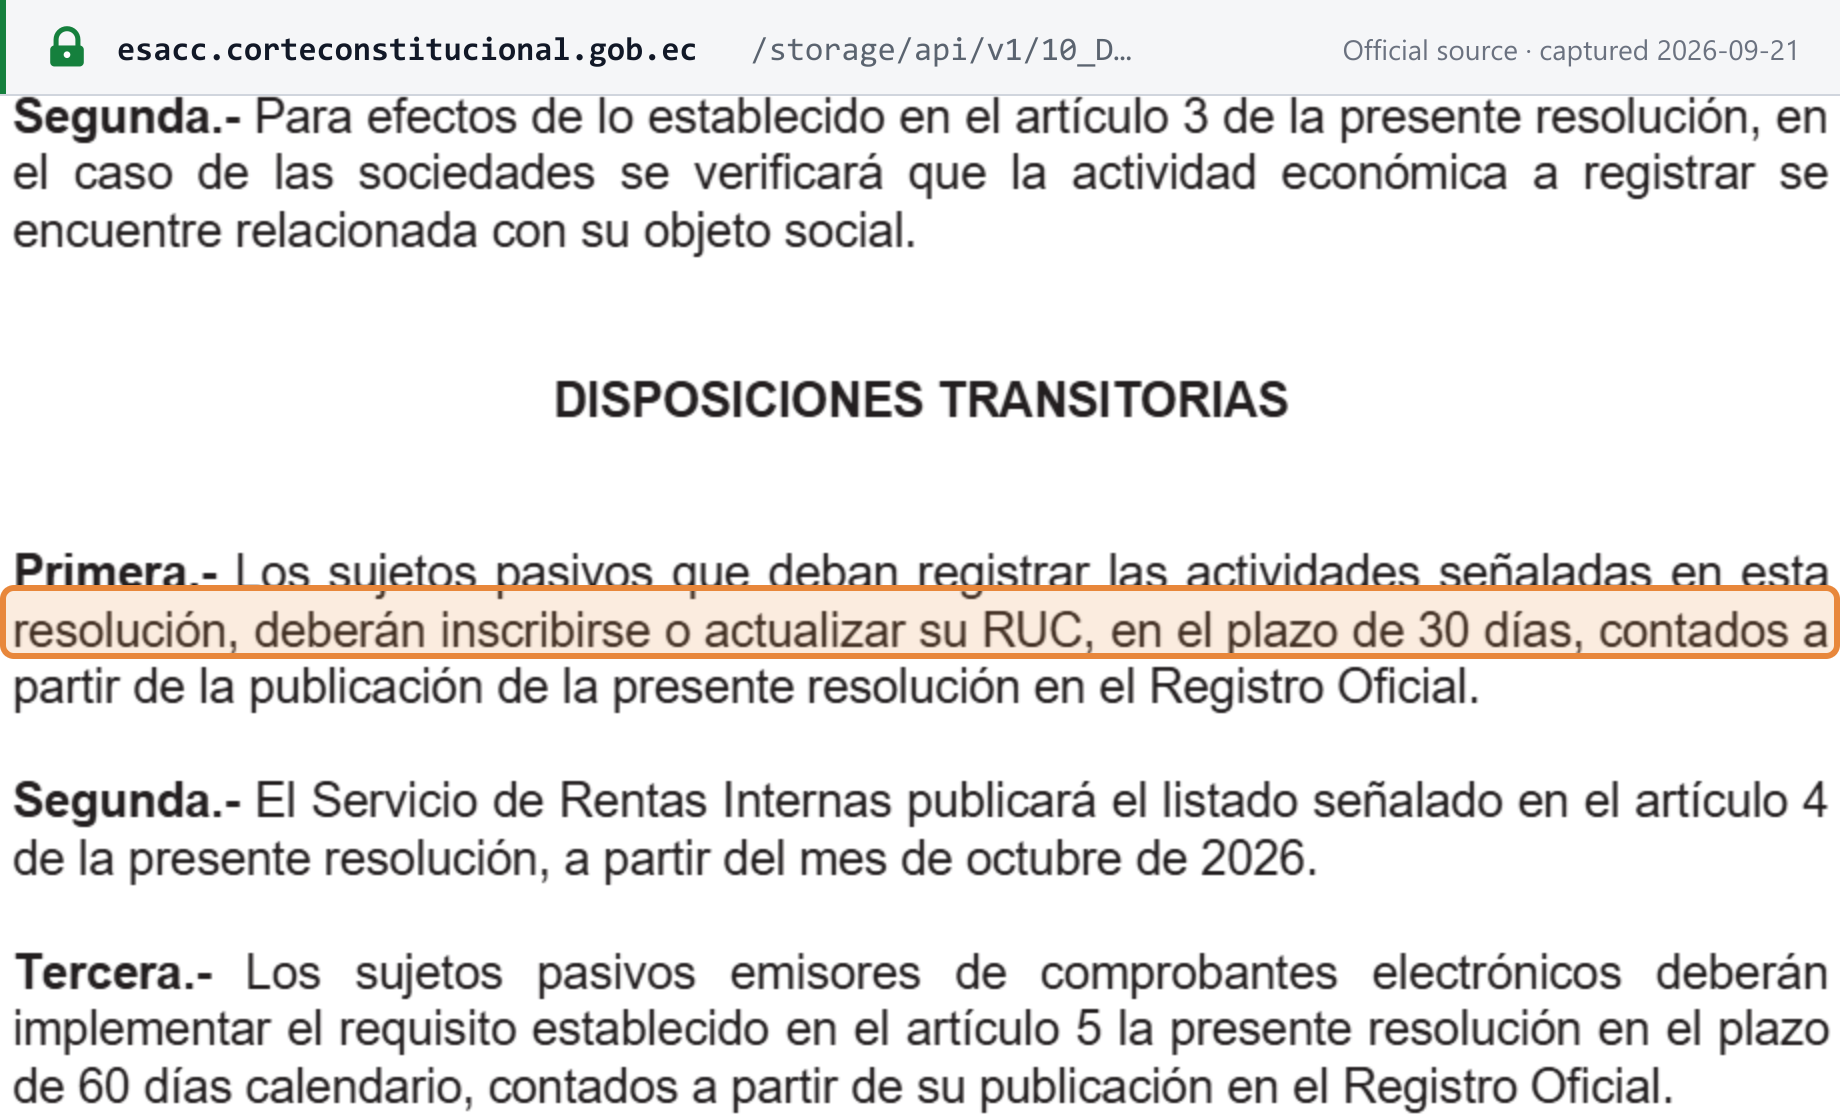 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Registro Oficial, Quinto Suplemento, Año II – N° 335, 28 July 2026 — Resolución SRI NAC-DGERCGC26-00000027, Disposiciones Transitorias Primera to Tercera (p. 6) · esacc.corteconstitucional.gob.ec