Egypt rewrites six items of the VAT-exempt list and repeals two serials of the schedule table
- Jurisdiction
- Egypt
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- Plan ahead
- Announced
- 28 July 2026
- Effective
- 29 July 2026
- Authority
- Egyptian Tax Authority (ETA)
- Systems
- Tax engine, Invoicing, ERP
- Verified
- Fetched from official source · high confidence
Suppliers of butane gas, quarried and mined raw materials, land and buildings, assistive and dialysis medical devices, postal savings services, and non-bank financial services supervised by the FRA or the Central Bank.
Confirm invoicing/tax-engine configuration correctly exempts the re-worded schedule items (assistive/prosthetic and dialysis medical devices, postal savings-fund and FRA-supervised non-bank financial services, qualifying real-estate sale/lease, butane gas, raw mined materials) per Law 149/2026, and check whether goods previously listed at repealed schedule items 8 and 10 have lost their prior treatment.
Tax engineInvoicingERP
Law No. 149 of 2026 amending the VAT Law issued by Law No. 67 of 2016 (Official Gazette Issue No. 30 bis (a), 28 July 2026; effective the day after publication, i.e. 29 July 2026) replaced the wording of items 19, 20, 28, 32, 35 and 36 of the schedule of VAT-exempt goods and services, and repealed items 8 and 10 of the same schedule. As replaced: item 19 covers butane gas (LPG cylinders); item 20 covers natural raw materials from mines and quarries in their natural state (excluding crude oil and natural gas); item 28 covers sale/lease of vacant land, agricultural land, and residential and non-residential buildings/units (with an exception for units run as an independent commercial management concern); item 32 covers wheelchairs and parts, artificial body organs, hearing aids for the deaf, other devices worn/carried/implanted to compensate for a disability and their inputs, kidney dialysis machines and consumables including artificial kidney filters, infant incubators, sera, vaccines, blood and its derivatives, blood-collection bags, and family-planning materials; item 35 covers postal savings-fund financial services; item 36 covers non-banking financial services supervised by the Financial Regulatory Authority.
What changed in detail
Law No. 149 of 2026, amending the VAT Law issued by Law No. 67 of 2016, was published in Egypt’s Official Gazette, issue No. 30 bis (a), on 28 July 2026. Article Five provides that it applies from the day following publication — 29 July 2026.
Article Two replaces the text of items 19, 20, 28, 32, 35 and 36 of the list of goods and services exempt from VAT annexed to the VAT Law. As replaced:
- 19 — butane gas (butagas).
- 20 — natural materials, including the products of mines and quarries in their natural state, excluding crude oil and natural gas.
- 28 — sale and lease of vacant land, agricultural land and residential buildings and units, and sale and lease of non-residential buildings and units, except the lease of buildings and units taken as an independent seat for managing an activity. Seats of religious, charitable, social, educational and health activities are excepted from that carve-out.
- 32 — wheelchairs, artificial body organs, hearing aids for the deaf, other devices worn, carried or implanted to compensate a deficiency, disability or impairment and their production inputs, dialysis machines and consumables including artificial kidney filters, infant incubators, sera, vaccines, blood and its derivatives, blood-collection bags, and family-planning means.
- 35 — the banking services of the Post Office Savings Fund and the financial services provided by the National Postal Authority.
- 36 — non-banking financial services subject to the supervision and oversight of the Financial Regulatory Authority or the Central Bank.
Article Four separately repeals serials 8 and 10 of item “First” of the schedule of goods and services annexed to the VAT Law.
:::note Two readings corrected against the gazette text, 21 September 2026 The frozen entry says items 8 and 10 were repealed from “the same schedule” — the exempt list. Article Four repeals them from item “First” of the جدول السلع والخدمات, the schedule-tax table, a different annex from the قائمة (list) of exempt goods and services that Article Two amends. Both are visible in the exhibits above.
Two readings are also widened here against the Arabic: item 35 covers the National Postal Authority’s financial services as well as the Post Office Savings Fund’s banking services, and item 36 covers services supervised by the Central Bank as well as by the Financial Regulatory Authority, which is the only body the frozen entry names. :::
What it means
Most of the six items restate treatment that already existed; the work is in the two that changed shape. Item 28 turns on how a property is used rather than how it is classified — a unit taken as an independent seat for running an activity falls outside the exemption even in a residential building — so lease documentation and actual occupancy become the evidence that decides the treatment, not the title deed.
Item 36 now turns on which regulator supervises the service. A non-bank financial service is exempt if the Financial Regulatory Authority or the Central Bank oversees it, which is a different question from whether the provider holds a banking licence.
The repeal in Article Four is the part most likely to be missed, precisely because it lives in another annex. A tax engine configured against the exemption list alone will not see it.
Proof
يستبدل بنصوص البنود أرقـام ) ۱۹ ، ۲۰ ، ۲۸ ، ۳۲ ، ٣ ٥ ، ۳ ٦ ( مـن قائمـة السلع والخدما ت المعفاة من الضريبة على القيمة المضافة المرافقة لقـانون الـضريبة على القيمة المضافة المشار إليه ، النصوص الآ تية :The texts of items numbered (19, 20, 28, 32, 35, 36) of the list of goods and services exempt from value added tax annexed to the Value Added Tax Law referred to above shall be replaced by the following texts:
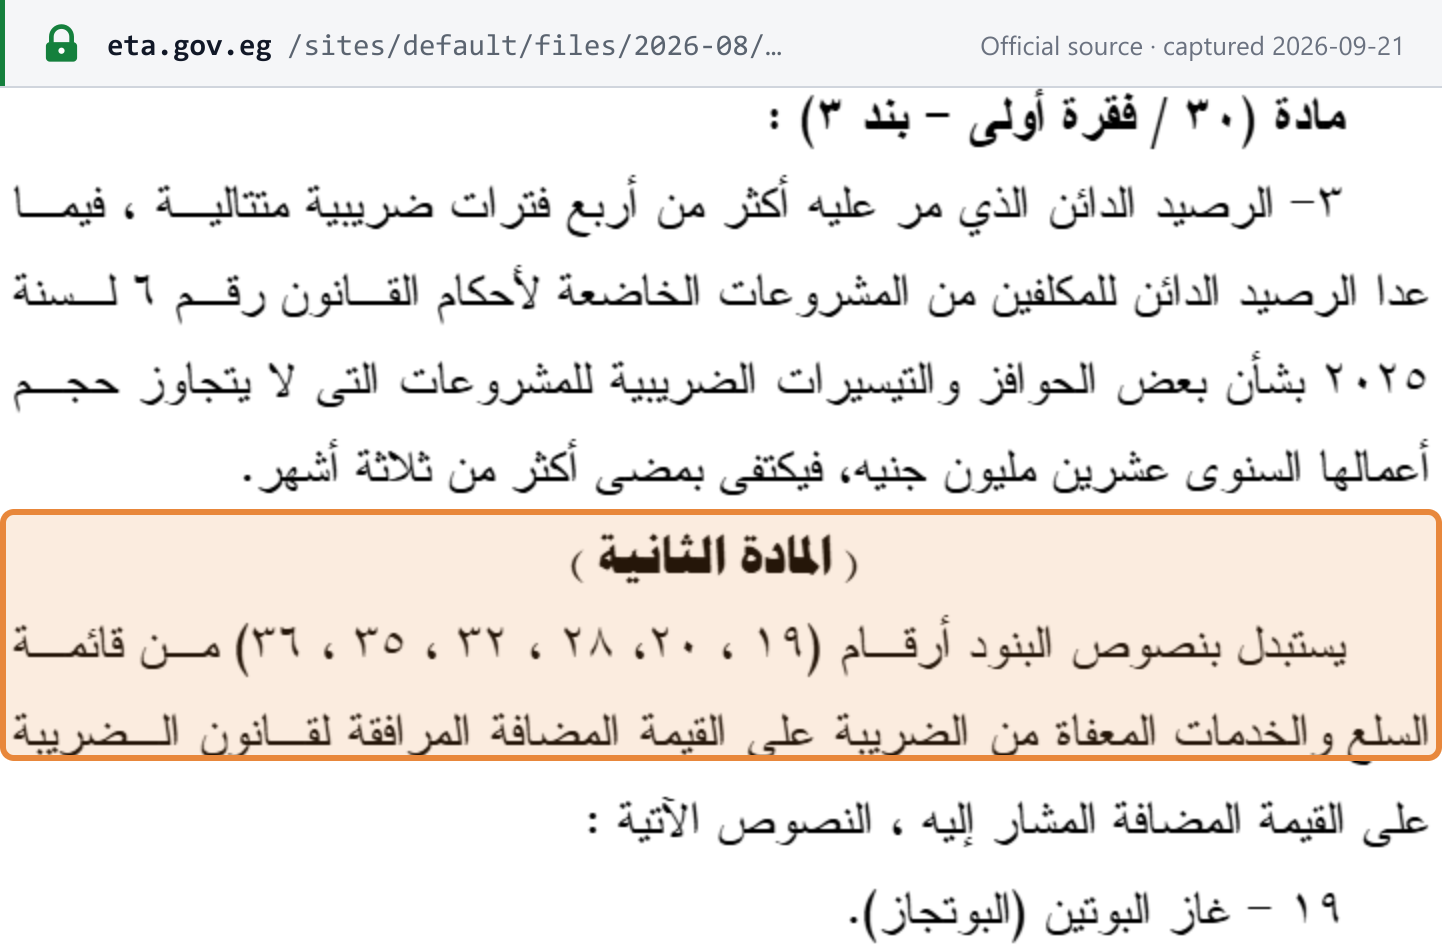 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Law No. 149 of 2026, Official Gazette issue No. 30 bis (a), 28 July 2026 — Article Two (PDF page 2) · eta.gov.eg
ي ل غ ى المسلسلان رقما ) ۸ ، ۱۰ ( من البند " أولا " من جـدول الـسلع والخـدمات المرافق ل قانون الضريبة على القيمة المضافة المشار إليه .Serials numbered (8, 10) of item "First" of the schedule of goods and services annexed to the Value Added Tax Law referred to above are repealed.
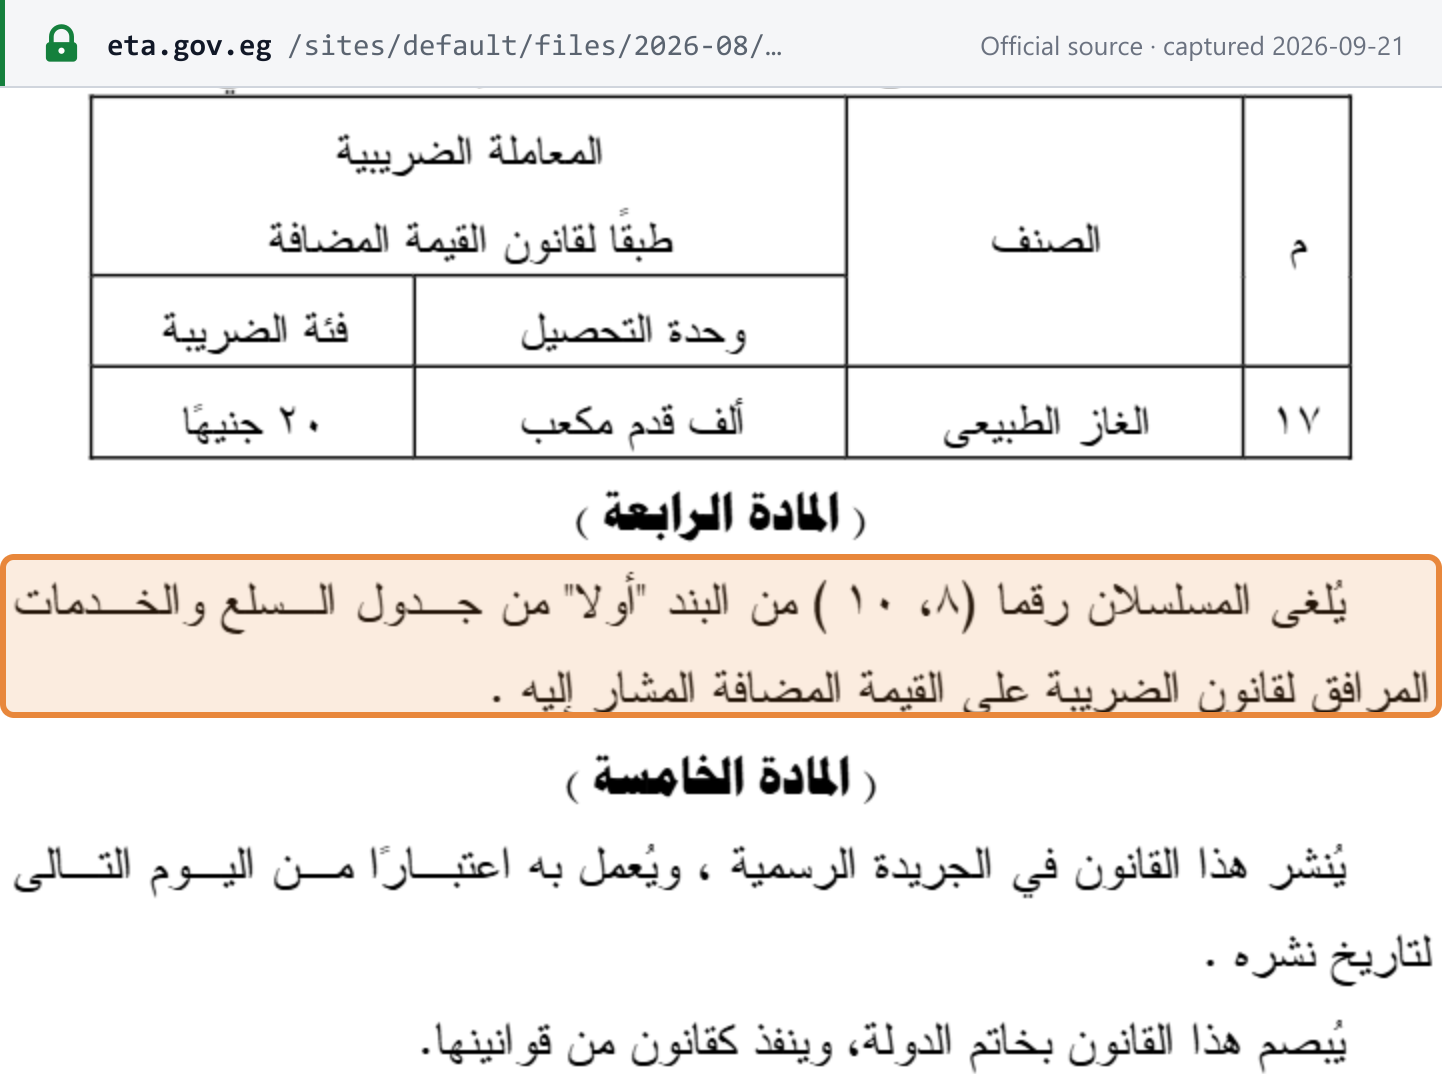 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Law No. 149 of 2026, Official Gazette issue No. 30 bis (a), 28 July 2026 — Article Four (PDF page 4) · eta.gov.eg