Finland enacts Law 597/2026 implementing ViDA single-VAT-registration rules from 1 January 2027
This page records one dated change. For the rules in Finland as they stand today, see the Finland guide →
- Jurisdiction
- Finland
- Tax
- VAT
- Change type
- Registration
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 30 June 2026
- Effective
- 1 January 2027
- Authority
- Finlex (Finnish Ministry of Justice statute database, run by Oikeusrekisterikeskus)
- Systems
- Tax engine, E-commerce, Reporting
- Verified
- Fetched from official source · high confidence
Businesses using the EU One Stop Shop, call-off stock arrangements, and marketplaces, platforms and portals facilitating supplies of goods in Finland.
Update Finnish OSS, call-off-stock and marketplace deemed-supplier logic for supplies with tax point on or after 1 January 2027.
Tax engineE-commerceReporting
Finland's Law 597/2026 amending the VAT Act (Laki arvonlisäverolain muuttamisesta), given in Helsinki on 26 June 2026 on government proposal HE 78/2026 and implementing Council Directive (EU) 2025/516, enters into force on 1 January 2027. It implements the single-VAT-registration elements of ViDA: it amends the OSS special scheme provisions (including sections 133 k, 133 l, 133 o and 133 r, and new section 137 b; covering intra-Community distance sales, certain domestic supplies of goods and services by EU-established taxable persons), amends the call-off stock rules (section 18 c) so that they cover only goods moved by 30 June 2028, and amends the existing deemed-supplier rule (section 19 b) under which a business facilitating supplies of goods through a marketplace, platform, portal or similar electronic interface is treated as having bought and resold the goods (section 19 b). It applies where the tax liability arises on or after 1 January 2027.
What changed in detail
Finland’s Law 597/2026 amending the VAT Act (Laki arvonlisäverolain muuttamisesta) was given in Helsinki on 26 June 2026 on government proposal HE 78/2026 and published in the Statute Book (Säädöskokoelma) on 30 June 2026. It implements Council Directive (EU) 2025/516 and enters into force on 1 January 2027.
It implements the single-VAT-registration elements of ViDA. It amends the OSS special scheme provisions (sections 133 k, 133 l, 133 o and 133 r), covering intra-Community distance sales and certain domestic supplies of goods and services by EU-established taxable persons, adds a new section 137 b, and rewrites the call-off stock provisions.
It adds a deemed-supplier rule under which a business facilitating supplies of goods through a marketplace, platform, portal or similar electronic interface is treated as having bought and resold the goods (section 19 b).
It applies where the tax liability arises on or after 1 January 2027.
What it means
The test is when the tax liability arises, not when the contract or invoice is dated, so supplies straddling year-end need to be dated carefully.
The deemed-supplier rule matters most for platforms: it moves VAT responsibility for the covered goods onto the facilitator. Platform operators and the sellers who use them should check whether the supplies fall within the listed categories.
Proof
Jos elinkeinonharjoittaja mahdollistaa markkinapaikkaa, alustaa, portaalia tai vastaavaa sähköistä rajapintaa käyttämällä toisen elinkeinonharjoittajan suorittaman tavaroiden myynnin, hänen katsotaan myyneen tavarat ostajalle ja toisen elinkeinonharjoittajan myyneen ne hänelle, edellyttäen että kyseessä on:If a trader, by using a marketplace, platform, portal or similar electronic interface, enables the sale of goods carried out by another trader, he is deemed to have sold the goods to the buyer and the other trader to have sold them to him, provided that it concerns:
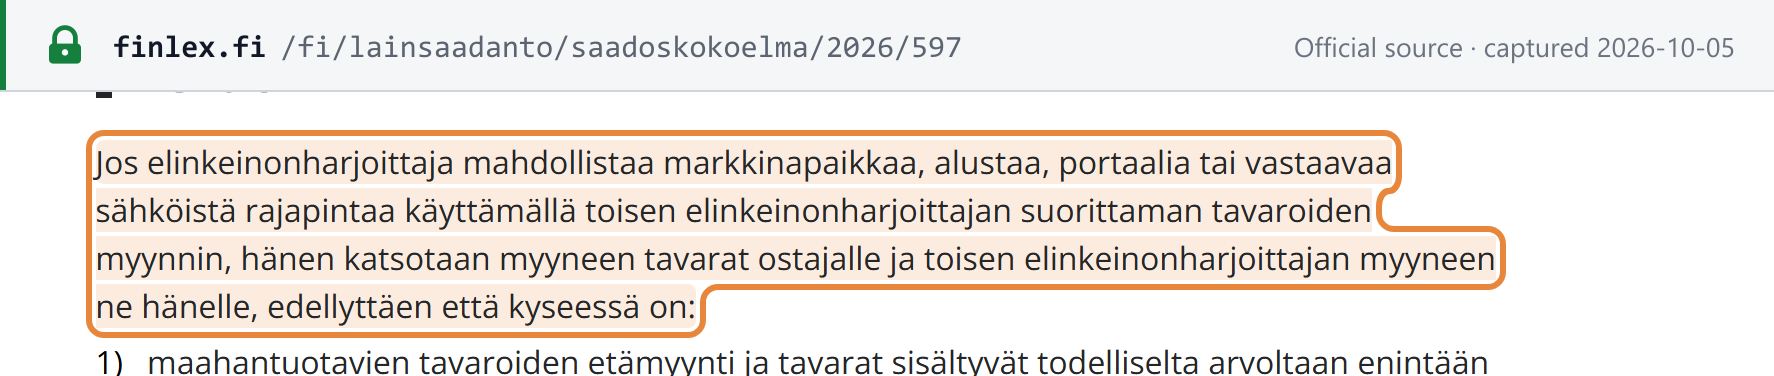 Source snapshot of the official page. Open full size ↗
Sources
- Laki arvonlisäverolain muuttamisesta 597/2026
- HE 78/2026 Hallituksen esitys eduskunnalle laeiksi arvonlisäverolain ja Ahvenanmaan maakuntaa koskevista poikkeuksista arvonlisävero- ja valmisteverolainsäädäntöön annetun lain muuttamisesta
- Laki arvonlisäverolain muuttamisesta 597/2026
- HE 78/2026 vp - Hallituksen esitys arvonlisäverolain muuttamisesta