France clarifies what counts as a used good for the VAT margin scheme
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Update
- Status
- Enacted
- Impact
- Watch
- Announced
- 19 August 2026
- Authority
- Direction générale des Finances publiques (DGFiP) — BOFiP
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Taxable dealers (assujettis-revendeurs) in France applying the VAT margin scheme of CGI article 297 A to second-hand goods — vehicle traders, refurbished-electronics resellers, furniture and antiques dealers.
Businesses applying the VAT margin scheme to used goods should review classification of stock against the DGFiP's clarified definition (BOI-RES-TVA-000270).
Tax engine
DGFiP published a rescrit (BOI-RES-TVA-000270, ACTU-2026-00098) on 19 August 2026 clarifying the notion of 'biens d'occasion' (used goods) for the purposes of the VAT margin-scheme regime under article 297 A of the Code général des impôts.
What changed in detail
On 19 August 2026 the Direction générale des Finances publiques published ACTU-2026-00098 in the RES – TVA series of the Bulletin officiel des finances publiques. The actuality records the publication of a rescrit, BOI-RES-TVA-000270, giving clarifications on the notion of biens d’occasion — used goods — for the application of the profit-margin regime provided at article 297 A of the Code général des impôts, in the field of value added tax.
Article 297 A is the provision under which a taxable dealer accounts for VAT on the difference between the selling price and the buying price, rather than on the full consideration, for second-hand goods, works of art, collectors’ items and antiques. Whether the goods are biens d’occasion is the gateway condition for that treatment, and it is that condition the rescrit addresses.
The rescrit is filed under the sectoral-regimes heading, and the linked document is signed by Laurent Martel, directeur de la législation fiscale. The actuality itself sets out no related actuality and no transitional arrangement: it is a clarification of existing doctrine rather than a change to article 297 A.
What it means
A rescrit is DGFiP answering one taxpayer’s question and publishing the answer because it then binds the administration for anyone in the same position. That makes it narrower than a doctrine rewrite and more directly usable than one — if your facts match, you can rely on it.
The gateway matters more than the margin. Getting bien d’occasion wrong does not move a rate; it moves the basis of assessment from the margin to the whole selling price. On stock bought from private individuals, with no input VAT to recover, that is the difference between tax on a few points of margin and tax on the lot. Refurbished electronics, part-exchanged vehicles and reconditioned furniture are where the line usually blurs, so that is where the review is worth doing.
Proof
Des précisions sont apportées sur la notion de biens d’occasion pour l’application du régime de la marge bénéficiaire, prévu à l’article 297 A du code général des impôts, en matière de taxe sur la valeur ajoutée.Clarifications are given on the notion of second-hand goods for the application of the profit-margin regime, provided for at article 297 A of the General Tax Code, in matters of value added tax.
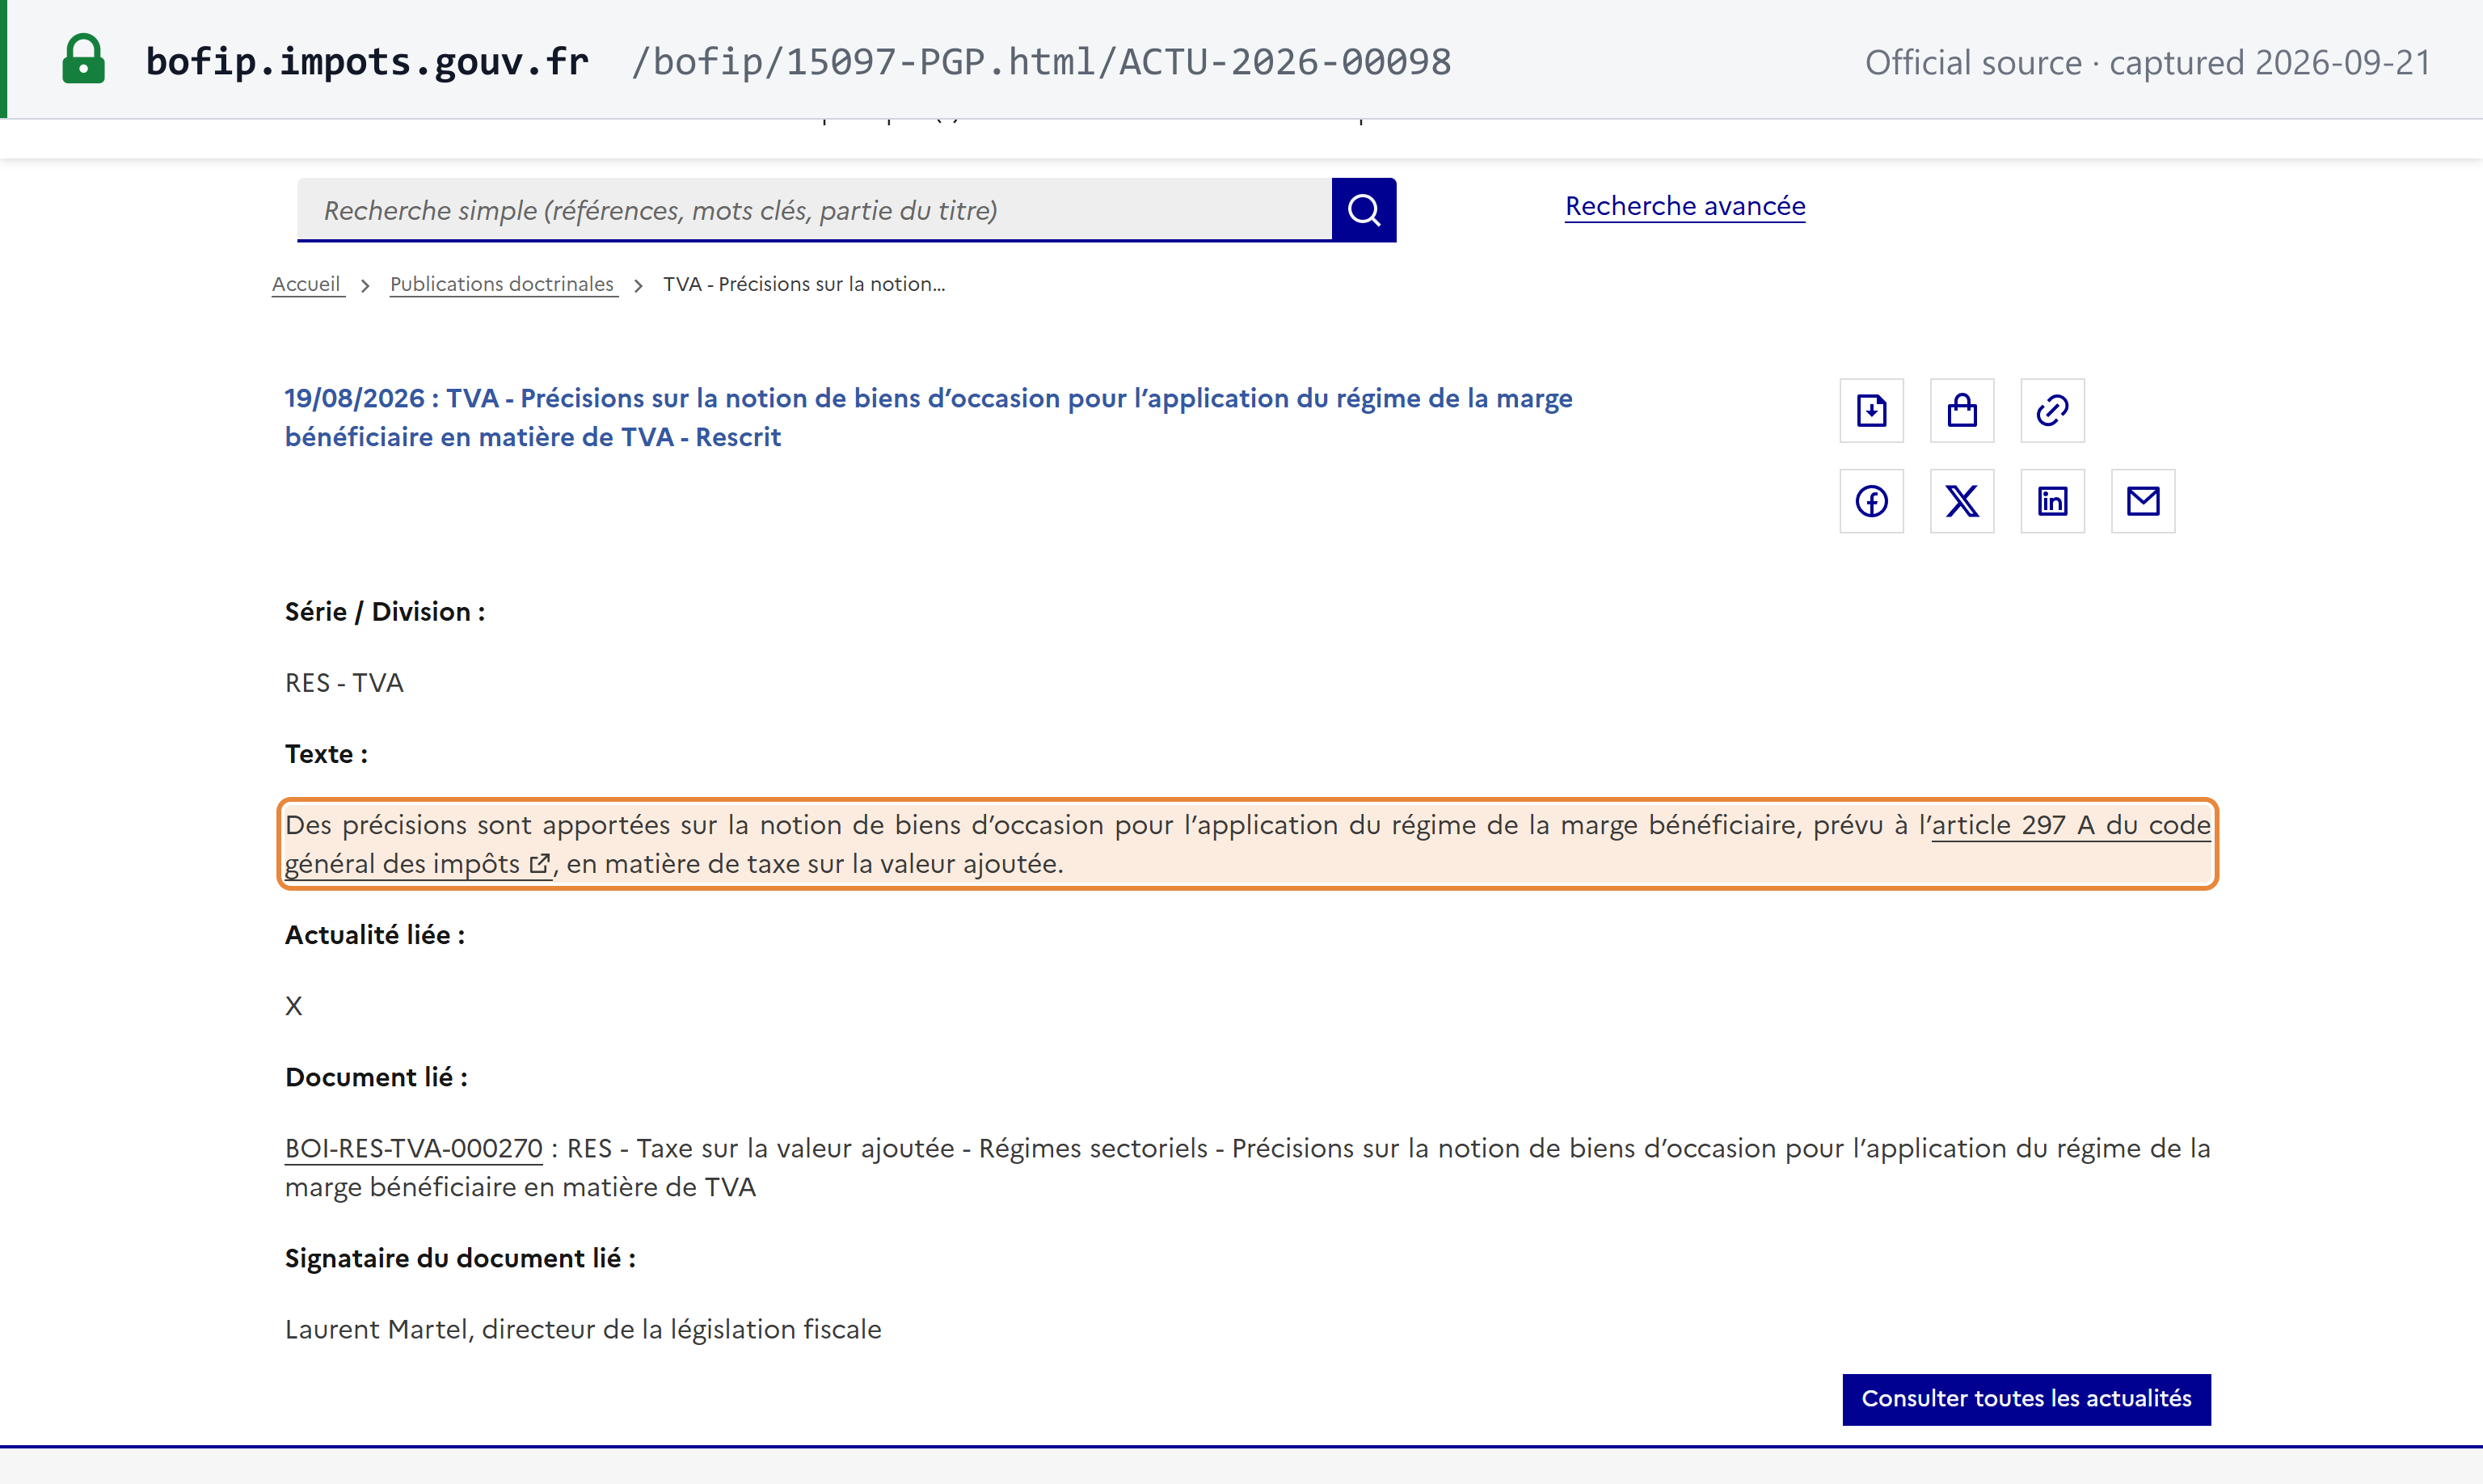 Source snapshot of the official page. Open full size ↗