Germany: Commission proposes, not yet adopted, to extend the BEHG emission-allowance reverse charge to 30 June 2030
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Germany as they stand today, see the Germany guide →
- Jurisdiction
- Germany
- Tax
- VAT
- Change type
- Compliance
- Status
- Proposed
- Impact
- Watch
- Announced
- 16 October 2026
- Authority
- European Commission — Taxation and Customs Union
- Systems
- Tax engine, Invoicing
- Verified
- Fetched from official source · high confidence
Businesses trading emission allowances under the German Fuel Emission Allowance Trading Act (BEHG).
No action — monitoring only.
Tax engineInvoicing
On 16 October 2026 the European Commission proposed (COM(2026) 556 final, 2026/0318 (NLE)) a Council Implementing Decision extending Germany's authorisation to apply the reverse charge, in derogation from Article 193 of Directive 2006/112/EC, to transfers of emission allowances traded under the national Fuel Emission Allowance Trading Act (BEHG). The current authorisation under Implementing Decision (EU) 2021/1778, as extended by (EU) 2024/2680, runs to 31 December 2026; the proposal would replace Article 2 so that it expires on 30 June 2030. It needs unanimous Council approval and takes effect on notification.
What changed in detail
This is a proposal, not an adopted decision. On 16 October 2026 the European Commission proposed (COM(2026) 556 final, 2026/0318 (NLE)) a Council Implementing Decision extending Germany’s authorisation to apply the reverse charge, in derogation from Article 193 of Directive 2006/112/EC, to transfers of emission allowances traded under the national Fuel Emission Allowance Trading Act (BEHG).
The current authorisation, under Implementing Decision (EU) 2021/1778 as extended by (EU) 2024/2680, runs to 31 December 2026. The proposal would replace Article 2 so that it expires on 30 June 2030. It needs unanimous Council approval and takes effect on notification.
What it means
Without a Council decision before the end of 2026, the reverse charge would lapse and allowance transfers would revert to the ordinary supplier-accounts-for-VAT rules. Traders should treat the extension as unconfirmed until the Council acts until the Council acts.
Proof
Article 2 of Implementing Decision (EU) 2021/1778 is replaced by the following: ‘Article 2 This Decision shall expire on 30 June 2030.’.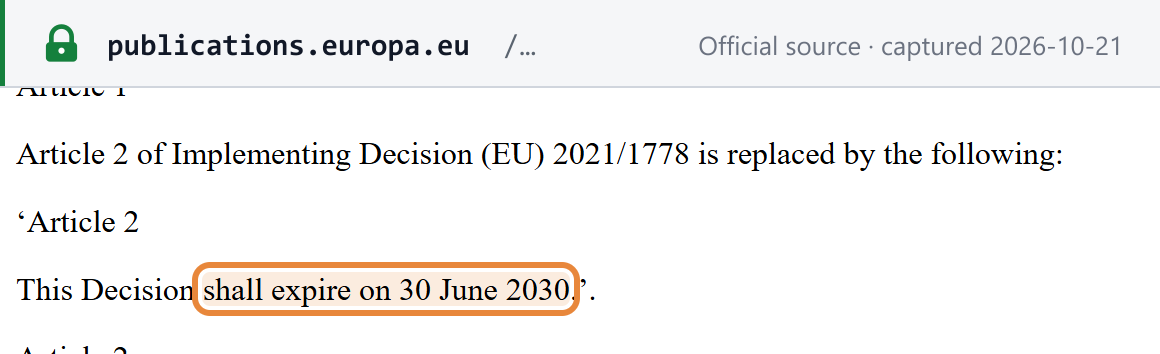 Source snapshot of the official page. Open full size ↗