Germany recasts UStG section 22a(2) on who may act as a VAT fiscal representative from 1 September 2026
This page records one dated change. For the rules in Germany as they stand today, see the Germany guide →
- Jurisdiction
- Germany
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 29 June 2026
- Effective
- 1 September 2026
- Authority
- Bundesministerium der Justiz (gesetze-im-internet.de)
- Systems
- Reporting
- Verified
- Fetched from official source · medium confidence
Non-resident businesses appointing a German VAT fiscal representative, and tax advisers, forwarders and customs representatives who act as one.
No action — monitoring only (affects only VAT fiscal-representation providers and the non-established exempt-supply traders who use them).
Reporting
Article 5 of the Ninth Act amending provisions of tax-advisory law and tax law (9. StBerRÄndG, BGBl. 2026 I Nr. 197, of 29 June 2026) replaced section 22a(2) of the Umsatzsteuergesetz with effect from 1 September 2026: persons and companies within section 3 sentence 1 of the Steuerberatungsgesetz, and forwarders and other customs representatives authorised under section 4d of that Act, may act as fiscal representatives; a fiscal representative under point 2 must be resident within the territory of the Steuerberatungsgesetz and may not use the small-business scheme under section 19. Section 22e(1) (prohibition of fiscal representation) was conformed to refer to fiscal representation by the persons in section 22a(2) sentence 1 point 2.
What changed in detail
Article 5 of the Ninth Act amending provisions of tax-advisory law and tax law (9. StBerRÄndG, BGBl. 2026 I Nr. 197, of 29 June 2026) replaced section 22a(2) of the Umsatzsteuergesetz with effect from 1 September 2026.
Persons and companies within section 3 sentence 1 of the Steuerberatungsgesetz, and forwarders and other customs representatives authorised under section 4d of that Act, may act as fiscal representatives. A fiscal representative under point 2 must be resident within the territory of the Steuerberatungsgesetz and may not use the small-business scheme under section 19.
The explanatory memorandum (Bundestag Drucksache 21/6002) says section 22a(2) is recast because of the changes to the Steuerberatungsgesetz, which moved the old section 4 no. 9 to section 4d, and that no change of substance is intended.
Section 22e(1), the prohibition of fiscal representation, was conformed to refer to fiscal representation by the persons named in section 22a(2) sentence 1 point 2.
What it means
The change is a recast of who may be appointed, not a change to when fiscal representation is required, and the legislature does not intend it to change the substance. Non-resident businesses with an existing German fiscal representative may still want to check that the appointee’s references match section 22a(2) as rewritten.
The residence and small-business conditions apply to the point 2 group specifically. A representative that is a small business under section 19 cannot fill the role.
Proof
Der Fiskalvertreter nach Satz 1 Nummer 2 muss im Geltungsbereich des Steuerberatungsgesetzes ansässig sein und darf die Regelung für Kleinunternehmer nach § 19 nicht in Anspruch nehmen.The fiscal representative under sentence 1 number 2 must be resident within the territory of the Steuerberatungsgesetz and may not make use of the small-business scheme under section 19.
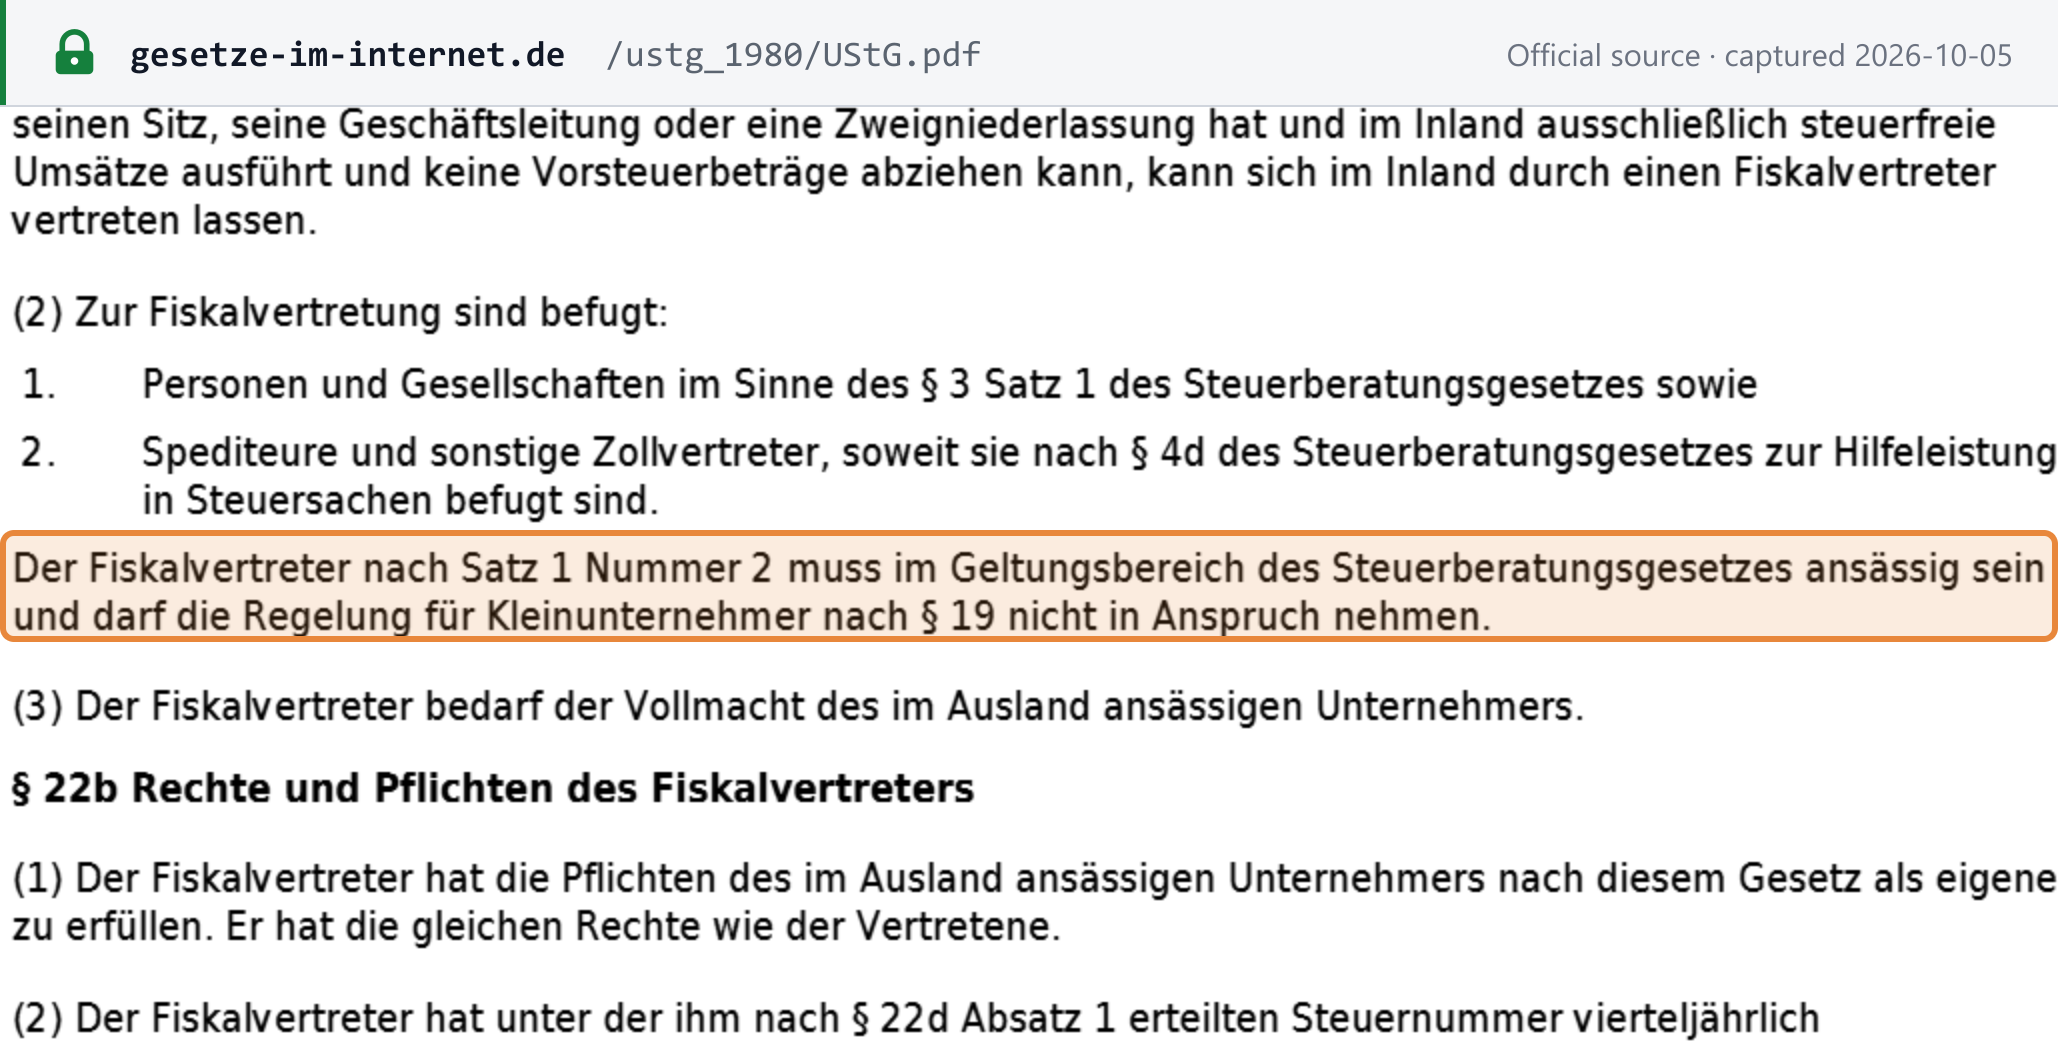 Source snapshot of the official page. Open full size ↗