Not yet law: Iceland's 2027 budget bill would move bathing lagoons off the reduced VAT rate
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Iceland as they stand today, see the Iceland guide →
- Jurisdiction
- Iceland
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 1 September 2026
- Authority
- Fjármála- og efnahagsráðuneytið (Ministry of Finance and Economic Affairs)
- Verified
- Fetched from official source · high confidence
Operators of steam baths, bathing lagoons and related bathing activities in Iceland, currently taxed at the 11% reduced VAT rate — if the proposal is enacted.
No action — monitoring only.
Iceland's budget bill for 2027 (frumvarp til fjárlaga, presented to the Althingi in September 2026) proposes to end the reduced-rate treatment of steam baths, bathing lagoons and related activities, moving them from the 11% rate to the 24% standard rate, with an estimated revenue gain of ISK 4 billion. The budget bill does not itself amend the VAT Act or set a commencement date; that requires separate legislation.
What changed in detail
This is not yet law. Iceland’s budget bill for 2027 (frumvarp til fjárlaga), presented to the Althingi in September 2026, proposes to end the reduced-rate treatment of steam baths, bathing lagoons and related activities, moving them from the 11% reduced VAT rate to the 24% standard rate. The Ministry of Finance and Economic Affairs estimates the change would raise ISK 4 billion in revenue. The budget bill does not itself amend the VAT Act or set a commencement date — that requires separate legislation.
What it means
A budget bill states fiscal intent; it is not the mechanism that changes the VAT Act. Bathing lagoon and steam bath operators should watch for the separate VAT Act amendment this proposal would require, rather than treating the budget figure as a rate that is already in force. Until that amendment passes, the 11% rate continues to apply.
Proof
Annars vegar er fyrirhugað að hverfa frá því að starfsemi gufubaða og baðlóna sé skattlögð með ívilnandi hætti í neðra þrepi VSK.On the one hand, it is proposed to move away from taxing the operation of steam baths and bathing lagoons at a preferential rate in the reduced VAT bracket.
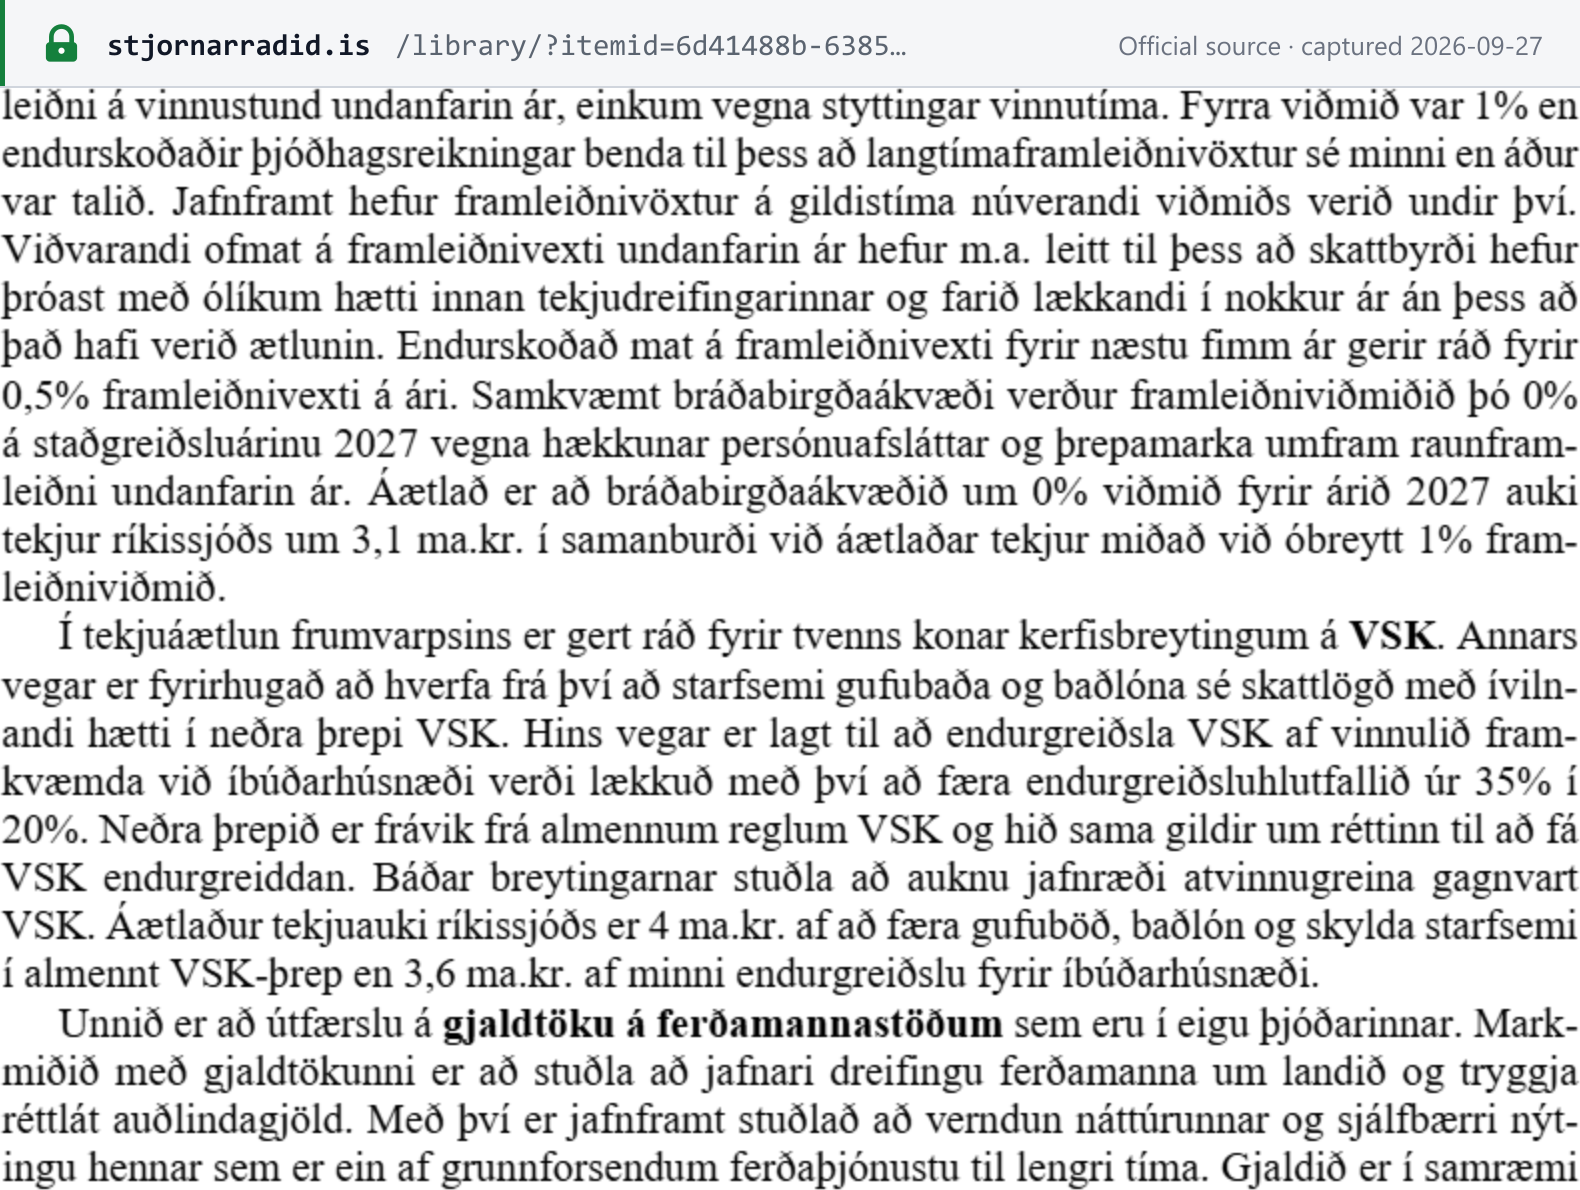 Source snapshot of the official page. Open full size ↗