Indonesia starts VAT collection on cross-border digital purchases through SPP-TDLN on 25 September 2026
- Jurisdiction
- Indonesia
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- Action required
- Effective
- 25 September 2026
- Authority
- Directorate General of Taxes (DJP), Indonesia
- Systems
- E-commerce, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Indonesian consumers buying foreign digital goods and services, appointed payment issuers (banks and non-bank payment institutions), and foreign providers not already collecting VAT.
Foreign digital sellers not registered as PMSE VAT collectors: expect Indonesian VAT (11/111 of price) to be withheld at the card/payment issuer from 25 September 2026; reconcile settlements and confirm PMSE-collector status with DJP.
E-commerceTax engineReporting
Minister of Finance Regulation (PMK) No. 49 of 2026, signed 14 July 2026, sets the procedure for collecting VAT on cross-border digital transactions through the VAT Collection System for Cross-Border Digital Transactions (SPP-TDLN). Appointed 'Pihak Lain' (issuers: banks and non-bank payment institutions) must collect VAT on qualifying purchases of foreign digital goods and services by Indonesian consumers when the SPP-TDLN operator confirms the transaction is subject to VAT, computed as 11/111 of the VAT-inclusive price (Article 7). It applies only to transactions on which VAT has not already been collected by a foreign seller appointed as a PMSE VAT collector under PMK 81/2024; it introduces no new tax or rate. The DGT announcement PENG-6/PJ/2026 states SPP-TDLN is implemented effective 25 September 2026; the initial six issuers are BRI, Bank Mandiri, BNI, BTN, Bank Syariah Indonesia and LinkAja.
What changed in detail
Minister of Finance Regulation (PMK) No. 49 of 2026, signed on 14 July 2026, sets the procedure for collecting VAT on cross-border digital transactions through the VAT Collection System for Cross-Border Digital Transactions (SPP-TDLN). Appointed ‘Pihak Lain’ (issuers: banks and non-bank payment institutions) must collect VAT on qualifying purchases of foreign digital goods and services by Indonesian consumers once the SPP-TDLN operator confirms the transaction is subject to VAT. VAT is computed as 11/111 of the VAT-inclusive price (Article 7).
The system applies only to transactions on which VAT has not already been collected by a foreign seller appointed as a PMSE VAT collector under PMK 81/2024. It introduces no new tax and no new rate.
The Directorate General of Taxes announcement PENG-6/PJ/2026 states that SPP-TDLN is implemented effective 25 September 2026. The initial six issuers are BRI, Bank Mandiri, BNI, BTN, Bank Syariah Indonesia and LinkAja.
What it means
This is a second collection route, not a second tax. Foreign providers already appointed as PMSE VAT collectors are outside it for their own sales, but those that are not appointed may now see VAT collected at the payment stage by the issuer. Providers should check how their transactions are classified so that VAT is not collected twice. For consumers the VAT is the same, collected through the card or wallet used.
Proof
Following the enactment of Minister of Finance Regulation No. 49 of 2026, the Directorate General of Taxes (DGT) hereby informs foreign merchants and service providers that Indonesia will implement the VAT Collection System for Cross-Border Digital Transactions (SPP-TDLN) effective 25 September 2026.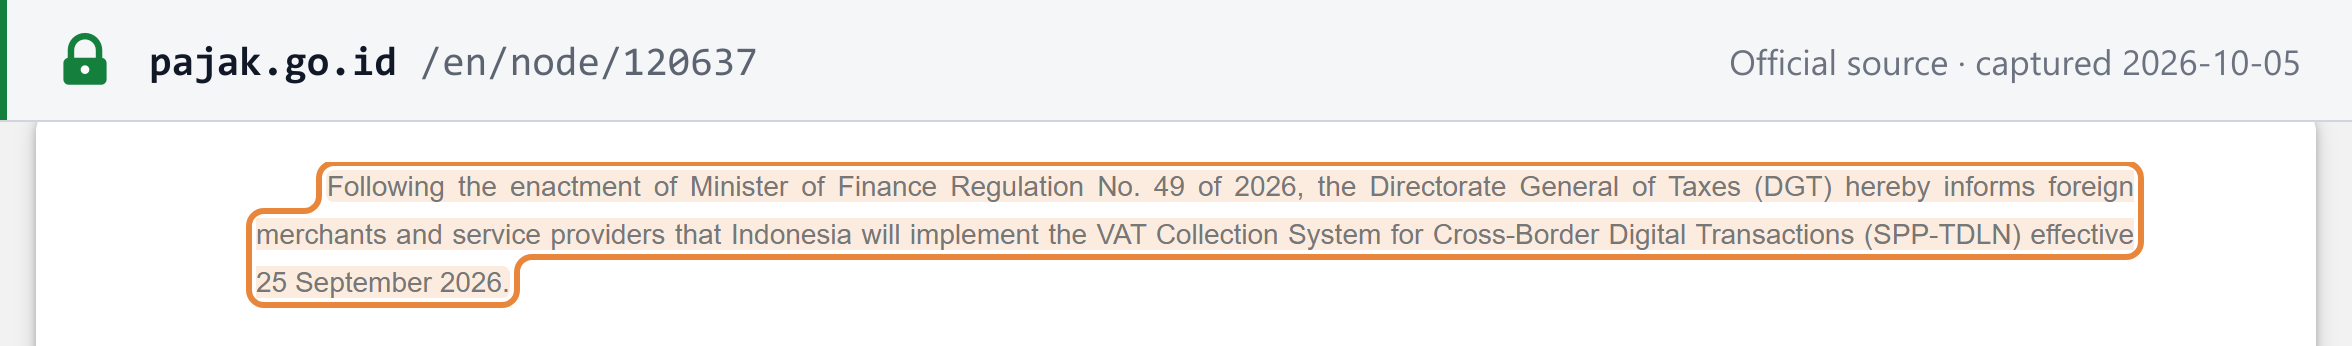 Source snapshot of the official page. Open full size ↗