Isle of Man regroups cider and sparkling wine in travellers' duty-free alcohol allowances
- Jurisdiction
- Isle of Man
- Tax
- Customs/Excise Duty
- Change type
- Update
- Status
- Enacted
- Impact
- FYI
- Announced
- 11 September 2026
- Effective
- 1 October 2026
- Authority
- Isle of Man Treasury
- Systems
- Customs
- Verified
- Fetched from official source · high confidence
Travellers bringing alcoholic products into the Isle of Man for personal use, and retailers and carriers that publish allowance guidance. No business registration or return is affected.
No action — monitoring only.
Customs
The Isle of Man Treasury announced that, from 1 October 2026, travellers' duty-free alcohol allowances are simplified by grouping similar products together: cider is reclassified into the 'beer' category with an allowance of 42 litres (up from 9 litres), and sparkling wine is reclassified into the 'wine' category with an allowance of 18 litres (up from 9 litres). This mirrors a parallel UK change under the Customs and Excise Agreement 1979.
What changed in detail
The Isle of Man Treasury announced on Friday 11 September 2026 that some travellers’ duty-free alcohol allowances change from 1 October 2026. The stated purpose is to simplify the allowances by grouping similar alcohol products together.
Two products move category. Cider takes a duty-free allowance of 42 litres and is included in the ‘beer’ category, up from 9 litres. Sparkling wine takes a duty-free allowance of 18 litres and is included in the ‘wine’ category, also up from 9 litres.
The Treasury notes that the revisions give some travellers greater flexibility to bring back a wider mix of products within the beer and wine allowances, rather than being limited by separate category thresholds — but that travellers who currently make full use of allowances across multiple alcohol categories may see a reduction in the overall quantity they can bring back duty-free.
Alcohol duty is a ‘common duty’ shared between the Isle of Man and the United Kingdom under the Customs and Excise Agreement 1979, which requires both to maintain broadly aligned legislation on common duties. The Isle of Man change accompanies the equivalent UK change.
What it means
Nothing here touches a VAT return or an excise registration; it is traveller-facing relief, and the action for a business is limited to any customer-facing allowance table it publishes.
The framing is worth reading carefully, because “up from 9 litres” is only half the story. Merging cider into beer and sparkling wine into wine replaces two separate entitlements with one shared ceiling, so a traveller who previously carried the cider allowance and the beer allowance now draws both from the same 42 litres. The Treasury says so itself. Anyone restating this as a straight increase will be restating it wrongly.
The structural point is the Customs and Excise Agreement 1979: Manx alcohol duty follows the UK by treaty, so this is a mirror of a UK change rather than an independent Manx policy, and the same will be true of the next one.
Proof
From 1 October 2026: Cider will have a duty-free allowance of 42 litres and be included in the 'beer' category (up from 9 litres); and Sparkling wine will have a duty-free allowance of 18 litres and be included in the 'wine' category (up from 9 litres)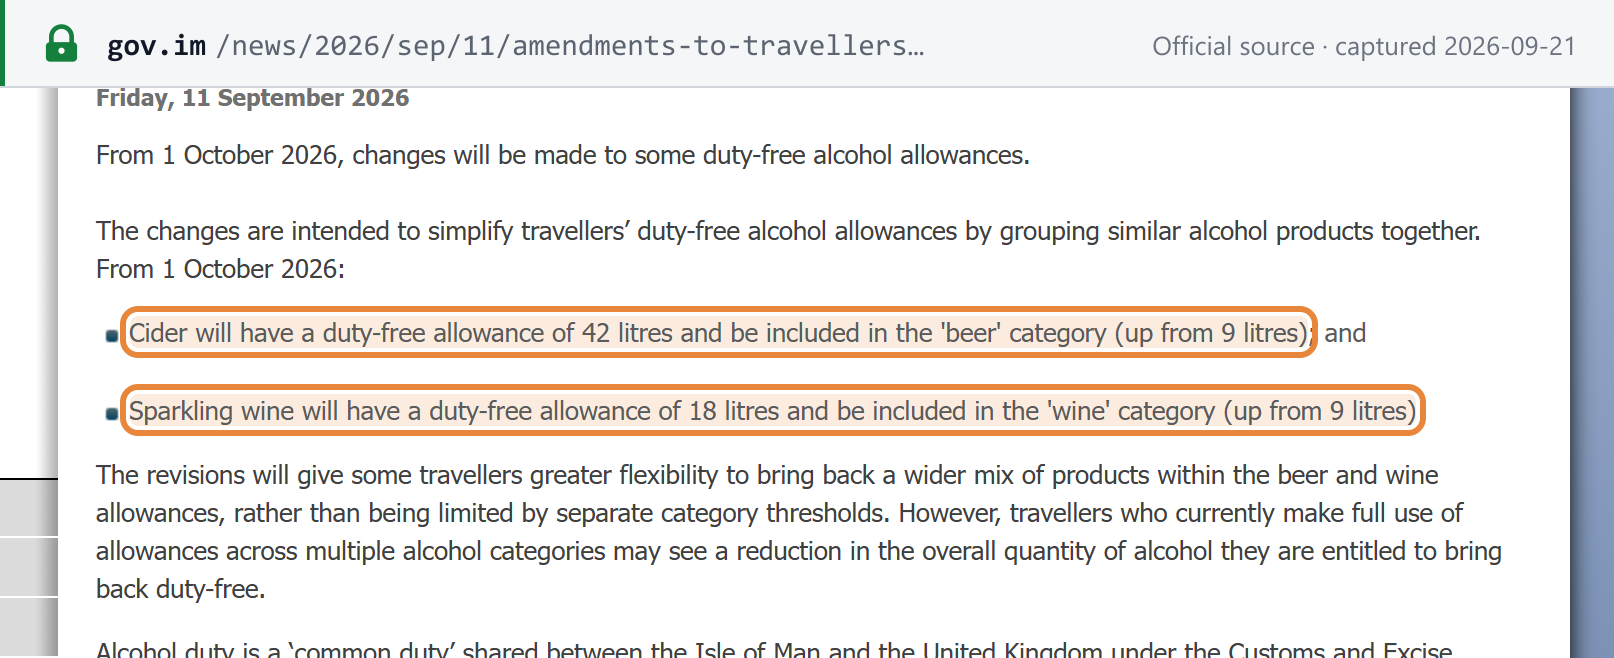 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Isle of Man Government news, Friday 11 September 2026 — "Amendments to Travellers' Duty-Free Allowances for Alcoholic Products" · www.gov.im
Alcohol duty is a 'common duty' shared between the Isle of Man and the United Kingdom under the Customs and Excise Agreement 1979. The Agreement requires the Isle of Man and the UK to maintain broadly aligned legislation in relation to common duties, including alcohol duty.Archived from the official distribution · Isle of Man Government news, 11 September 2026 — common-duty paragraph · www.gov.im