Italy extends the input-VAT deduction window to the second year after receipt
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Plan ahead
- Announced
- 11 August 2026
- Effective
- 12 August 2026
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Systems
- ERP, Reporting
- Verified
- Fetched from official source · high confidence
All Italian VAT-registered businesses recording purchase invoices and deducting input VAT under DPR 633/1972 or the consolidated VAT text.
Extend input-VAT deduction and invoice-registration windows to the second year after receipt.
ERPReporting
Article 12 of Italy's Legislative Decree No. 148 of 7 August 2026 (Gazzetta Ufficiale No. 185, Supplemento Ordinario No. 30, 11 August 2026; in force 12 August 2026) amends articles 19(1) and 25 of DPR 633/1972 so that input VAT may be deducted, and purchase invoices recorded, up to the return for the second year following the year of receipt, instead of the same year. It makes the same change to articles 56 and 88 of the consolidated VAT text (Legislative Decree No. 10 of 19 January 2026).
What changed in detail
Article 12 of Legislative Decree No. 148 of 7 August 2026 (Gazzetta Ufficiale No. 185, Supplemento Ordinario No. 30, 11 August 2026; in force 12 August 2026) amends articles 19(1) and 25 of DPR 633/1972, Italy’s VAT code. Input VAT may now be deducted, and purchase invoices recorded, up to the return for the second year following the year in which the invoice was received, instead of the same year as before. The decree makes the identical change to articles 56 and 88 of the consolidated VAT text (Legislative Decree No. 10 of 19 January 2026), so the extended window applies under both instruments.
The same Article 12 also replaces the purchase-price definition for deemed supplies, the place-of-supply presence test, the Capital Assets Scheme apportionment mechanism, and tax credit notes elsewhere in the decree — this record covers only the deduction-window change to articles 19 and 25/56 and 88.
What it means
A full extra year to deduct input VAT and record a purchase invoice gives finance teams more room to catch a late or disputed supplier invoice without losing the deduction — previously, missing the same-year deadline meant the credit was gone. Accounts-payable and VAT-return processes built around a same-year cut-off should be re-checked now that the compliance window is materially longer; the risk this removes is a hard one, not a soft one — an invoice that surfaces late used to mean lost input tax, and now it usually does not.
Proof
a) all’articolo 19, comma 1, secondo periodo, le parole: «all’anno» sono sostituite dalle seguenti: «al secondo anno successivo a quello»;(a) in article 19, paragraph 1, second sentence, the words "the year" are replaced with the following: "the second year following that";
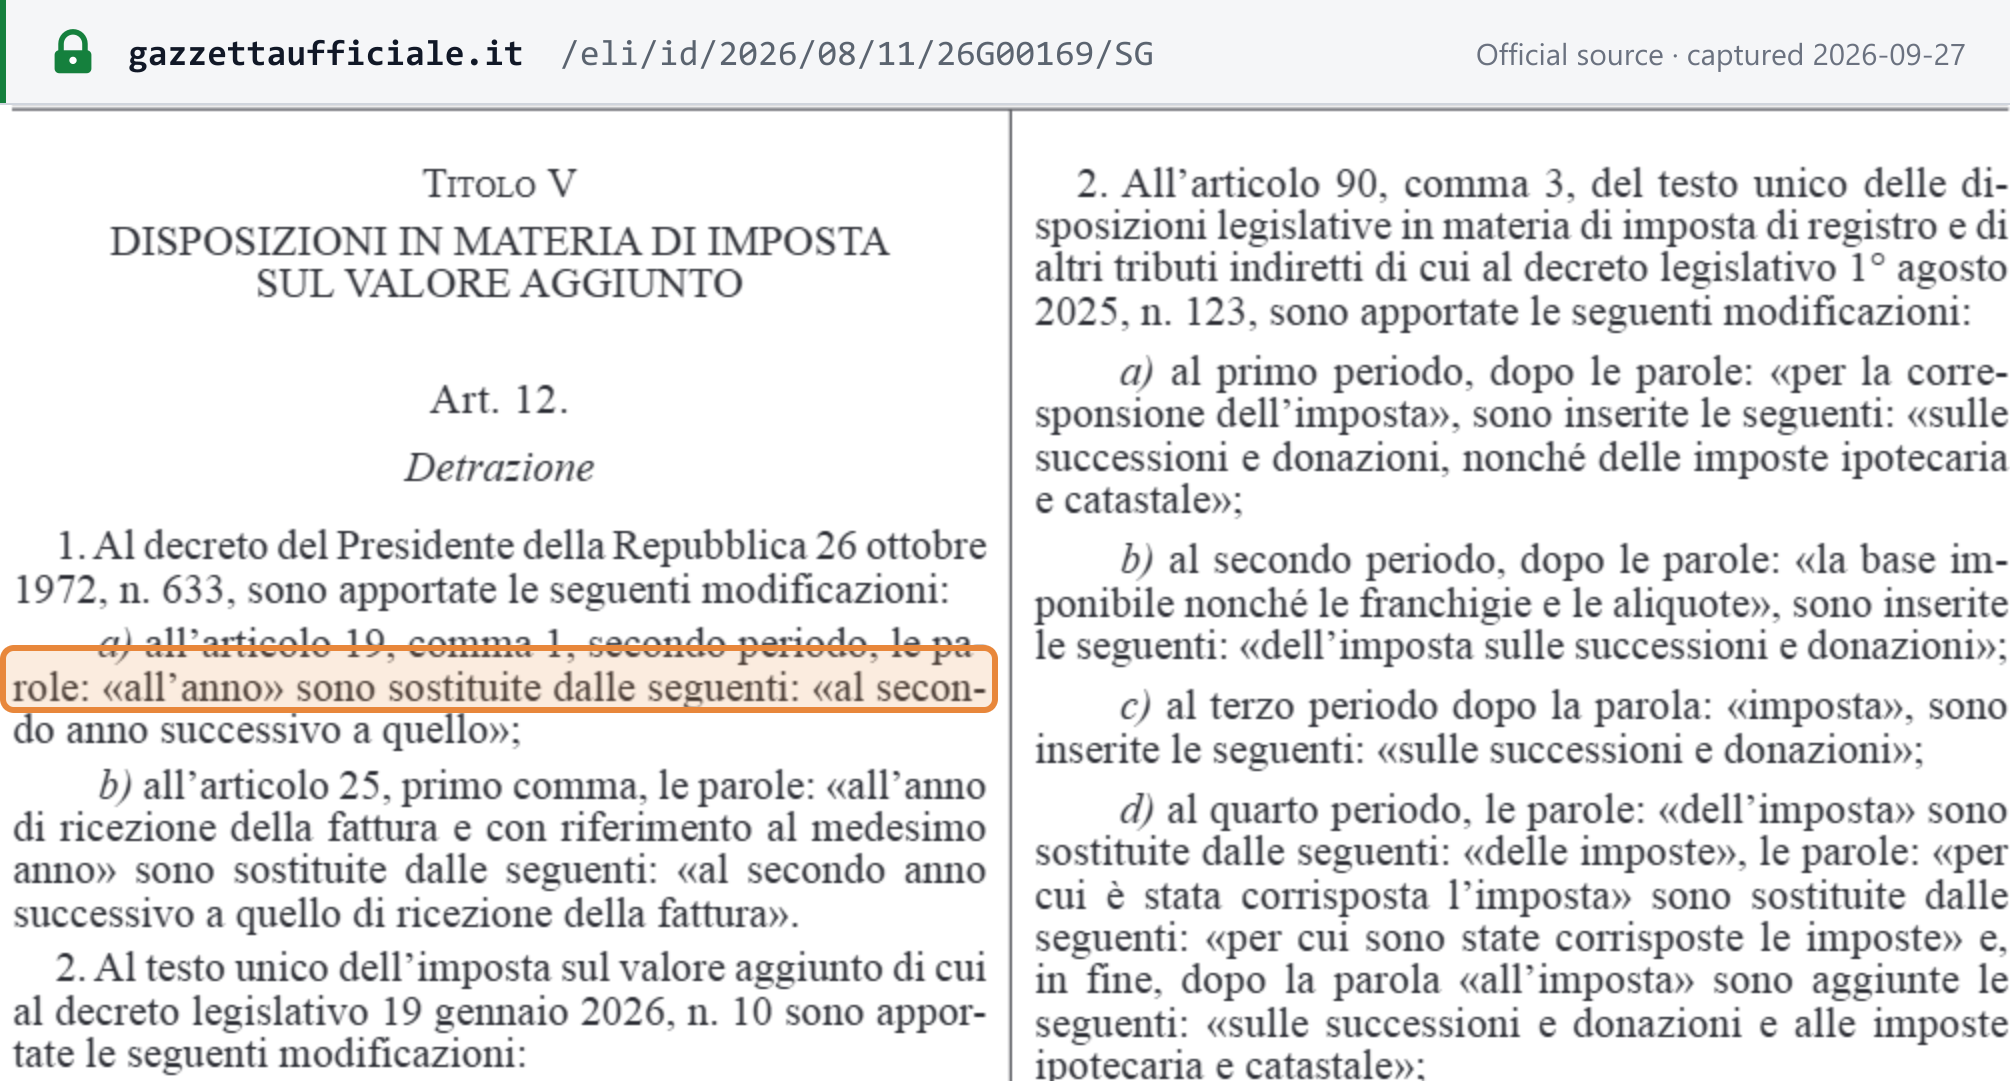 Source snapshot of the official page. Open full size ↗