Italy sets F24 tax codes for payments after omitted-VAT-return communications (Risoluzione 34/E)
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 30 September 2026
- Authority
- Agenzia delle Entrate (Italian Revenue Agency)
- Systems
- Reporting, Tax engine
- Verified
- Fetched from official source · high confidence
Italian VAT payers who receive an article 54-bis.1 communication for an omitted annual VAT return.
Map F24 codes 9005, 95AA, 95BB and 95CC in payment workflows if Italian VAT returns may be omitted.
ReportingTax engine
Agenzia delle Entrate Risoluzione n. 34/E of 30 September 2026 establishes F24 tax codes for paying sums due after communications issued under Article 54-bis.1 of DPR 633/1972 (automated liquidation of VAT for omitted annual VAT returns): code 9005 for the full amount, and codes 95AA (tax), 95BB (interest) and 95CC (penalties) for partial payment. Compensation under Article 17 of Legislative Decree 241/1997 is not available for these payments.
What changed in detail
Agenzia delle Entrate Risoluzione n. 34/E of 30 September 2026 establishes F24 tax codes for paying sums due after communications issued under Article 54-bis.1 of DPR 633/1972. That article covers the automated liquidation of VAT where an annual VAT return was omitted.
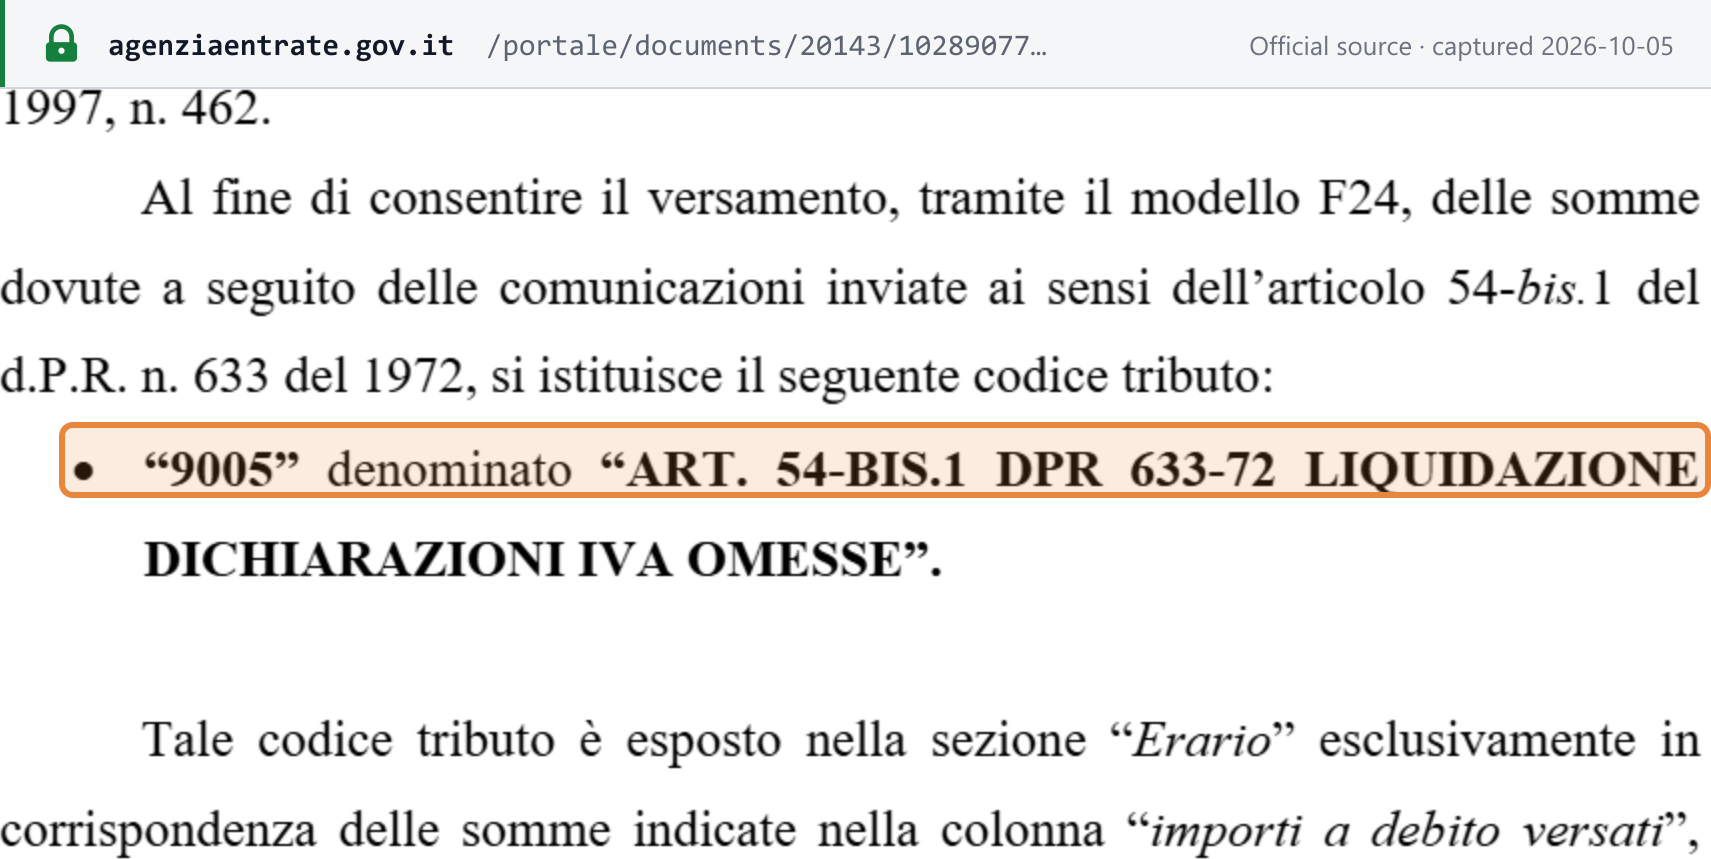
Code 9005 is used for payment of the full amount. For partial payment, code 95AA is used for the tax, code 95BB for the interest and code 95CC for the penalties. Compensation under Article 17 of Legislative Decree 241/1997 is not available for these payments.
What it means
The practical point is the choice of code at payment. A taxpayer paying the whole amount uses 9005; one paying in part must split the payment between tax (95AA), interest (95BB) and penalties (95CC). Because offsetting credits against these sums is not permitted, they must be paid directly. Using the wrong code risks the payment not being matched to the communication.
Proof
• “9005” denominato “ART. 54-BIS.1 DPR 633-72 LIQUIDAZIONE DICHIARAZIONI IVA OMESSE”."9005" named "ART. 54-BIS.1 DPR 633-72 LIQUIDATION OF OMITTED VAT RETURNS".
 Source snapshot of the official page. Open full size ↗