Italy's VAT consolidated text (D.Lgs. 10/2026) applies from 1 January 2027 and replaces most of DPR 633/1972
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 30 January 2026
- Effective
- 1 January 2027
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Systems
- Invoicing, Tax engine, ERP, Reporting
- Verified
- Fetched from official source · high confidence
All VAT-registered businesses and advisers in Italy that cite DPR 633/1972.
Update statute citations (DPR 633/1972 article references to Testo unico articles) in invoice templates, tax-engine rule IDs and reporting from 1 Jan 2027.
InvoicingTax engineERPReporting
Legislative Decree 19 January 2026, n. 10 (GU n. 24, S.O. n. 4, 30 January 2026; in force 31 January 2026) approved the Testo unico delle disposizioni legislative in materia di imposta sul valore aggiunto. Article 171 of the Testo unico provides that its provisions apply from 1 January 2027; Article 170 abrogates from that date, among others, articles 1 to 17, 17-ter to 27 and further listed articles of DPR 26 October 1972 n. 633 and its tables A, B and C, and Article 170(3) re-points references to abrogated provisions to the corresponding provisions of the Testo unico.
What changed in detail
Legislative Decree 19 January 2026, n. 10 approved the Testo unico delle disposizioni legislative in materia di imposta sul valore aggiunto, Italy’s consolidated VAT text. It was published in the Gazzetta Ufficiale n. 24, supplemento ordinario n. 4, of 30 January 2026 and is in force from 31 January 2026.
Article 171 provides that the provisions of the Testo unico apply from 1 January 2027. From that date Article 170 abrogates, among others, articles 1 to 17 and 17-ter to 27 and further listed articles of DPR 26 October 1972 n. 633, together with its tables A, B and C. Article 170(3) re-points references to the abrogated provisions to the corresponding provisions of the Testo unico.
What it means
This is a re-codification date, not a change of rate or rule as such. From 1 January 2027, citations to DPR 633/1972 articles that have been abrogated should be read through the Article 170(3) re-pointing to the Testo unico. Invoice templates, tax-engine rule references, internal policies and advisers’ checklists that cite article numbers of DPR 633/1972 should be mapped to the new numbering before that date.
Proof
1. Le disposizioni del presente testo unico si applicano a decorrere dal 1° gennaio 2027.The provisions of this consolidated text apply from 1 January 2027.
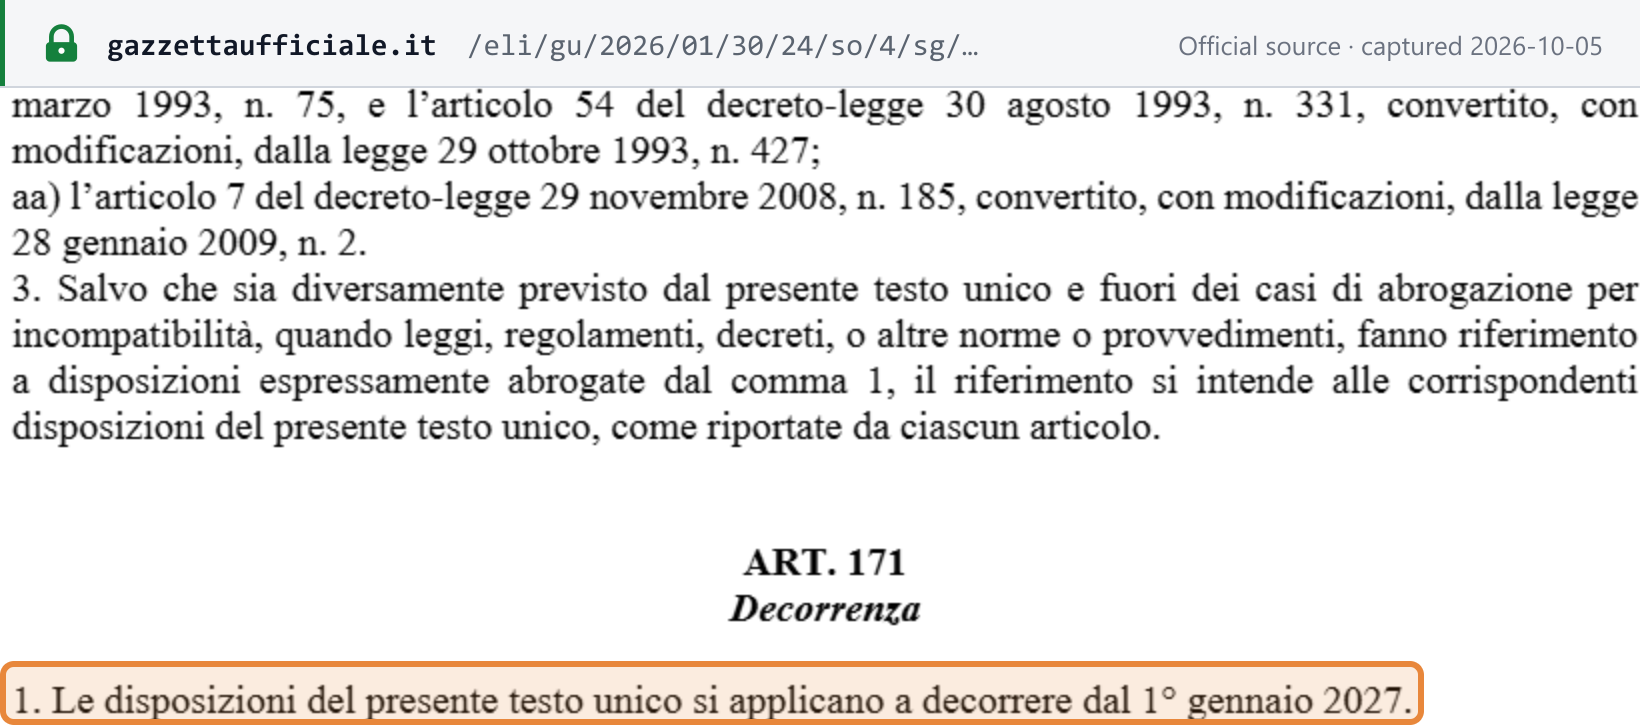 Source snapshot of the official page. Open full size ↗