Jersey's Proposed Budget 2027-2030 lists technical GST changes — proposals only, pending the Finance Law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
- Jurisdiction
- Jersey
- Tax
- GST
- Change type
- Compliance
- Status
- Proposed
- Impact
- Watch
- Announced
- 29 September 2026
- Authority
- Government of Jersey
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
GST-registered groups in Jersey, suppliers of medical services and goods, and businesses involved in storing investment assets.
No action - monitoring only.
Tax engineReporting
The Government of Jersey's Proposed Budget 2027-2030 (lodged with the States Assembly on 29 September 2026) lists technical GST measures to be included in the Draft Finance (2027 Budget) (Jersey) Law: removal of the 90-day lead-in time to vary a GST group registration, and amendments to the GST Law's medical-supply exemption to align with the forthcoming Health and Social Care Professionals Register (Jersey) Law. The budget also proposes tax warehouses for investment assets allowing storage and transfer without triggering GST and customs/excise duties provided the assets do not enter the domestic market. The GST rate (5%) is unchanged. Measures are provisional until the Finance Law is adopted.
What changed in detail
These are proposals, not law. The Government of Jersey’s Proposed Budget 2027-2030 was lodged with the States Assembly on 29 September 2026, and the measures are provisional until the Finance Law is adopted.
The budget lists technical GST measures to be included in the Draft Finance (2027 Budget) (Jersey) Law. The 90-day lead-in time to vary a group registration for GST is removed. The GST Law’s medical-supply exemption would be amended to align with the forthcoming Health and Social Care Professionals Register (Jersey) Law. The budget also proposes tax warehouses for investment assets, allowing storage and transfer without triggering GST and customs and excise duties provided the assets do not enter the domestic market. The GST rate of 5 per cent is unchanged.
What it means
These are housekeeping measures rather than a change to the rate. The group registration change matters to businesses that restructure groups, since variations would no longer wait 90 days. Nothing applies until the Finance Law is adopted.
Proof
The 90-day lead-in time to vary a group registration for GST is removed.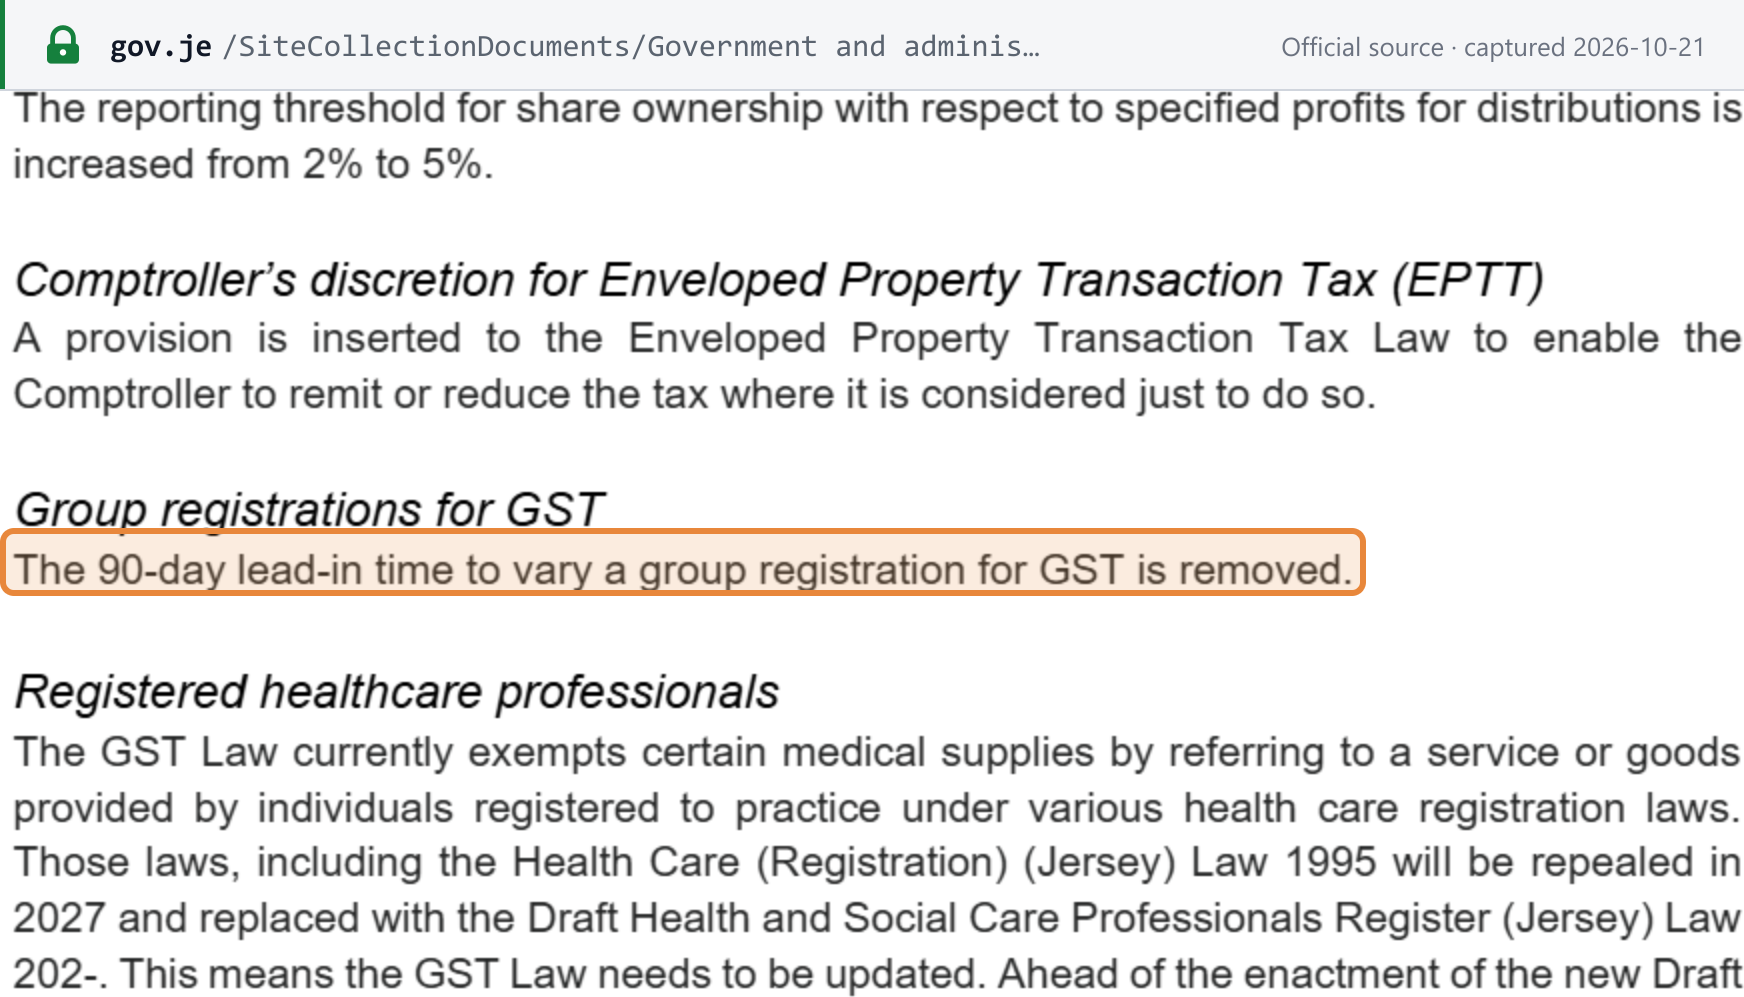 Source snapshot of the official page. Open full size ↗