Kenya extends the 8% VAT rate on petrol, kerosene and diesel from 15 July to 14 October 2026 (Legal Notice No. 128)
This page records one dated change. For the rules in Kenya as they stand today, see the Kenya guide →
- Jurisdiction
- Kenya
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 14 July 2026
- Effective
- 15 July 2026
- Authority
- Kenya Revenue Authority
- Systems
- POS, Tax engine, Invoicing
- Verified
- Fetched from official source · high confidence
Importers, distributors and retailers of premium motor spirit, illuminating kerosene and automotive light gas oil in Kenya.
No action - monitoring only; confirm which rate applies to fuel supplies after 14 October 2026 before invoicing.
POSTax engineInvoicing
Legal Notice No. 128 of 2026, the Value Added Tax (Amendment of Rate of Tax) Order, 2026 (Kenya Gazette Supplement No. 178, 14 July 2026), reduces the VAT rate under section 5(2)(b) of the VAT Act from 16% to 8% on premium motor spirit (tariff 2710.12.20), illuminating kerosene (2710.19.22) and automotive light gas oil (2710.19.31) from 15 July 2026 up to 14 October 2026. It extends the 8% rate that applied from 15 April to 14 July 2026.
What changed in detail
Legal Notice No. 128 of 2026, the Value Added Tax (Amendment of Rate of Tax) Order, 2026, was published in Kenya Gazette Supplement No. 178 on 14 July 2026. Under section 6(1) of the VAT Act, the Cabinet Secretary for the National Treasury reduces the rate under section 5(2)(b) from 16% to 8% on goods in its Schedule, from 15 July 2026 up to 14 October 2026.
The Schedule lists premium motor spirit (tariff 2710.12.20), illuminating kerosene (2710.19.22) and automotive light gas oil (2710.19.31).
The order extends the 8% rate that applied from 15 April to 14 July 2026.
What it means
The reduced rate was time-limited and the notice’s stated end date, 14 October 2026, has passed. Supplies after that date need to be checked against any later legal notice rather than assumed to stay at 8%. For supplies between 15 July and 14 October 2026, the 8% rate applies to the three products listed.
Proof
reduces the rate of tax specified in section 5 (2) (b) of the Act from sixteen per cent to eight per cent in respect of the goods listed in the Schedule hereto, with effect from the 15th July, 2026 up to the 14th October, 2026.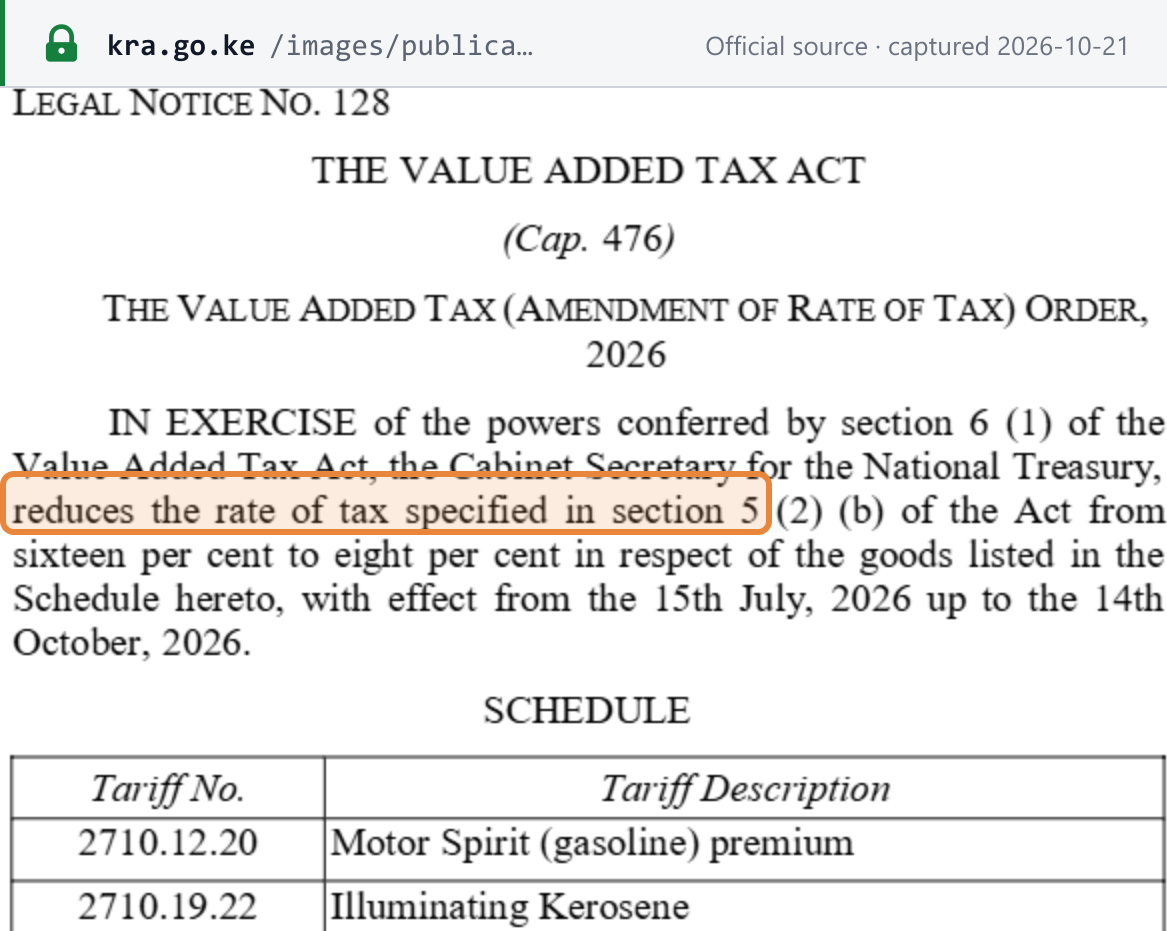 Source snapshot of the official page. Open full size ↗