Lithuania bill would restore the 9% VAT rate on residential heating
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Lithuania as they stand today, see the Lithuania guide →
- Jurisdiction
- Lithuania
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 17 September 2026
- Effective
- 1 January 2027
- Authority
- Lietuvos Respublikos Seimas
- Verified
- Fetched from official source · high confidence
Suppliers of heat energy for heating residential premises, including hot water supplied to residential premises and the heat used to heat it — no action while this remains a bill.
No action — monitoring only.
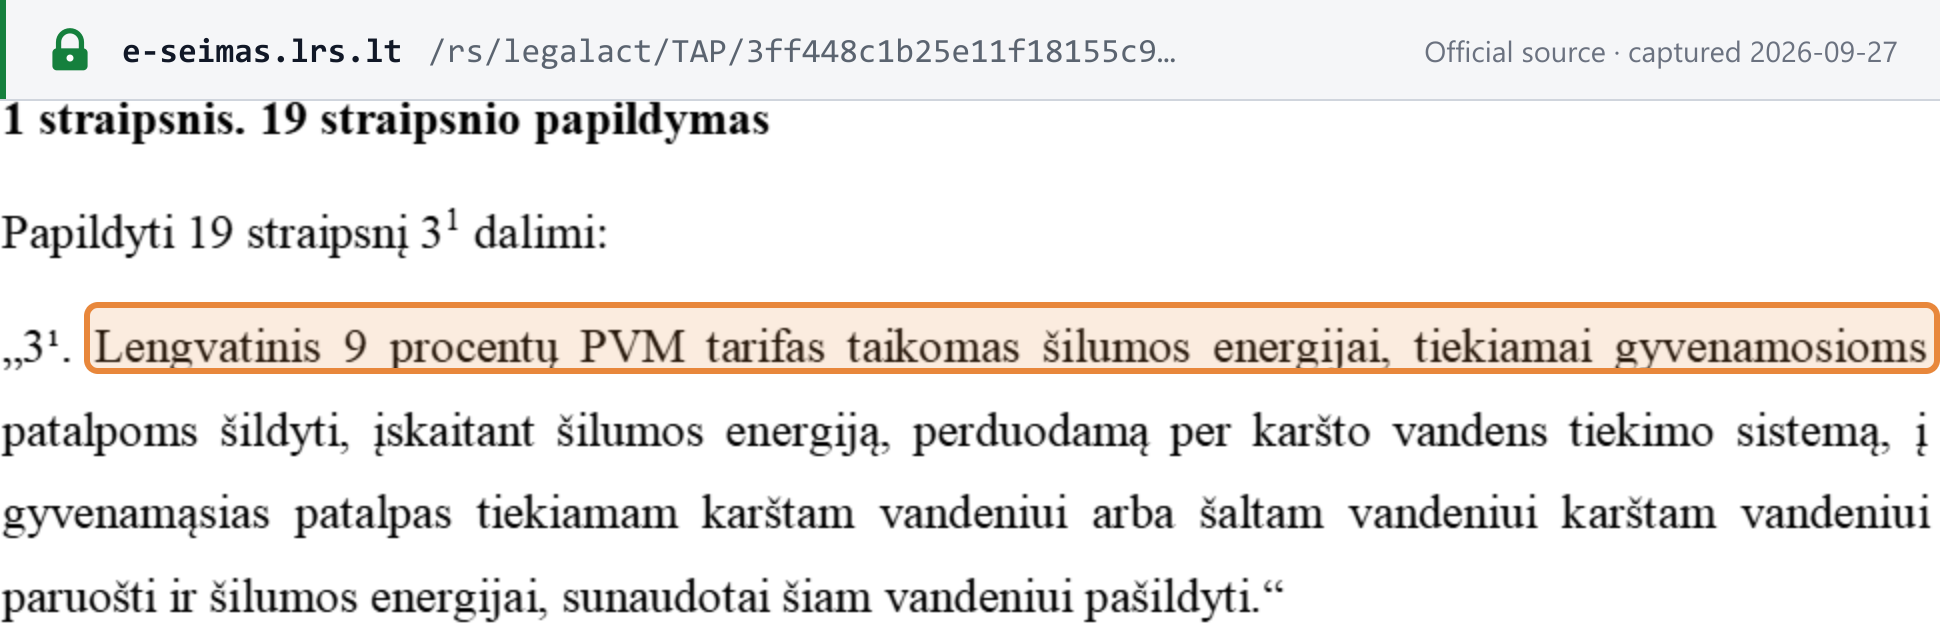
A bill registered in the Seimas on 17 September 2026 as No. XVP-1853, sponsored by Member of the Seimas Arvydas Anušauskas, would add paragraph 3¹ to Article 19 of the Law on VAT No. IX-751 to apply a reduced 9% rate to heat energy supplied for heating residential premises, including hot water supplied to residential premises and the heat used to heat it, from 1 January 2027. The bill is at the registration stage and has not been debated.
What changed in detail
The bill is not law. A draft amendment to Article 19 of Lithuania’s VAT Law No. IX-751 was registered in the Seimas on 17 September 2026 as bill No. XVP-1853, sponsored by Member of the Seimas Arvydas Anušauskas. It would add a new paragraph 3¹ applying a reduced 9% VAT rate to heat energy supplied for heating residential premises, including hot water supplied to residential premises and the heat used to heat it. The bill sets a planned entry-into-force date of 1 January 2027.
The bill is at the registration stage only and has not yet been debated in the Seimas.
What it means
This would reverse the removal of the 9% reduced rate for residential heating, restoring a lower rate on household heating bills — but nothing changes yet, and a registered bill can be amended, delayed or dropped before any vote. Suppliers and billing systems should treat this as a signal to watch rather than a rate to schedule; the standard rate continues to apply until, and unless, this bill is enacted and a commencement date is confirmed in a published act.
Proof
Lengvatinis 9 procentų PVM tarifas taikomas šilumos energijai, tiekiamai gyvenamosioms patalpoms šildytiA reduced 9 percent VAT rate applies to heat energy supplied for heating residential premises
 Source snapshot of the official page. Open full size ↗