Malta transposes ViDA into the VAT Act through Act III of 2026, in force from 1 January 2027
This page records one dated change. For the rules in Malta as they stand today, see the Malta guide →
- Jurisdiction
- Malta
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 10 March 2026
- Effective
- 1 January 2027
- Authority
- Malta Tax and Customs Administration (MTCA)
- Systems
- Tax engine, ERP, E-commerce
- Verified
- Fetched from official source · high confidence
E-commerce platforms facilitating intra-EU supplies of goods to Maltese customers, Union and non-Union OSS and IOSS registrants, and businesses using the call-off stock simplification for goods moved to or from Malta.
Sellers using OSS/IOSS or the call-off stock simplification for Malta should review deemed-supplier scope, the OSS EUR 10,000 threshold treatment, and call-off stock timelines ahead of the 1 January 2027 commencement.
Tax engineERPE-commerce
Malta's Budget Measures Implementation Act, 2026 (Act III of 2026, published in the Government Gazette of Malta No. 21,599 on 10 March 2026) amends the VAT Act (Cap. 406) to transpose Article 2 of Council Directive (EU) 2025/516 (ViDA). The ViDA-transposition amendments extend the deemed-supplier rule for e-commerce platforms facilitating intra-EU goods supplies, phase out the call-off stock simplification for goods dispatched on or before 30 June 2028, and clarify application of the EUR 10,000 One Stop Shop (OSS) distance-selling threshold and OSS/IOSS input-VAT and cash-accounting rules. Per the Malta Tax and Customs Administration's explanatory notes, these ViDA-transposition amendments to the VAT Act come into force on 1 January 2027; the Act's other (non-ViDA) VAT Act amendments came into force on the Act's publication date.
What changed in detail
The Budget Measures Implementation Act, 2026 (Act III of 2026), published in the Government Gazette of Malta No. 21,599 on 10 March 2026, amends the Value Added Tax Act (Cap. 406). The Malta Tax and Customs Administration’s explanatory notes group the amendments in three: those transposing Article 2 of Council Directive (EU) 2025/516 (ViDA), those clarifying existing VAT Act provisions, and cosmetic changes.
On the ViDA side the notes record four operative changes. Sub-item (2) of item 12A of the Second Schedule is substituted, extending the deemed-supplier rule to e-commerce platforms facilitating supplies of goods within the EU to taxable persons, or to non-taxable legal persons whose intra-Community acquisitions are not subject to VAT. Item 17A(2)(a) is substituted and item 17A(8) added, phasing out the call-off stock simplification for goods dispatched or transported on or before 30 June 2028, ahead of the ViDA transfer-of-own-goods scheme. Item 4(5) of Part One and item 10(2) of Part Two of the Third Schedule are amended to clarify the EUR 10,000 OSS threshold: a person registered under an OSS special scheme is automatically treated as having opted for the alternative place-of-supply rules. Item 2(2) of Part One of the Fourteenth Schedule is substituted so that supplies made under the non-Union and Union OSS schemes cannot be subject to cash accounting.
The explanatory notes state that the amendments necessary to transpose Article 2 of ViDA come into force on 1 January 2027, and that all other amendments came into force on publication.
What it means
Malta did its ViDA transposition early and quietly, inside the budget implementation act rather than a standalone VAT law — so anyone watching for a Maltese “ViDA bill” will have missed it. The text is on the statute book now; only the commencement is a year out.
Two of the four changes bite before 2027 in planning terms. The call-off stock phase-out turns on dispatch date, so arrangements running into mid-2028 need a migration path to the transfer-of-own-goods scheme rather than a renewal. And the OSS cash-accounting exclusion removes a combination some Maltese businesses were relying on: if your OSS supplies were being cash-accounted, that has to change before commencement, not after it.
Proof
Amendments necessary to transpose Article 2 of ViDA shall come into force on 1st January 2027. All other amendments shall come into force upon the date of publication of the Act.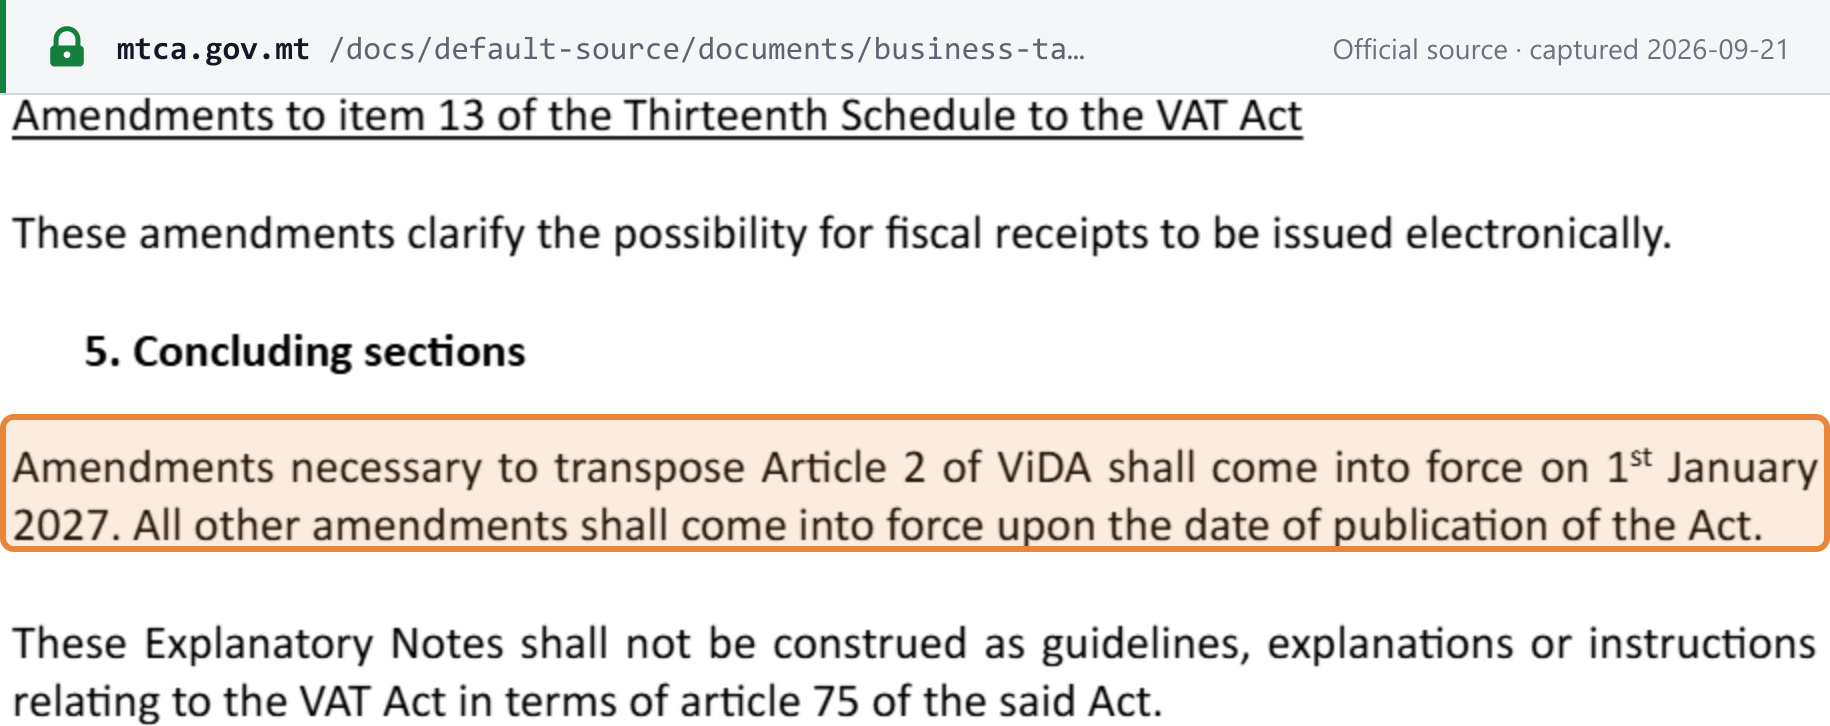 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Explanatory Notes for the purpose of article 3(2)(c) of Chapter 512 of the Laws of Malta — Budget Measures Act 2026 / VAT Act (Cap. 406), section 5 · mtca.gov.mt