Dutch bill 36 920 on single VAT registration passes the Tweede Kamer and goes to the Eerste Kamer
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Netherlands as they stand today, see the Netherlands guide →
- Jurisdiction
- Netherlands
- Tax
- VAT
- Change type
- Registration
- Status
- Proposed
- Impact
- Watch
- Announced
- 17 September 2026
- Effective
- 1 January 2027
- Authority
- Eerste Kamer der Staten-Generaal
- Systems
- Tax engine, Reporting, ERP
- Verified
- Fetched from official source · high confidence
Businesses selling cross-border to EU consumers, using the OSS Union scheme or call-off stock arrangements.
Prepare OSS-scope and call-off-stock/transfer changes for 1 January 2027; confirm the Eerste Kamer vote of 6 October 2026 and Staatsblad publication before treating as law.
Tax engineReportingERP
Bill 36 920, the Wet implementatie Richtlijn btw in het digitale tijdperk – enkele btw-registratie, which implements the single-VAT-registration part of Directive (EU) 2025/516 (extension of the OSS Union scheme and a new transfer-of-own-goods arrangement replacing call-off stock, integrated into the OSS), was passed by the Tweede Kamer as a hamerstuk on 17 September 2026. The Eerste Kamer finance committee issued a blank report on 29 September 2026 and the Senate is scheduled to dispose of it as a hamerstuk on 6 October 2026. The bill provides for entry into force on 1 January 2027 (or retroactively to that date if published later).
What changed in detail
Bill 36 920 is a bill, not yet law. It is the Wet implementatie Richtlijn btw in het digitale tijdperk – enkele btw-registratie, which implements the single-VAT-registration part of Directive (EU) 2025/516. That part extends the OSS Union scheme and adds a new transfer-of-own-goods arrangement integrated into the OSS, while call-off stock is gradually abolished.
The Tweede Kamer passed the bill as a hamerstuk on 17 September 2026. The Eerste Kamer finance committee issued a blank report on 29 September 2026, and the Senate is scheduled to dispose of it as a hamerstuk on 6 October 2026. As of 5 October 2026 that vote had not taken place. The bill provides for entry into force on 1 January 2027, or retroactively to that date if it is published later.
What it means
The Senate step on 6 October is scheduled as a hamerstuk, but the bill is not law until it has been passed and published. Businesses using call-off stock should plan for the replacement arrangement from 1 January 2027, and those registered in several EU member states should check which registrations the single registration can replace.
Proof
Het voorstel (EK, A) is op 17 september 2026 als hamerstuk afgedaan door de Tweede Kamer.The proposal (EK, A) was disposed of as a hamerstuk by the Tweede Kamer on 17 September 2026.
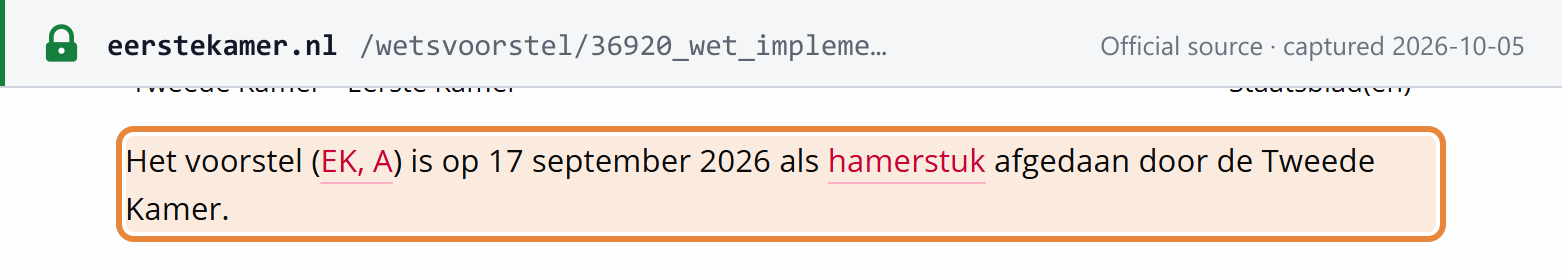 Source snapshot of the official page. Open full size ↗