Norway requires B2B electronic invoices, issued and received, from 1 January 2027 (Bookkeeping Act amendment)
This page records one dated change. For the rules in Norway as they stand today, see the Norway guide →
- Jurisdiction
- Norway
- Tax
- VAT
- Change type
- E-invoicing
- Status
- Enacted
- Impact
- Action required
- Announced
- 19 June 2026
- Effective
- 1 January 2027
- Authority
- Lovdata
- Systems
- ERP, Invoicing
- Verified
- Fetched from official source · high confidence
Norwegian bookkeeping-liable businesses that sell to or buy from other bookkeeping-liable parties.
Be ready to both issue and receive structured e-invoices to/from Norwegian bookkeeping-liable counterparties from 1 January 2027; do not rely on a NOK 50,000 exemption or a mandated EHF format until regulations under s. 10(4) are published.
ERPInvoicing
Under lov 19. juni 2026 nr. 39 amending the Bookkeeping Act, new section 10 second paragraph requires documentation of sales of goods and services to other bookkeeping-liable parties to be issued, and documentation of purchases from them to be received, in electronic invoice format. Royal resolution FOR-2026-06-19-1154 brings Part I sections 3, 10, 11 and 13 of the amending Act into force on 1 January 2027, so both issuing and receiving apply from that date; only Part I section 7 fourth paragraph (bookkeeping in an electronic accounting system) takes effect on 1 January 2030. The Act defines an electronic invoice as a sales document issued, sent and received in a structured electronic format suitable for automated processing and names no specific format; it contains no turnover-based exemption. Format requirements and exemptions are left to regulations or individual decisions under section 10 fourth paragraph. This corrects no-b2b-einvoice-bookkeeping-act-2026 (2026-W26), which gave a later receiving date, a named format and a NOK 50,000 exemption that the Act does not contain.
What changed in detail
Under lov 19. juni 2026 nr. 39 amending the Bookkeeping Act, new section 10 second paragraph requires documentation of sales of goods and services to other bookkeeping-liable parties to be issued, and documentation of purchases from them to be received, in electronic invoice format.
Royal resolution FOR-2026-06-19-1154 brings Part I sections 3, 10, 11 and 13 of the amending Act into force on 1 January 2027, so both issuing and receiving apply from that date. Only Part I section 7 fourth paragraph (bookkeeping in an electronic accounting system) takes effect on 1 January 2030.
The Act defines an electronic invoice as a sales document issued, sent and received in a structured electronic format suitable for automated processing, and names no specific format. It contains no turnover-based exemption. Format requirements and exemptions are left to regulations or individual decisions under section 10 fourth paragraph.
This replaces an earlier account (no-b2b-einvoice-bookkeeping-act-2026) that gave a later receiving date, a named format and a NOK 50,000 exemption, none of which appear in the Act.
What it means
The Act itself puts both sides on the same day, but it left the receiving date, the formats and any exemptions to secondary legislation, and that legislation has since been made. FOR-2026-09-25-1913 gives businesses until 1 January 2030 to meet the receive duty, while issuing still starts on 1 January 2027. FOR-2026-09-29-1933 names EHF and Peppol BIS 3.0 as the formats and sets a narrow NOK 50,000 exemption. Plan from those two records, not from the Act alone.
Proof
Dokumentasjon for kjøp av varer og tjenester fra andre bokføringspliktige skal tilsvarende mottas i elektronisk fakturaformat.Documentation for purchases of goods and services from other bookkeeping-liable parties shall likewise be received in electronic invoice format.
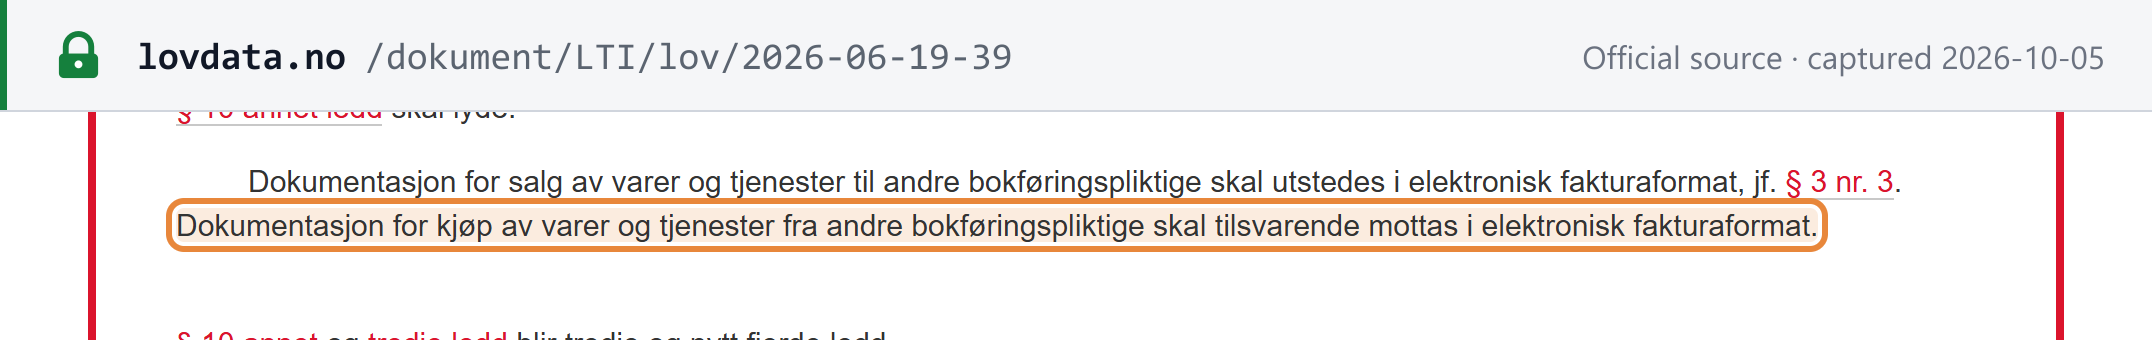 Source snapshot of the official page. Open full size ↗
Sources
- Lov om endringer i bokføringsloven og enkelte andre lover på finansmarkedsområdet (pliktig digital bokføring og e-fakturering mv.) — LOV-2026-06-19-39
- Delt ikraftsetting av lov 19. juni 2026 nr. 39 om endringer i bokføringsloven og enkelte andre lover på finansmarkedsområdet (pliktig digital bokføring og e-fakturering mv.) — FOR-2026-06-19-1154
What this replaces
- On 8 June 2026 the Storting adopted Prop. effective 1 January 2027