Norway: VAT-registered entities must reverse-charge remote services from abroad even for non-economic activity
This page records one dated change. For the rules in Norway as they stand today, see the Norway guide →
- Jurisdiction
- Norway
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- FYI
- Announced
- 1 October 2026
- Authority
- Skatteetaten (Norwegian Tax Administration)
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Norwegian legal persons registered in the VAT Register that buy remote services from foreign suppliers, including those with non-economic activity.
Check that self-assessment (reverse charge) on imported remote services is applied to purchases for non-economic activity by VAT-registered Norwegian entities.
Tax engineReporting
On 1 October 2026 the Norwegian Tax Directorate (Skattedirektoratet) published a statement that a legal person registered in the VAT Register must itself calculate and pay VAT under the reverse-charge rules (VAT Act section 11-3 first paragraph) on remote services bought from a foreign supplier, including where the service is used in the entity's non-economic (ideal) activity; the foreign supplier does not charge Norwegian VAT in that case. The use of the service affects the right of deduction.
What changed in detail
On 1 October 2026 the Norwegian Tax Directorate (Skattedirektoratet) published a statement on VAT Act section 11-3 first paragraph. It says that a legal person registered in the VAT Register must itself calculate and pay VAT under the reverse-charge rules on remote services bought from a foreign supplier.
This applies including where the service is used in the entity’s non-economic (ideal) activity. In that case the foreign supplier does not charge Norwegian VAT. The use of the service affects the right of deduction.
What it means
The catch is the non-economic activity: an entity such as an association or a public body that is VAT-registered for part of what it does cannot treat remote services used for its non-economic side as outside Norwegian VAT. It accounts for the reverse-charge VAT itself, and the right of deduction then turns on how the service is used. Check supplier invoices carefully, since foreign suppliers will not charge Norwegian VAT in this case.
Proof
Skattedirektoratet legger til grunn at den registrerte mottakeren skal beregne og betale merverdiavgiften etter reglene om snudd avregningThe Tax Directorate assumes that the registered recipient shall calculate and pay the VAT under the rules on reverse charge.
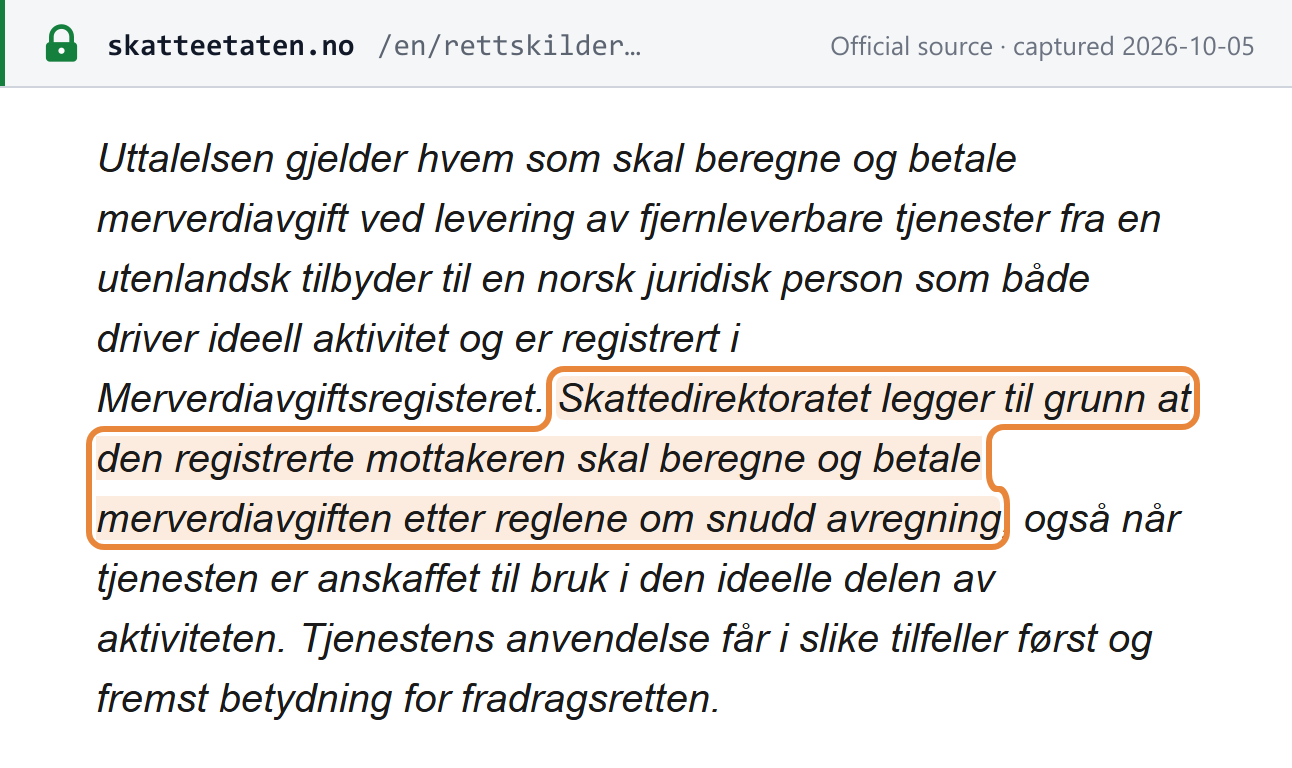 Source snapshot of the official page. Open full size ↗