Pakistan penalises failure to integrate with the FBR system with fines up to Rs 5 million and premises sealing (Finance Act 2026)
This page records one dated change. For the rules in Pakistan as they stand today, see the Pakistan guide →
- Jurisdiction
- Pakistan
- Tax
- Sales Tax
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 26 June 2026
- Effective
- 1 July 2026
- Authority
- Federal Board of Revenue, Pakistan
- Systems
- Invoicing, POS, Reporting
- Verified
- Fetched from official source · medium confidence
Persons in Pakistan required to integrate their business with the FBR computerised system for monitoring, tracking, reporting or recording of sales, production and similar transactions.
Registered persons not yet integrated with the FBR system should integrate before the penalty and sealing provisions are applied.
InvoicingPOSReporting
Correction of record: Pakistan's Finance Act, 2026 (assented 26 June 2026, Gazette of Pakistan Extraordinary; in force 1 July 2026) does not provide 'suspension or blacklisting' for failure to integrate with the FBR e-invoicing and production-monitoring systems, as the earlier entry stated. Its amendment of the section 33 penalty table of the Sales Tax Act 1990 (S. No. 25) provides a penalty of up to Rs 1 million for failing to integrate within the time notified by the Board, a second penalty of up to Rs 5 million if the offence continues one month after the first penalty, and sealing of business premises by an Inland Revenue officer with or without a penalty. Integration is due 'within the stipulated time as notified by the Board', not automatically from 1 July 2026.
What changed in detail
Pakistan’s Finance Act, 2026 (Act No. XLIII of 2026) received the President’s assent on 26 June 2026. It was published in the Gazette of Pakistan Extraordinary and comes into force, unless otherwise provided, on 1 July 2026.
Section 4 of the Act amends the Sales Tax Act, 1990. It substitutes the entry at S. No. 25 of the penalty table in section 33. The entry covers any person who must integrate their business with the Board or its computerised system and who fails to register, or, if registered, fails to integrate as required by law within the stipulated time as notified by the Board. The penalties are:
- a penalty of up to Rs 1 million;
- a second penalty of up to Rs 5 million if the offence continues one month after the first penalty; and
- sealing of business premises by an Inland Revenue officer, with or without a penalty, in the manner prescribed.
This corrects the earlier record, pk-sales-tax-act-expansion-2026. That record said that non-integration led to “suspension or blacklisting” and implied that integration was due from 1 July 2026. The Act provides neither. The sanction is the fine-and-sealing regime above, and the deadline is whatever the Board notifies.
What it means
The deadline comes from a Board notification, not from the Act. A registered person who is not yet integrated should look for the FBR notification that covers their sector. That notification is what starts the clock on the first penalty.
The escalation is steep. One month after a first penalty of up to Rs 1 million, a second penalty of up to Rs 5 million can follow. Sealing can be used at any point, with or without a fine, so in practice the risk to the business is closure rather than a fine.
Proof
Such person shall be liable to pay a penalty up to one million rupees, if he continues to commit the offence after one month of the imposition of first penalty, he shall be liable to second penalty of up to five million rupees.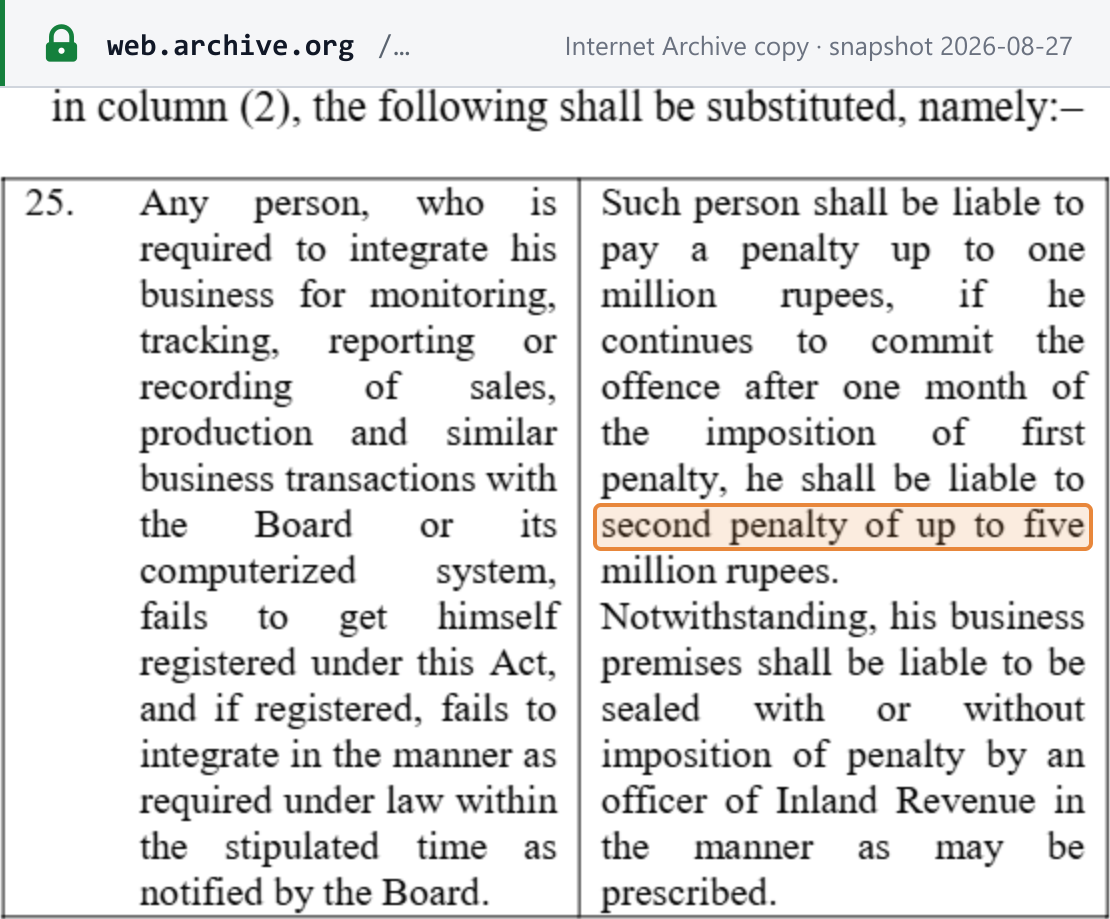 Source snapshot of the official page. Open full size ↗