Peru moves airport-service documents and joint-venture attribution documents into electronic issuance
- Jurisdiction
- Peru
- Tax
- VAT (IGV)
- Change type
- E-invoicing
- Status
- In force
- Impact
- Plan ahead
- Announced
- 26 March 2026
- Effective
- 1 August 2026
- Instrument
- PE-SUNAT-RS-48-2026
- Authority
- Superintendencia Nacional de Aduanas y de Administración Tributaria (SUNAT)
- Systems
- ERP, Invoicing, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Airport operators and concessionaires charging passenger service fees in Peru — CORPAC and the concession holders or local or regional governments that run an airport — and the operators of consortia, joint ventures and other collaboration contracts that do not keep accounting separate from their members, who issue the documento de atribución so participants can support their share of input tax credit, cost or expense. Collectors of the Garantía de Red Principal under Law 27133 are additionally designated as electronic issuers.
Operators of consortia, joint ventures and other collaboration contracts without independent accounting must issue the documento de atribución electronically through the SEE (as a DOAE) and transmit it to SUNAT within seven calendar days of issue. Airport operators charging passenger service fees must issue the DAE-SEAE through the SEE. A second set of provisions applies from 1 November 2026.
ERPInvoicingTax engineReporting
SUNAT Resolución de Superintendencia No. 000048-2026/SUNAT, dated 26 March 2026, requires two categories of document to be issued through the Sistema de Emisión Electrónica (SEE): the authorised document for airport services supplied to passengers (DAE-SEAE) and the documento de atribución used by operators of consortia, joint ventures and other collaboration contracts that do not keep accounting separate from their members (DOAE). It designates the issuers of those documents as SEE electronic issuers, additionally designates collectors of the Garantía de Red Principal under Law No. 27133 as SEE electronic issuers, and amends the rules governing electronic issuance. The resolution entered into force on 1 August 2026, except for paragraphs 4.3 and 4.4 of article 4 and two repealing provisions, which take effect on 1 November 2026.
What changed in detail
Resolución de Superintendencia N.° 000048-2026/SUNAT, dated 26 March 2026, extends Peru’s Sistema de Emisión Electrónica (SEE) to two further document types and designates the persons who must issue them as electronic issuers:
- The authorised document for airport services supplied to passengers (DAE-SEAE), previously issued outside the SEE under the Reglamento de Comprobantes de Pago.
- The documento de atribución (DOAE), used by the operator of a consortium, joint venture or other collaboration contract that does not keep accounting separate from its members, so that the other participants can support their share of input tax credit, cost or expense.
It additionally designates collectors of the Garantía de Red Principal under Law No. 27133 as SEE electronic issuers, and amends the rules governing electronic issuance — including the information SUNAT makes available in the proposals it publishes through the Sistema Integrado de Registros Electrónicos.
As published, the resolution was to enter into force on 1 August 2026, with a second tranche on 1 November 2026. It never did: Resolución de Superintendencia N.° 000143-2026/SUNAT, published in El Peruano on 31 July 2026, replaced its vigencia clause before that date. The resolution now enters into force on 1 January 2027, and the second tranche on 1 April 2027.
:::note Correction, 24 September 2026 This record previously stated that the resolution entered into force on 1 August 2026. That was wrong. RS 000143-2026/SUNAT, dated 29 July 2026 and published in El Peruano on 31 July 2026, rewrote the resolution’s own commencement provision: “La presente resolución entra en vigor el 1 de enero de 2027, salvo los párrafos 4.3 y 4.4 del artículo 4, la Cuarta Disposición Complementaria Derogatoria y el literal b) de la Octava Disposición Complementaria Derogatoria de la presente resolución, que entran en vigor el 1 de abril de 2027.” The first proof above is that provision; the second is the original clause it replaced.
Sources: SUNAT, RS 000143-2026 · El Peruano :::
What it means
The DOAE is the part with the widest reach. Collaboration contracts without independent accounting are common in Peruvian mining, construction and energy, and the attribution document is what lets each participant claim its share of input IGV. Moving it into the SEE means the operator has to transmit it to SUNAT within seven calendar days of issue, and a document transmitted late loses its status as a DOAE even if the participant already received it.
There is also an availability obligation that is easy to miss: the issuer must provide an authenticated web route through which the participant can read, download and print the document for a year from issue.
Note the dates carefully. The resolution is dated 26 March 2026, was due to start on 1 August 2026, and was postponed the day before: nothing in it applies until 1 January 2027, and a further set of provisions starts on 1 April 2027. Anyone who built against the August date has more time, not less; the obligations themselves are unchanged.
Proof
La presente resolución entra en vigor el 1 de enero de 2027, salvo los párrafos 4.3 y 4.4 del artículo 4, la Cuarta Disposición Complementaria Derogatoria y el literal b) de la Octava Disposición Complementaria Derogatoria de la presente resolución, que entran en vigor el 1 de abril de 2027.This resolution enters into force on 1 January 2027, except for paragraphs 4.3 and 4.4 of article 4, the Fourth Repealing Complementary Provision and subparagraph (b) of the Eighth Repealing Complementary Provision of this resolution, which enter into force on 1 April 2027.
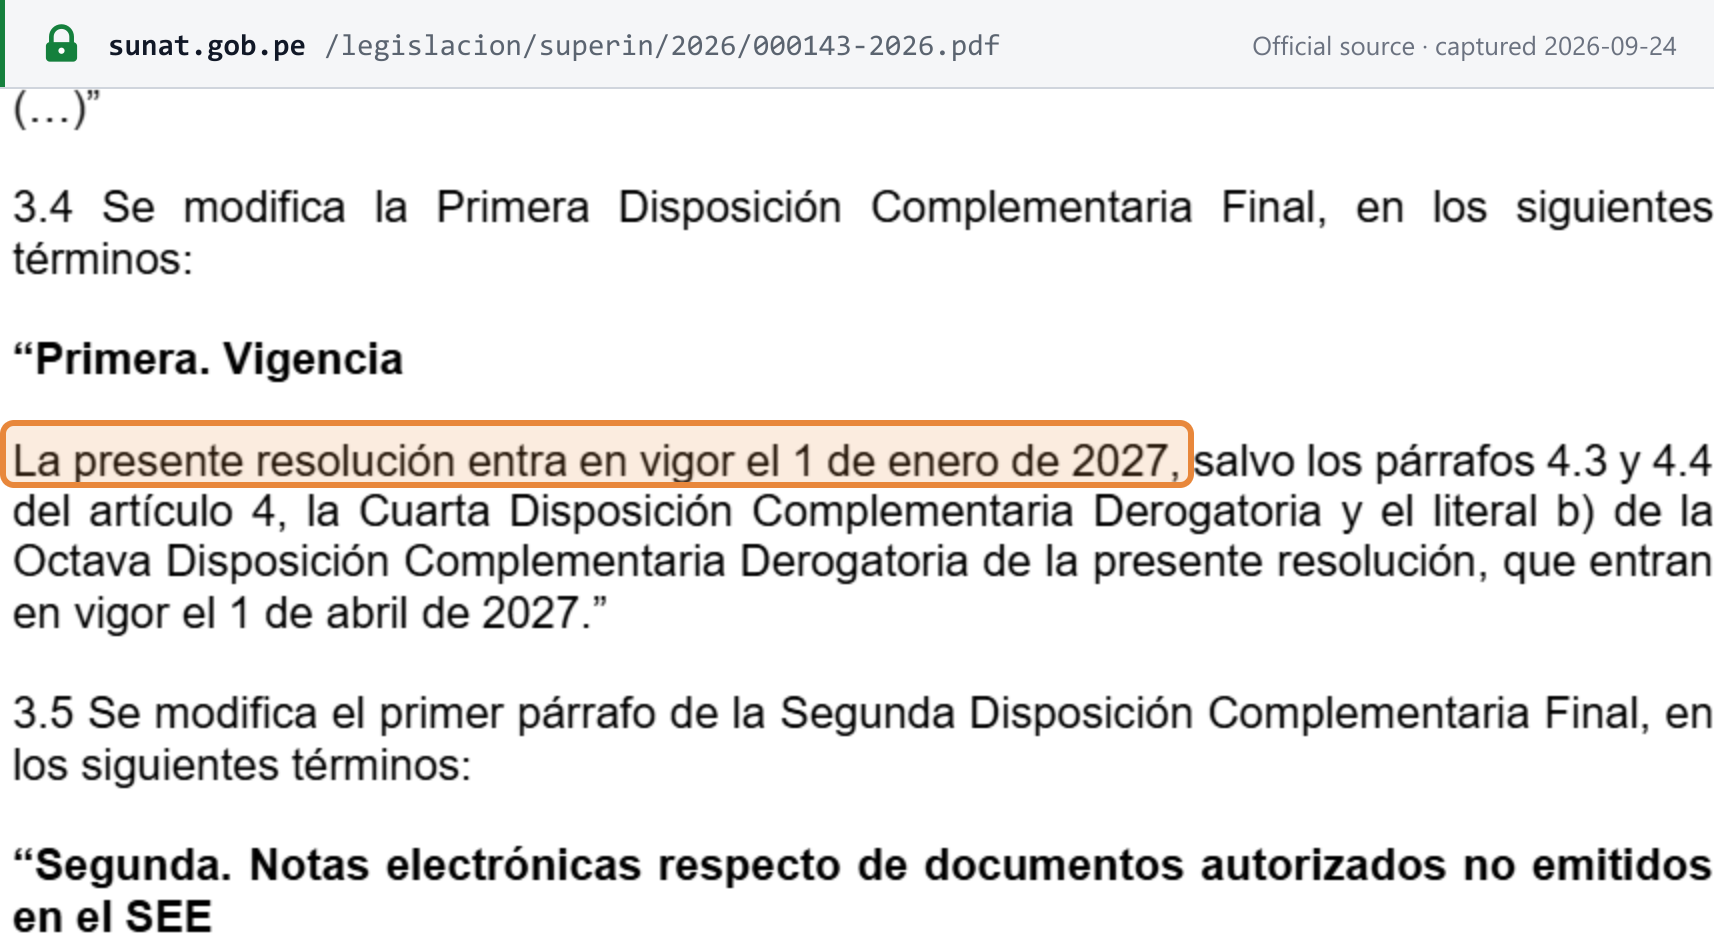 Source snapshot of the official page. Open full size ↗
La presente resolución entra en vigor el 1 de agosto de 2026, salvo los párrafos 4.3 y 4.4 del artículo 4, la cuarta disposición complementaria derogatoria y el literal b) de la octava disposición complementaria derogatoria de la presente resolución, que entran en vigor el 1 de noviembre de 2026.This resolution enters into force on 1 August 2026, except for paragraphs 4.3 and 4.4 of article 4, the fourth repealing complementary provision and subparagraph (b) of the eighth repealing complementary provision of this resolution, which enter into force on 1 November 2026.
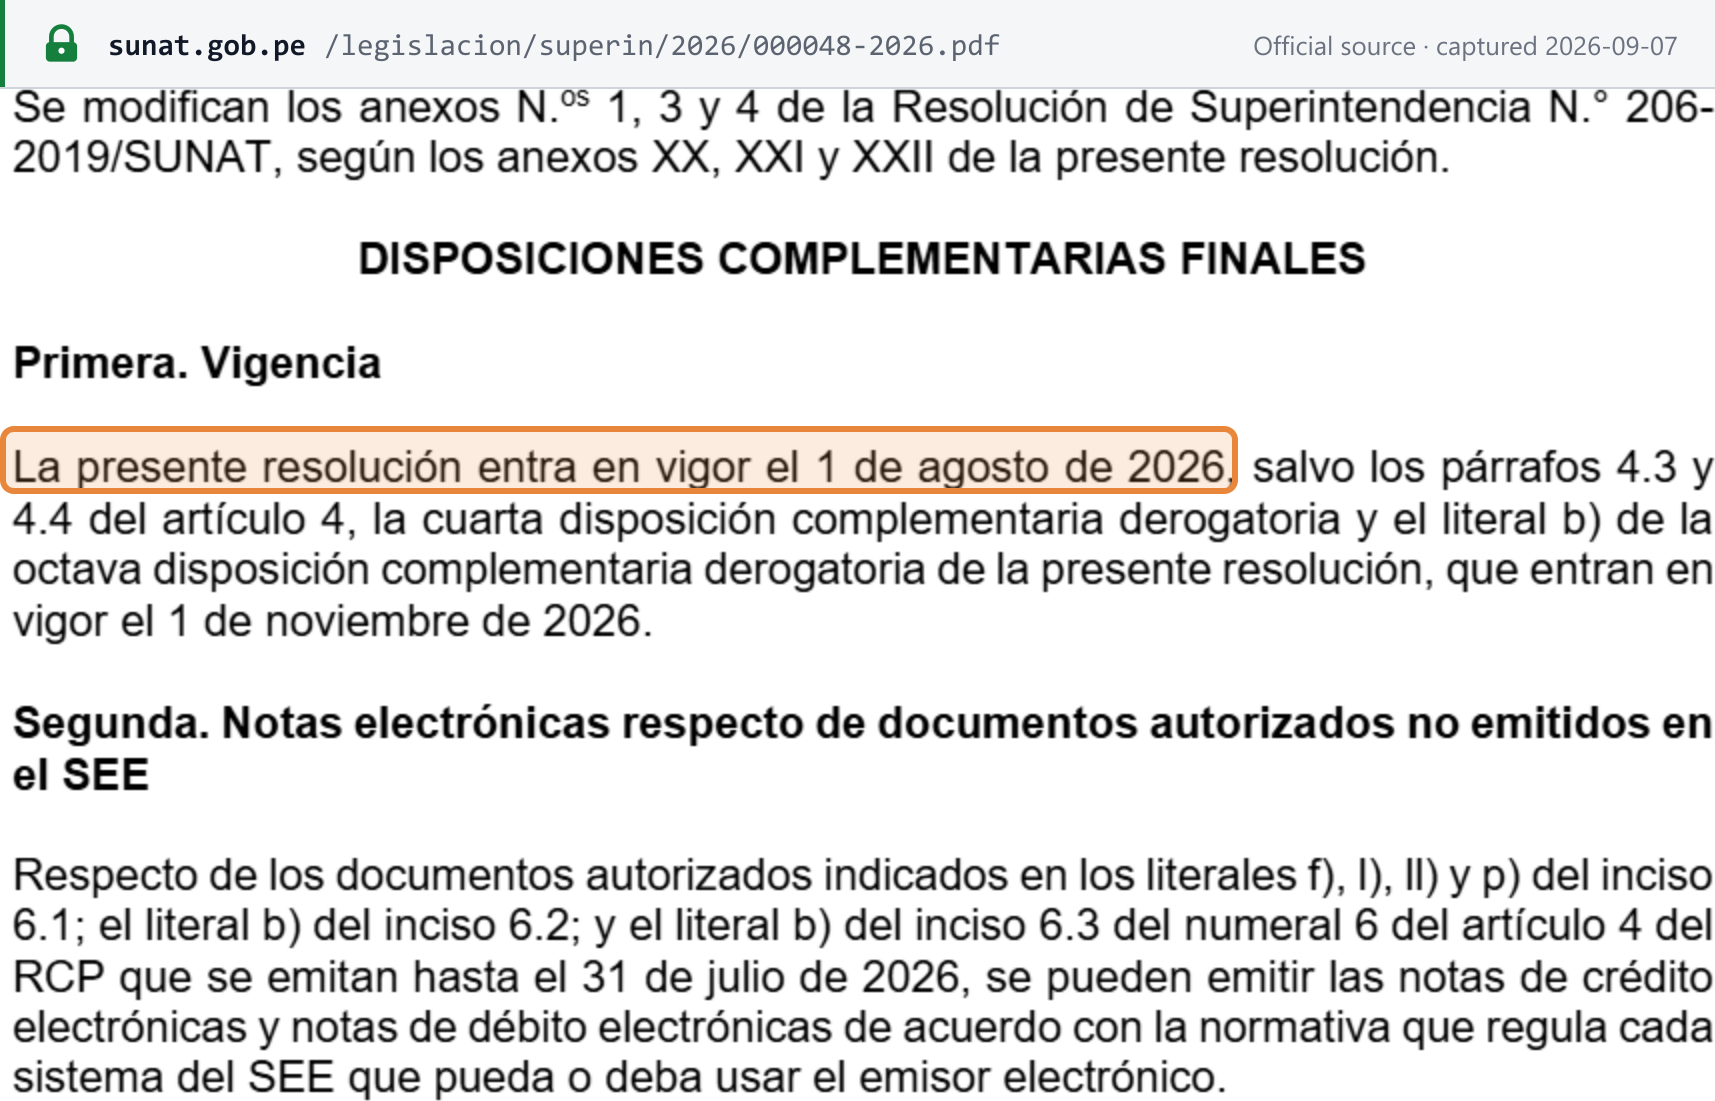 Source snapshot of the official page. Open full size ↗