SUNAT extends penalty relief for electronic sales and purchase register breaches under SIRE
- Jurisdiction
- Peru
- Tax
- VAT (IGV)
- Change type
- Compliance
- Status
- In force
- Impact
- Plan ahead
- Announced
- 31 August 2026
- Effective
- 31 August 2026
- Authority
- Superintendencia Nacional de Aduanas y de Administración Tributaria (SUNAT)
- Systems
- Reporting, ERP
- Verified
- Fetched from official source · high confidence
Peruvian taxpayers required to keep the electronic sales and income register (RVIE) and the electronic purchase register (RCE) through the Sistema Integrado de Registros Electrónicos (SIRE) — in practice, taxpayers migrated onto SIRE who have fallen behind on generating or correcting those registers. The relief concerns penalties for the covered infractions; the underlying obligation to keep the registers is unchanged.
Taxpayers behind on electronic sales and purchase register obligations in SIRE have additional time: SUNAT will not penalise the covered infractions, and non-compliant register generation can be corrected with the corresponding SIRE adjustments.
ReportingERP
SUNAT extended its discretionary power not to penalise certain infractions relating to the keeping of the electronic sales and income register (RVIE) and the electronic purchase register (RCE) through the Sistema Integrado de Registros Electrónicos (SIRE), by Resolución de Superintendencia Nacional Adjunta de Tributos Internos No. 000041-2026-SUNAT/700000, published on SUNAT's electronic-receipt portal on 31 August 2026.
What changed in detail
Resolución de Superintendencia Nacional Adjunta de Tributos Internos N.° 000041-2026-SUNAT/700000 extends SUNAT’s facultad discrecional — its discretion not to apply a sanction — to certain infractions connected with keeping the RVIE and RCE registers through SIRE.
SUNAT published the resolution in the Normas Legales section of its electronic-receipt portal, where the page was last modified on 31 August 2026.
Discretionary non-sanction is a standing feature of Peruvian tax administration: the obligation and the infraction both remain on the books, and SUNAT simply undertakes not to impose the penalty for the covered conduct and period.
What it means
This is relief from penalties, not from the obligation. Registers still have to be generated and corrected; what changes is the consequence of having been late.
The practical read is that SIRE migration continues to run behind schedule, and SUNAT is managing that with successive extensions of discretion rather than by moving the underlying deadlines. That pattern is worth planning around: a taxpayer relying on the current relief should still be closing the gap, because each extension has so far been time-boxed rather than permanent.
Proof
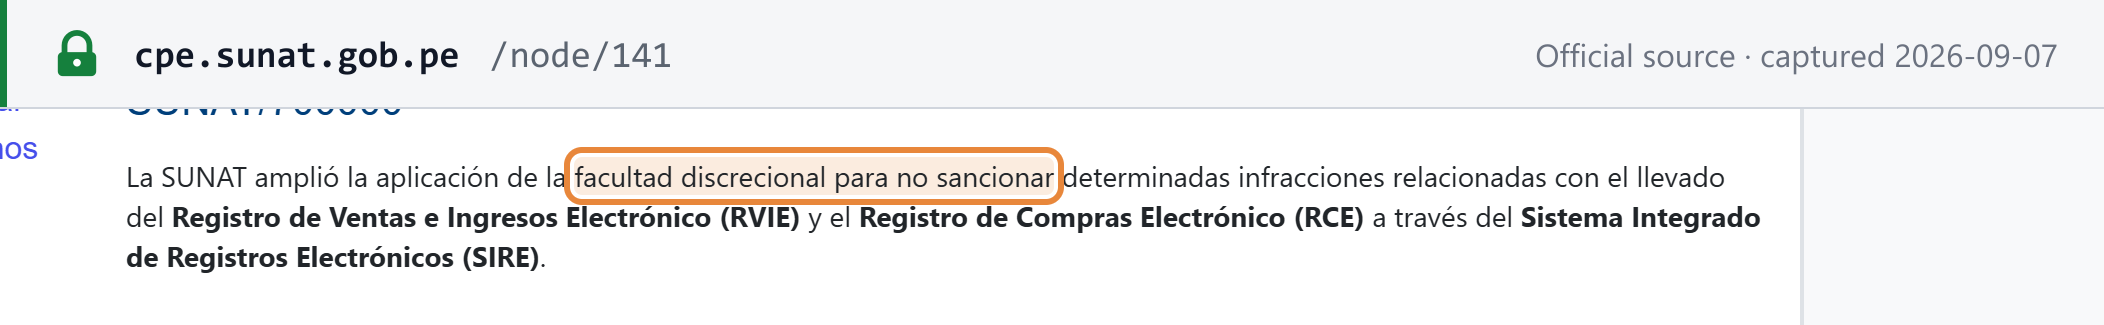
La SUNAT amplió la aplicación de la facultad discrecional para no sancionar determinadas infracciones relacionadas con el llevado del Registro de Ventas e Ingresos Electrónico (RVIE) y el Registro de Compras Electrónico (RCE) a través del Sistema Integrado de Registros Electrónicos (SIRE)SUNAT has extended the application of its discretionary power not to penalise certain infractions relating to the keeping of the Electronic Sales and Income Register (RVIE) and the Electronic Purchase Register (RCE) through the Integrated System of Electronic Registers (SIRE).
 Source snapshot of the official page. Open full size ↗