Poland rewrites VAT Act art. 99(12) so liability follows the return unless the tax office determines otherwise, from 1 October 2026
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 25 June 2026
- Effective
- 1 October 2026
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Systems
- Reporting
- Verified
- Fetched from official source · high confidence
Polish VAT payers filing returns, including those claiming refunds or carrying input tax forward.
No action — monitoring only.
Reporting
Article 11 of the Act of 29 May 2026 amending the Tax Ordinance and certain other acts (Dz.U. 2026 poz. 846, published 25 June 2026) gives art. 99(12) of the VAT Act a new wording under which the tax liability, refund of the difference, refund of input tax, the difference under art. 87(1) and input tax carried forward are taken in the amount shown in the tax return unless the tax authority determines them otherwise. The Act enters into force on 1 October 2026 (art. 11 is not among the excepted provisions).
What changed in detail
Article 11 of the Act of 29 May 2026 amending the Tax Ordinance and certain other acts (Dz.U. 2026 poz. 846, published 25 June 2026) gives art. 99(12) of the VAT Act a new wording.
Under it, the tax liability, the refund of the difference, the refund of input tax, the difference under art. 87(1) and the input tax carried forward are taken in the amount shown in the tax return, unless the tax authority determines them in a different amount.
The Act enters into force on 1 October 2026. Article 11 is not among the excepted provisions.
What it means
The default is the return: the amounts a taxpayer declares stand unless the tax office determines otherwise. That puts weight on getting the return right, because the declared figure becomes the baseline for refunds and carry-forwards. The rule changes the wording of art. 99(12), so check how it interacts with correction procedures before relying on it.
Proof
„12. Zobowiązanie podatkowe, zwrot różnicy podatku, zwrot podatku naliczonego, różnicę podatku, o której mowa w art. 87 ust. 1, oraz podatek naliczony do odliczenia w następnych okresach rozliczeniowych przyjmuje się w wysokości wynikającej z deklaracji podatkowej, chyba że organ podatkowy określi je w innej wysokości.”.12. The tax liability, refund of the difference in tax, refund of input tax, the difference in tax referred to in art. 87(1), and input tax to be deducted in subsequent settlement periods are taken in the amount resulting from the tax return, unless the tax authority determines them in a different amount.
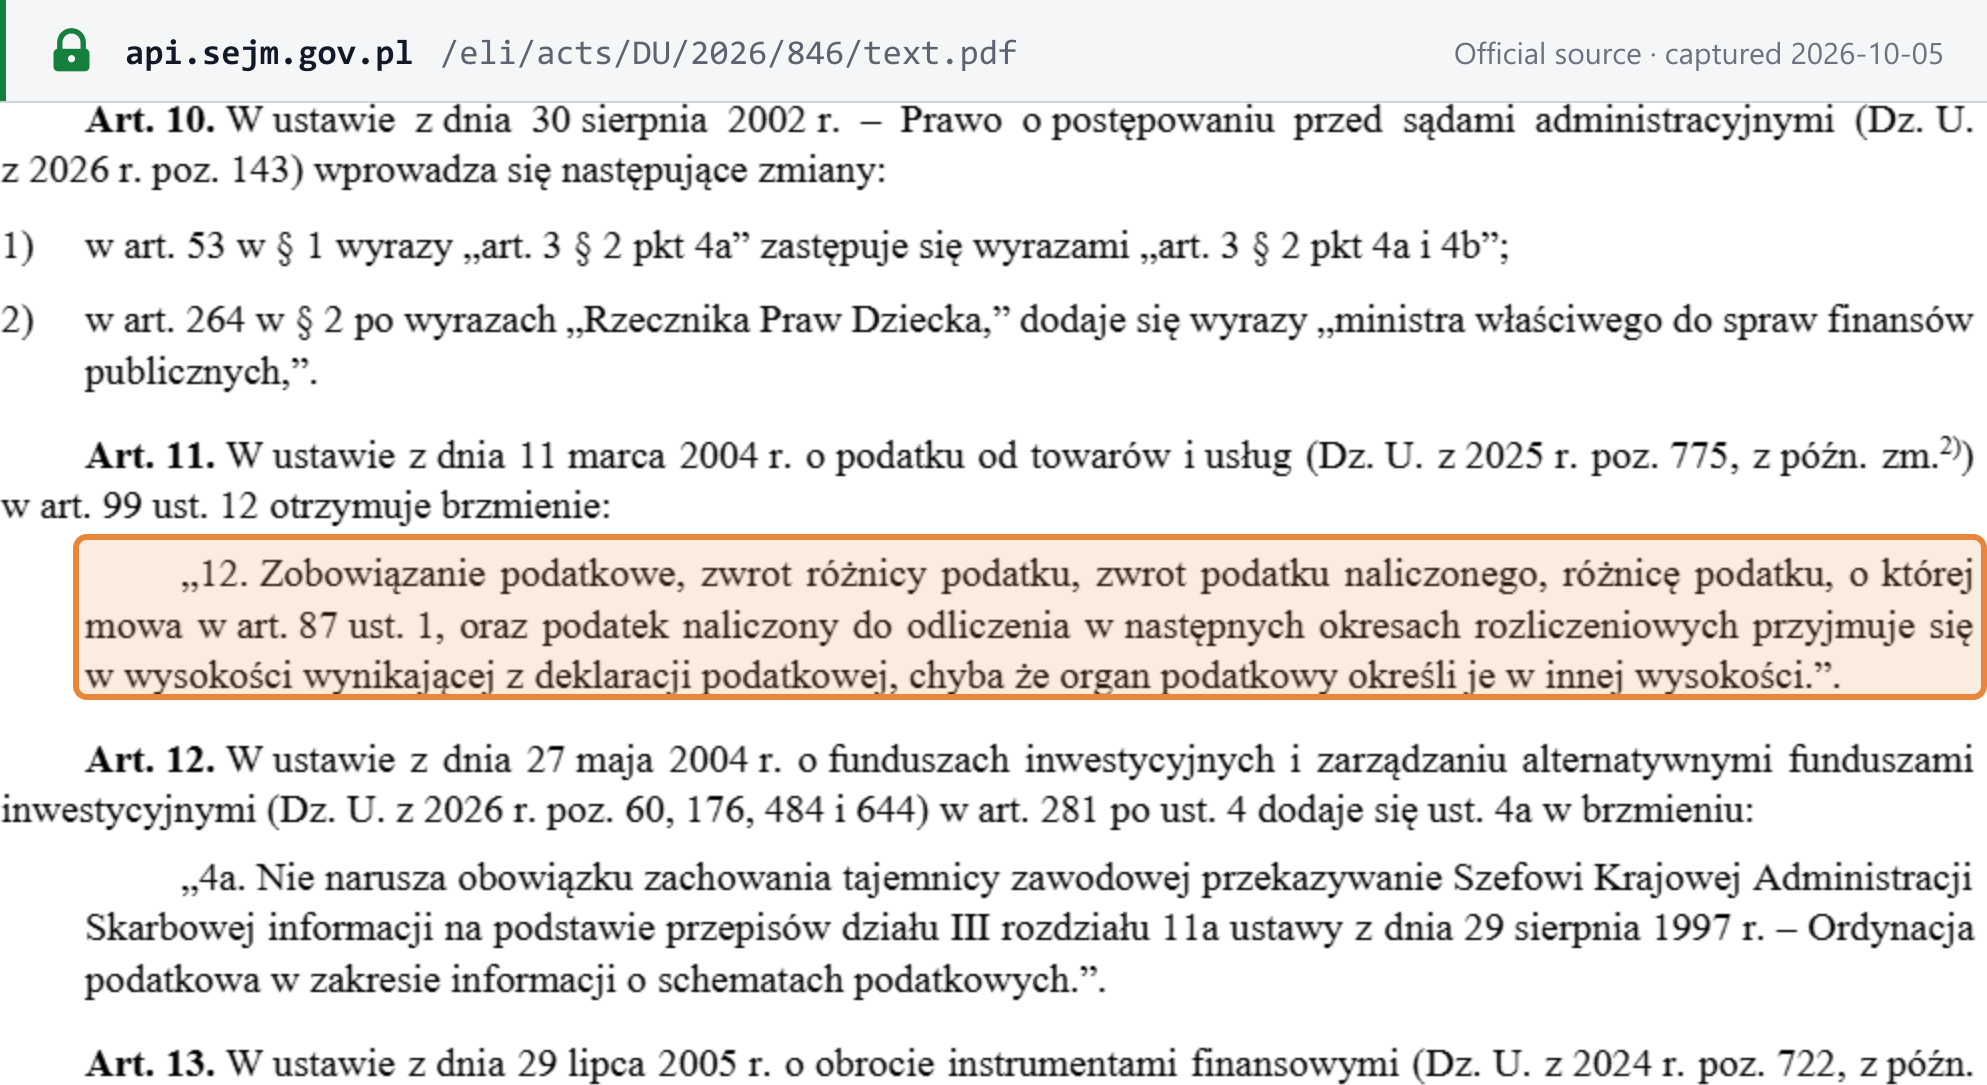 Source snapshot of the official page. Open full size ↗